Once upon a time, goldsmiths fabricated gold coins of standardised weight and purity. This made them a trusted source of gold coins. The goldsmiths also owned a safe where they stored their own gold. Other people wanted to store their gold there too because those safes were well-guarded. And so the goldsmiths began to rent out safe storage. People storing their gold with the goldsmith received a voucher certifying the amount of gold they brought in.
At first, these vouchers could only be collected by the original depositor. Later on, any holder of the voucher could collect the deposit. Another innovation was making standard vouchers representing 1, 2, 5 or 10 units. From then on people began to use them as money as paper money is more convenient than gold coins. And so depositors rarely came to collect their gold and it remained inside the vaults of the goldsmiths.
Modern banking
Some goldsmiths also lent out their own gold at interest. As depositors rarely came in to collect their gold, they discovered they could also lend out the gold brought in by the depositors. When the depositors found out about this, they demanded interest on their deposits too. At this point, modern banking took off and paper money became known as banknotes.
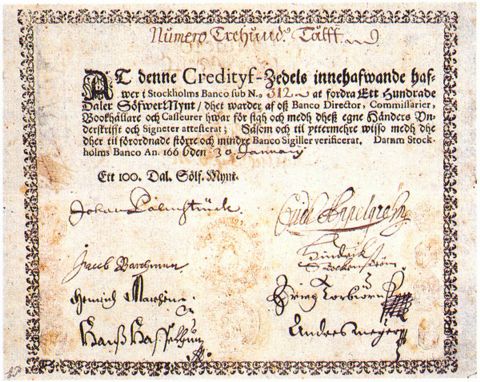
Credit note’s holder, Stockholm’s Banco sub no. 312
Borrowers preferred paper money too so the goldsmiths, who had become bankers, found out that they could lend out more money than they had gold in their vaults. They began to create money out of thin air. This is called fractional reserve banking as not all deposits were backed by gold reserves. The new money was spent on new businesses that hired new people so the economy boomed.
When depositors discovered that there were more bank notes circulating than there was gold in the vaults of the bank, the scheme could run into trouble if all depositors came in at the same time to demand their gold, but this rarely happened. Depositors received interest so they kept their deposits in the bank. They trusted their bank as long as they believed that debtors were paying back their loans.
Bank runs
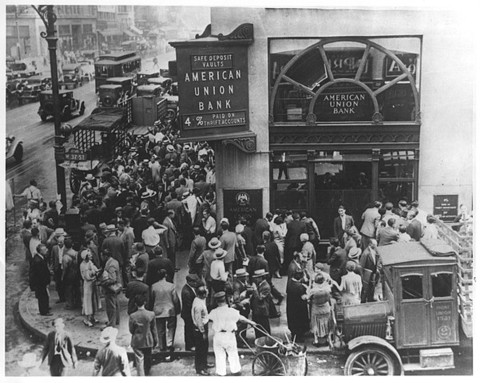
But sometimes people began to doubt that the bank was safe and worried depositors came to the bank to exchange their banknotes and deposits for gold coins. This is called a bank run. If too many people came in at the same time, the bank could run out of gold and close down because not all the gold was there. As a result, the bank’s notes and deposits could become worthless.
A crowd at New York’s American Union Bank during a bank run in the Great Depression
People who lost their money had less money to spend. This could hurt sales, causing businesses to run into trouble and default on their debts. As a consequence, depositors at other banks sometimes feared that their bank could go bankrupt too, leading to more bank runs. This could escalate into a financial crisis and an economic depression. This happened in the United States during the Great Depression of the 1930s.
Regulations and central banks
To forestall financial crises and to deal with them if they occur, banks were required to have a minimum amount of gold available in order to pay back depositors. Central banks were created to support banks by supplying additional gold if too many depositors came in to collect their gold at the same time. Central banks could still run out of gold but this was solved by ending the gold backing of currencies. Nowadays central banks can print new dollars or euros to cope with any shortfall. Regulations limit the number of loans banks make and therefore the amount of money that exists.
But everyone can lend to everyone. There are ways to circumvent the regulations imposed on banks. For example, corporations can issue bonds or use crowdfunding. And a lot of lending nowadays happens outside the official banking sector in institutions that are not subject to these regulations. Human imagination is the only limit to the amount of debt that can exist. And as long as people expect that those debts will be repaid, even if it is with new debts, there can be trust in these debts. But the financial crisis of 2008 demonstrated that this trust can disappear very suddenly.
Featured image: A goldsmith in his shop. Peter Christus (1449). Metropolitan Museum of Art. Wikimedia Commons. Public Domain.
Until very recently nearly everyone lived in abject poverty. Most people had barely enough to survive. In 1651 Thomas Hobbes depicted the life of man as poor, nasty, brutish, and short. Yet a few centuries later a miracle had happened. Many people are still poor but more people suffer from obesity than from hunger while the life expectancy in the poorest countries exceeds that of the Netherlands in 1750, the richest country in the world in the wake of the Industrial Revolution.
In 1516 Thomas More wrote his famous novel about a fictional island named Utopia. Life in Utopia was nearly as good as in the Garden of Eden. The Utopians worked six hours per day and took whatever they needed. His book inspired writers and dreamers to think of a better world while leaving the hard work to entrepreneurs, labourers and engineers. Today many of us have more than they need but still we work hard and feel insecure about the future.
Why is that? The answer lies within the nature of capitalism. It is not enough that we just work to buy the things we need. We must work harder to buy more, otherwise businesses go bankrupt, investors lose money, and people will be unemployed and left without income. In other words, the economy must grow. That worked well in the last few centuries, and it brought us many good things, but it may be about to kill us now.
People in traditional cultures didn’t need much. They were easily satisfied. Many modern people in capitalist societies believe they never have enough. You can always go for a bigger house, a more expensive car, or more luxury items. Many of us do not need more but the advertisement industry makes us believe that we do. We believe in scarcity even when there is abundance. And so the economy must grow. That is what they tell us.
But what are the consequences of this belief? If you eat too much this is great for business profits. And if you become obese as a consequence and need drugs for that reason, you again contribute to business profits so this is even better. Meanwhile we are using the resources of this planet in a much faster pace than nature can replenish. Humanity is standing before the abyss. Civilisation as it is will not continue for much longer. The end is near.
What has this to do with interest? If we want more products and services, we need more businesses, so we need investments. To do investments, we need savings. And to make people save, we need interest to make saving attractive. Consequently investments need to be profitable to pay for the interest. But there can be too much of a good thing. If we don’t need more stuff, we don’t need more savings, and interest rates go down.
A sustainable and humane economy?
Is it possible for humanity to live in harmony with itself and nature? We work harder than ever before and in doing so we destroy life on this planet. It seems hard to change this. If you organise production differently then your products might not be sold at a price that covers the cost to make them. In a market economy the value of a product is the price it fetches in the market. Marketing often comes down to inflating the market price of a product or a service to make more profit.
In the past there have been two fundamentally different approaches to the economy. For instance, before Germany became united in 1990, there were a capitalist and a socialist Germany. Socialist Germany ensured that everyone was employed. People in socialist Germany had enough but they had little choice as to what products they could buy. For instance, in socialist Germany there were two kinds of yoghurt while there were sixty in capitalist Germany.
And there was little freedom in socialist Germany. The secret police were everywhere. When Germany became united the socialist economy collapsed. Socialist corporations suddenly were bankrupt because no-one wanted to buy the products they produced. The ensuing reorganisation of the economy led to mass lay-offs and a staggering rise in unemployment. Ultimately 60% of the jobs in the former socialist firms disappeared.
Many lives and communities in former socialist Germany were destroyed. And people suddenly felt insecure about their future as businesses had to compete and make a profit in order to survive. In a market economy efficiency considerations determine what is produced. These efficiency considerations are the result of customer preferences as well as the requirement to make a profit. Loss-making businesses usually can’t attract capital in a market economy.
The quest for efficiency results in fewer and fewer people producing the things we need. To keep everyone employed in a capitalist economy unnecessary products and services must be produced, causing a rapid depletion of scarce resources as well as lots of waste. At least in theory we work can a few hours per day so we have more time for our mobile phone and each other. It may also be possible to free up resources to address poverty and other social problems.
And what has this to do with interest? The profit a corporation is expected to make should be higher than the interest rate in the markets for money and capital. Because what’s the point in making the effort and taking the risk of running a business if you can get the same return on a savings account? And so it appears that with negative interest rates corporations with zero profits can survive and that the economy doesn’t need to grow.
Share of Labour Compensation in GDP at Current National Prices for United States
The road to inequality
Not so long ago an economist wrote a book that sent a shock-wave through the economic world because of stating a major cause of wealth inequality, which is that the return on capital usually is higher than the rate of economic growth. Capitalists reinvest most of their profits so capital usually grows faster than the economy most of the time. It can be proven beyond any doubt that capital can’t grow faster than the economy forever. Something will have to give at some point.
And what has this to do with interest? Interest is any return on capital. Interest income is the income of capitalists. That includes business profits and interest on bonds. The graph shows that labour income as part of the economy has diminished in recent decades in the United States. And that is because the capital share of national income has risen. In the past depressions and wars destroyed a lot of capital. Since 1945 there hasn’t been a serious depression or a world war.
The capitalist economy is like a game of monopoly. First everyone is doing great and capital is built in the form of housing and hotels. At some point some people can’t pay their bills anymore. To keep the game going, the winners can lend money to the losers. But at some point the losers can’t pay the interest any more. To keep the game going, interest rates must be lowered, so they can borrow more. But at some point some people can’t pay the interest again.
This happens in the real economy too. In a game of Monopoly we can start all over again. In the real economy that’s not an option. It would mean closing down factories in another great depression or destroying houses in another world war. So the game must continue. In Monopoly the rich can lend money at negative interest rates to the rest so that they can pay their bills. In the real economy this may be possible too.
Monopoly features a scheme that looks like a universal basic income. Every time you finish a round you get a fixed sum of money from the bank. At some point the bank may end up empty. The rich can then lend money to the bank at a negative interest rate to pay for it. It might seem a stupid thing to do because Monopoly is just a game. But the real economy is not. It may need an income guarantee for everyone financed by the rich.
An outline of the future economy
Can we have an economy that is humane and in harmony with nature? A few centuries ago no-one would have believed that we could live the way we do today and most people would have believed that it is more likely that unicorns do exist. If excess resource consuming consumption is to be curtailed, fewer options for consumers remain, for instance there may only be organic products, and supermarkets in the future might look a bit like those in former socialist Germany.
That may not be so bad. People in socialist Cuba live as long as people in the United States despite the United States spending more on healthcare than any other country in the world. Cubans eat no fast food so they live a healthier life style. And Cubans suffer less from a negative self image than people who are exposed to the advertisement industry. Advertisements aim to make us unhappy with ourselves and what we have in order to make us buy more products and services.
Like in former socialist Germany there isn’t much freedom in Cuba. If the government is to regulate the fat content in fast food or the sugar content in sodas then we lose our freedom to become obese. Alternatively, the government could even end our freedom to destroy life on this planet and kill our children. That may be oppression. But the alternative may be a collective suicide of humanity. Even though socialism failed we may have to pick the best parts out of it and integrate them into a market economy.
If the most resource consuming non-essential activities are to be axed, entire industries will be wiped out like in socialist Germany. One can think of making air travel sustainable and what that will with ticket prices. It is bad for economic growth. Many people would not like this. Still, life in a future sustainable market economy can be much more agreeable than life in Cuba or former socialist Germany.
So what has this to do with interest? A dramatic change to make the economy sustainable can cause a massive economic shock like the Great Depression. The economy can soon recover if interest rates can go negative. Before you say that it is more likely that unicorns exist, this has been tested during the Great Depression. The outcome is dubbed the Miracle of Wörgl. And evidence for the existence of unicorns has not yet been so forthcoming.
If interest rates are low then the creators of ideas and makers of things are rewarded more. They are the entrepreneurs and labourers rather than the owners of capital. It is in the spirit of Silvio Gesell who believed that labour and creativity should be rewarded and not the passive ownership of capital. Only when there is a shortage of capital or more demand for goods and services than there is supply, people need to be encouraged to save.
The economy is already constrained by a lack of demand rather than supply. That will be even more so when excessive consumption is to be curtailed and the rich have fewer options to spend their money on. And so it may become possible to fund an income guarantee with income taxes as well as negative interest on government debt. This can improve the bargaining position of labourers.
It is better to have an income guarantee rather than a universal basic income because that would be cheaper. There is little to gain from handing out money to people that already have enough. And the scheme should provide an incentive to work. A simple example can explain how that might work out. Assume there is an income guarantee of € 800 per month and a 50% income tax. The following table shows the consequences for different income groups.
Perhaps it doesn’t feel right that people are being paid for doing nothing. But nowadays people are paid for producing and selling things we do not really need and by doing so they endanger our future. Someone who does nothing at all can be worth much more for society than a travelling salesperson, a trader on Wall Street or a constructor who builds mansions for the rich. Of course it is better that people do something useful and useful people should be rewarded for their efforts, but doing nothing is always better than doing something stupid, and having zero value is always better than having negative value.
Another question is how this can be paid for? The Miracle of Wörgl shows us that the economy can flourish without growth when interest rates are negative so that most people will be employed. Money can still be a motivator to run a business or to go to work but less so than in the present. It doesn’t have to stop people from starting a business. Many entrepreneurs didn’t intend to become rich. They just wanted to be an entrepreneur or believed in the product they were making or selling. Still, there is no doubt whatsoever that a humane economy in harmony with nature will be very different from the economy of today.
Featured image: Slums built on swamp land near a garbage dump in East Cipinang, Jakarta Indonesia. Jonathan McIntosh (2004).
Other images: Share of Labour Compensation in GDP at Current National Prices for United States. FED. Public Domain
A few centuries ago, over 99% of the world’s population lived in abject poverty. In 1651, Thomas Hobbes depicted human life as poor, nasty, brutish, and short. It had always been that way. Yet, a few centuries later, a miracle had occurred. Nowadays, more people suffer from obesity than from hunger. Today, the life expectancy in the poorest countries exceeds that of the Netherlands in 1750, the wealthiest nation at the dawn of the Industrial Revolution. This miracle is the result of science, innovations and a massive build-up of capital. How could that happen? One crucial reason is that interest rates fell from 30% in the Middle Ages to 5% in England at the start of the Industrial Revolution. Had interest rates not gone that low, the Industrial Revolution wouldn’t have started in the first place. Only, what caused interest rates to go that low?
In the economic arena, the interest rate is the outcome of an epic battle between ‘Time Preference’ and ‘Capitalist Spirit’ that raged for centuries. The capitalist spirit won. Ordinary people suffer from a condition known as time preference, which causes them to spend their money on frivolous items. They think, ‘Live today, because you can be dead tomorrow.’ Economists say they lack trust in the future. There are also capitalists, who are special people who suffer from an illness called the capitalist spirit. Rather than spending their money on frivolous items, they think, ‘Don’t live today, but invest, so you will have more money when you die.’ Economists say that they have trust in the future.
And so, capitalists save and invest while ordinary people work for them and buy the products and services their ventures produce. When time preference prevails, there is little saving and high interest rates. People are poor because there is a lack of investment capital. When the capitalist spirit prevails, there are ample savings, low interest rates, and wealthy individuals with excess capital to invest. This miracle wouldn’t have happened without low interest rates, since investment returns must exceed interest rates, and low rates can’t persist without efficient financial markets and trust in political and economic institutions. So, how did that come about?
In the Middle Ages, Europeans gradually developed a capitalist spirit. The ethic of the merchant gradually spread, so that money and profit, rather than Christian values, came to drive Europeans. They found new trade routes and exploited their colonies. Initially, Spain and Portugal led the way, but their kings were short of cash and imposed heavy taxes on their people. Many merchants moved to the Dutch Republic, which was more business-friendly because the propertied classes ran it. The Dutch didn’t have a strong state with an army, so taxes were lower as well. The Dutch invented the stock market, featuring publicly traded shares, a crucial financial innovation that helps manage risk. Since then, investors have been able to invest in a corporation at any time and sell their investment at any time.
Later, Great Britain became the dominant power. The British business elite, who paid most of the taxes, didn’t like paying for incompetence and corruption. After they had gained control of the British state during the Glorious Revolution of 1689, they forced it to improve its competence. The British invented fractional reserve banking with a central bank, thereby creating efficient financial markets. Their colonial empire also expanded, so that they came to control the largest market, which favoured economies of scale. Once the competent government and financial innovations were in place, the Industrial Revolution took off. Low interest rates made long-term investments in machines profitable.
Once interest rates had decreased, economic growth accelerated, enabling investment returns to cover interest payments and allowing financial markets to expand, thereby driving further growth. The capitalist miracle is that financial markets helped boost trade and production by creating money that doesn’t exist to start businesses that don’t yet exist to make products that the people those businesses will hire will buy with this newly created money. Financial markets are at the basis of the capitalist economy. When growth slows, interest-bearing debt may collapse the global economy, but so far financial innovators have devised new lending schemes, aided by low interest rates. Low interest rates make an economy possible, not high ones. And trust makes low interest rates possible.
Usury: a hidden cancer
As long as there is growth, there is more stuff to dole out, even though the division of the fruits of capitalism has its shortcomings. Yet, that applies to every economic organisation. Personal qualities explain some inequality. Some people work harder, some are better entrepreneurs, some are more frugal, some are more useful, and some are better at exploiting others for their personal gain. Or they inherit estates. These people usually end up wealthier. The success of capitalism comes from increasing the size of the pie rather than from its fair division. The primary driving force in the capitalist system has little to do with individual qualities. It is profit or interest. Interest comprises all returns on capital. Interest is the reason why the rich get richer at the expense of the rest.
Yet, the primary objection is that it will end in disaster. Since the Industrial Revolution, we have become trapped in a global competition driven by innovation and economies of scale. As a result, a few oligarchs have become exceptionally wealthy, often by cornering markets. The tech sector is an example. Wealth inequality will be the most urgent immediate challenge once there is less to go around. Some think it is unacceptable that people are starving while the elites fly around in private jets. Of course, the elites fund think tanks spreading propaganda that the current system is most efficient, which it is, so it is believable, so that you are to blame if you can’t compete.
The relationship with usury is not that clear. Yet, more efficient financial markets and lower interest rates enable lending, so there is more interest-bearing debt than in the past. Most people pay more interest than they receive. We pay interest through rent, taxes, and the prices of everything we buy. Interest works like a tax on poverty, with the poor paying for the benefit of the wealthy. Lower interest rates could benefit most people by lowering prices. Only, we don’t see that happening. That is because other factors interfere.
In a usury-based financial system, lower interest rates allow us to borrow more, putting more money into circulation and thereby contributing to rising prices. As we borrow more, we may end up paying even more interest. To improve their yields in a low-interest environment, capitalists invent new schemes, such as leveraged buyouts and vampire capitalism. Lower interest rates also enabled more predatory lending by making loan-sharking profitable even at higher default rates.
Worse yet, low interest rates have exacerbated the excesses in the financial system. That is because we live under a usurious financial system. Had the maximum interest rate been 7%, schemes such as loan sharking and leveraged buyouts wouldn’t be possible. That would require us to look after people in financial trouble and limit their freedom, rather than giving them the liberty to borrow. We allow it because the merchant’s ethics have become the foundation of our moral system. And that is no ethics at all. Yet, a world without merchants is a world without many comforts. That is why we accept the bribe and allow trade to make us dependent on governments and markets, so that we become cogs in the system. Interest plays a crucial role in this process by making the money flow. Things aren’t straightforward, so ‘interest is evil’ is simplistic and not a helpful approach. The alternative comes down to forgoing many of the comforts of modern life, as the Amish do.
What is usury?
When you ask some random individual what usury is, and you do get an answer, it might be charging an excessively high interest rate. Traditionally, usury referred to paying for the use of money. In other words, usury is charging interest on loans. In this traditional definition, the currency has a constant value, so the borrower must repay the same value. If a ruler debases the currency and halves its gold content, a lender has a legitimate claim on the same amount of gold, hence twice the amount of currency. The reasons why usury is damaging are:
Usury turns money into a tool of power, enabling the rich to exploit the poor.
Usury disrupts the circular flow of money, causing economic hardship.
Fixed interest payments cause financial instability as incomes fluctuate.
Making a profit from a business venture is not usury. Still, all capital income is interest, and interest contributes to wealth and income inequality, unless the interest rate is at or below the growth rate. Capitalism has raised living standards, so the prevailing view is that its benefits outweigh its drawbacks. And perhaps, it did for a long time. Today, capitalist economies excel in generating money for capitalists by turning energy and resources into waste and pollution to market non-essential products and services in the bullshit economy. Therefore, the drawbacks may now surpass the benefits. Yet, if there is no viable alternative, then what can you do?
The economist Piketty found that interest rates on capital were higher than the economic growth rate most of the time.1 That is unsustainable. It requires capital destruction to create new room for growth or lower interest rates. In the past, World War I, the Great Depression, and World War II annihilated vast amounts of capital through physical destruction and bankruptcies, creating new room for growth. And so did the end of communism in the 20th century. Eastern Europe, China and India became new centres of growth. The wave of capital seeking a return has finally reached Africa, the last frontier. Increasingly, growth comes from ‘wealth-creating’ non-essential activities in the bullshit economy, such as collecting large datasets to track consumer behaviour.
Value standard
The idea behind banning usury is that it is unfair for borrowers to return more than they borrowed. Traditionally, the poor borrowed from the rich, so charging interest would make them even poorer. If you borrow a loaf of bread, you return it. That is simple. Money, however, is an abstract measure of value, so what counts as usury and what does not requires a value standard. Islam forbids charging interest on money and debts and also prohibits the debasement of currency. According to Islamic law, money is gold or silver. Lenders should receive the same amount of gold or silver as repayment for the loan. There is, however, no reward for the risk of lending, which impedes capital formation. It is one of the reasons why the Industrial Revolution didn’t take off in the Islamic world.
A Natural Money currency serves as the standard of value, so usury refers to charging an interest rate above zero on loans. To serve as a standard, the currency must have a stable value. The Egyptian grain money’s value came from a backing by grain in granaries. During the gold standard, gold was the standard of value, as you could exchange national currencies for a fixed amount of gold. The backing of today’s fiat currencies is the economy. The Quantity Theory of Money states that Money Stock (M) * Velocity (V) = Price (P) * Quantity (Q), so Money Stock (M) depends on Velocity (V), Price (P) and Quantity (Q), and the value of a single unit, such as the euro, is M / units in circulation.
A grain or gold backing can give the currency a stable value because there is a limited amount of grain and gold. Such a limit doesn’t exist for fiat currencies. Still, Natural Money currency can serve as a stable value standard because its issuance depends on lenders’ willingness to accept negative interest rates. Lenders thus only lend when they expect the currency’s future value to remain sufficiently stable. When they don’t lend, the amount of money in circulation shrinks due to negative interest rates and debt repayments, allowing the currency’s value to increase and prices to decrease. Trust in the currency thus stems from persistent deflationary pressures, as negative interest rates consume the money supply, and the maximum interest rate constrains credit creation.
Efficiency argument
Presumably, so it is an assumption, most of what humans do makes no sense. One of the outcomes is that today’s global economy is overcapitalised due to massive over-investment in the bullshit economy, which is about transforming energy and resources into waste and pollution to make the rich richer in a rat race that ends with the end of humanity. If we are to correct that issue, near-term future growth rates will probably be negative, either as the result of an involuntary collapse or a managed decline, and the sustainable interest rate will also be negative. Once the world economy is on a sustainable footing again, sustainable growth may allow growth rates to become positive once more in the more distant future. A stable economy operating near the maximum growth rate, which can be negative, can achieve its full potential and full employment. That is what the ‘miracle of Wörgl’ suggests.
To illustrate the efficiency improvement that we might achieve by discontinuing the bullshit economy, everyone engaged in air travel or cryptocurrency could do something useful instead, like building homes, caring for the elderly, practising organic farming, removing weeds rather than using pesticides, or joining the police force to keep neighbourhoods safe. It only takes a different approach to economics. There are countless other bullshit occupations, so you can imagine the improvement when all these people do something that benefits society. If 50% of the people worked on bullshit, economic efficiency could increase by 200%, a whopping figure.
When average investment returns are near their sustainable maximum, real interest rates are also near their sustainable maximum. The usury-based economy is unstable due to credit expansions and contractions, so it often does not operate at its sustainable maximum, reducing its efficiency. Natural Money helps achieve a stable economy and minimise financial system risk, thereby realising the sustainable maximum. It follows that real interest rates with Natural Money are higher, even when economic growth rates are positive. The maximum nominal interest rate is zero, so higher real rates translate into currency appreciation, allowing a zero interest rate to yield a positive absolute return.
A simple calculation illustrates this view. Economists assume there is a link between the amount of money (M) in circulation and prices in the equation Money Stock (M) * Velocity (V) = Price (P) * Quantity (Q). If ΔP, ΔM and ΔQ are sufficiently small, and velocity is constant, so that ΔV = 0, then it is possible to approximate this equation with %ΔP = %ΔM – %ΔQ, where %ΔP is the percentage change in price level, %ΔM is the percentage change in money stock, %ΔV is the percentage change in money velocity, and %ΔQ is the percentage change in the quantity of production.
The velocity of money (V) for Natural Money might be higher than for interest-bearing currency, and this could be accompanied by a smaller money stock (M). Still, the velocity is likely to remain constant, as the economic picture is expected to remain stable. Now, it is possible to calculate the real interest rate (r) as the nominal interest rate (i) minus the inflation rate (%ΔP), so that r = i – (%ΔM + %ΔQ).
Suppose the long-term average economic growth rate for interest-bearing money is 2%. For Natural Money, it might be 3% because the economy is more often performing at its maximum potential. Assume that the long-term average annual increase in the money supply for interest-bearing money is 6%. For Natural Money, it is 0%. The long-term price inflation rate could then be 4% for interest-bearing money. With Natural Money, there could be a 3% price deflation rate as the economy grows at 3% with a stable money supply. We can then produce the following calculation:
situation
usury money
Natural Money
nominal interest rate (i)
+3%
-2%
change in money supply (ΔM)
+6%
0%
economic growth (ΔQ)
+2%
+3%
real interest rate (r = i – ΔM + ΔQ)
-1%
+1%
Natural Money can increase economic growth, allowing real interest rates to be higher. Furthermore, because Natural Money has several stabilisers that reduce financial system risk, the level of risk is likely lower. As a result, the risk-reward ratios associated with Natural Money are better than those in the current usury-based financial system. In other words, the same real interest rate in a usury-free financial system is a better deal because it entails fewer risks. Hence, a usury-free financial system based on Natural Money is more efficient, so there will be capital flight from the usury-based economy to the usury-free economy after Natural Money is implemented on a large enough scale. The efficiency argument demonstrates that usurious finance is parasitic.
The real interest rate may improve more than the economic growth rate due to lower financial-sector profits from phasing out exploitative parasitic activities, such as interest-bearing consumer credit. Without credit card payments, consumers have more disposable income. Furthermore, economic and financial stability can reduce investment risks, thereby reducing the need for financial sector intermediation. The financial instability and the need for government and central bank interventions in the usury-based financial system create opportunities for politically connected and other savvy and informed individuals, sometimes referred to as ‘financial parasites’, to enrich themselves at the expense of the general public. The higher efficiency of Natural Money could end that.
The efficiency argument still applies when we switch to a values-driven, people-friendly economy that operates in harmony with nature. The financial inefficiency of such an economy stems from its limited ability to generate money for investors by transforming energy and natural resources into waste and pollution, producing unnecessary products and services in the bullshit economy. That depresses interest rates. And so, it is not an inefficiency in the financial sector. With Natural Money, a values-driven, people-friendly economy can remain operational thanks to the financial system’s efficiency. Terminating the bullshit economy in a usury-based financial system will also depress interest rates, but may bring about an economic collapse because negative interest rates are impossible.
Trust
Someone once asked me on a message board, ‘Why would I lend money interest-free?’ The borrower may not repay. Why take that risk? By trying to refute the idea, the poster unwittingly hit the jackpot on what usury-free finance is about. Indeed, the world is full of curious accidents. We lend interest-free to people we trust, and we may lend to family and friends, even when they are untrustworthy individuals living off our money. After all, they are family and friends. In a market, it won’t happen unless we trust the currency and the borrowers. Hence, ending usury is only possible in a high-trust environment. And investors must be in the market for other reasons than maximising their profits. Those who lend money to organic farms and invest in renewable energy have a different view of investing than vampire capitalists, who scam the government and rob grandparents of their retirement savings.
Trust is the foundation of our financial system. Credit means trust. And trust in the future is the foundation of the capitalist economy. Investors imagine that the future will be better so that their investments will be profitable or at least not loss-making. Credit, or financial capital, reflects this trust. Most of our money is credit, so its value depends on an imagined future. Some people argue that credit, banking, and central banking are fraudulent because they are fantasies. They may prefer something tangible, such as gold. Indeed, the capitalist economy, as well as civilisation in general, demonstrates the power of human imagination, and our faith in what we believe.
To have trust in the future, investors must believe that their investments are safe. The rule of law, political stability, the absence of graft, and sensible economic policies are fundamental to the economy’s effective functioning. As investments, such as factory investments, are long-term, the risk that a government will annul earlier commitments is a critical factor in investment decisions. Government actions, such as asset confiscation or taxation, can deter investors. Differences in tax regimes are equally damaging, as tax havens parasitise on productive economies that collect taxes to invest in their infrastructure and education.
Interest rates are the lowest in stable countries with low inflation, as trust translates into a risk premium on investments. The greater the risk, the more the future is discounted, the higher the interest rates, and the lower the standard of living, usually. Hence, Switzerland and Sweden have low interest rates, while Argentina and Mozambique have high interest rates. Interest rates in Europe are lower than in the United States. Apart from lower growth expectations, the Stability and Growth Pact, which limits government deficits, plays a role. And the government deficit as a percentage of tax income is a better indicator of the health of government finances than the deficit as a percentage of GDP. These are more sustainable in Europe. And so, trust also plays a role here.
Interest rates in Switzerland are currently at their lowest. In 2025, the key interest rate stands at zero. Swiss interest rates are so low because investors trust the Swiss currency. From 1990 until 2024, the government’s budget deficit averaged 0.45% of GDP. At the end of 2024, government debt was 20% of GDP. A general rule is that the lower the trust in the currency, the higher the interest rate. Venezuela has the highest interest rate at 60%, but with an inflation rate of 180%, investors are better off with a zero yield in Swiss francs. In a market, low interest rates signal trust. Hence, trust is a crucial prerequisite for ending usury. The currency needs to be as trustworthy as the Swiss franc, which, in turn, places a great demand on the society using it in terms of financial responsibility.
You can try to end usury the wrong way. In 2025, interest rates in Turkey rose above 40% to curb inflation following a failed monetary experiment. The assumption that interest charges cause inflation led Turkey’s leader to force the central bank to lower its interest rates. Inflation soared to 85% in 2022. In doing so, the Turkish leader defrauded creditors, thereby transgressing Islamic law. The relationship between interest and inflation exists, but it operates via credit. Credit expansion causes inflation, not interest itself. In a usury-based financial system with fiat currencies, raising interest rates curbs inflation by dampening demand for credit. That obscures the truth that interest is a cause of inflation. A better path to ending usury is to curb lending by setting a maximum interest rate and gradually lowering it to zero if market conditions allow.
With Natural Money, the central bank doesn’t set the interest rate or manage the money supply. The interest rate and the money supply emerge in the market for the lending and borrowing of money. The holding fee on the currency provides stimulus by making negative-interest lending attractive, thereby keeping money off the sidelines. At the same time, a maximum interest rate of zero imposes austerity, curtailing credit during booms or periods of high inflation. That will cool down the economy and dampen inflation. There could be deflation, and deflation could be permanent. The market for lending and borrowing is free in the sense that the central bank doesn’t manage interest rates and the money supply. However, the maximum interest rate of zero operates as a price control.
Interest rates emerge in the market for lending and borrowing. Negative interest rates require trust in the currency, the government and its policies, the financial system, and, ultimately, in the borrowers. It requires trust in the political economy and the future. In other words, all the world’s governments must be as reliable and capable as Switzerland’s, and the global economy must be on a sustainable footing. At the same time, market participants shouldn’t engage in scams. So far, business and ethics haven’t agreed very well. The ethic of the merchant is no ethic at all. The change requires a moral imperative. We shouldn’t harm other people or nature. Instead, we should see the consequences of our actions and change our ways. Only a new religion can make that happen.
The price of usury
Interest promotes wealth and income inequality. Most of us pay more in interest than we receive, either directly through loans and rents, or indirectly through the products we purchase. German research from the 1980s showed that the bottom 80% of the poorest people pay interest to the top 10% of the wealthiest people. Saving and investing can be beneficial, but as most economic activity is wasteful bullshit and suicidal also, we have to question that. Perhaps the Old Order Amish are better off than the working poor, who have social media, cars, and, of course, streaming services. And interest also works as a tax that the poor pay to the wealthy. The wealthiest individuals reinvest most of their interest income. That is what made them rich in the first place.
Interest promotes short-term thinking. With positive interest rates, money in the future is worth less than money now. It affects investment choices. With lower interest rates, long-term investments would become more attractive. Lower interest rates also enabled the Industrial Revolution because it required investments in buildings and machines that were only profitable at lower interest rates. Yet, the same applies to investments in a sustainable economy. For example, when interest rates are high, cutting down a forest today, selling the wood, and investing the proceeds may give higher financial returns than sustainable forest management.
Finally, usury is the primary cause of financial instability. Incomes fluctuate, while interest charges are fixed. It can bring borrowers into trouble. Worse yet, those who can’t afford it pay the highest interest rates, for example, in credit card debt and payday lending. Had they been unable to borrow, they would be better off. The freedom to borrow is the freedom to become a slave. Financial instability can lead to economic instability. Usury is a cause of financial crises, recessions and depressions. That is why governments and central banks manage the problem with fiscal and monetary policies. Yet, their actions create a false sense of security, allowing debt to continue to grow and ultimately leading to a financial apocalypse. Still, the road to the end of usury also goes through financial innovation and modern finance, which includes fiscal and monetary policies.
Fractional reserve banking
Innovations in financial markets have made them more efficient, enabling lower interest rates and increased lending, thereby spurring the Industrial Revolution. A crucial invention was fractional reserve banking. It turned bank deposits into money. There is always a demand for money. It is the most liquid asset. Economists call it the liquidity preference. Money commands power. You can use money to buy anything at any time. We may want to keep cash at hand for expected purchases, unexpected expenses, and investment opportunities.2 And so, we may not be willing to lend our money.
Fractional reserve banking enables banks to lend out money that depositors can withdraw. If you lend money to a fractional-reserve bank, you can withdraw it at any time, as if it were cash. Banks kept a fraction of deposits in cash reserves to meet withdrawals, knowing that only a small share of depositors would withdraw their money. That freed up funds for investments and helped to lower interest rates. A fractional-reserve bank creates money because a new loan automatically creates a new, equal-sized deposit. And that deposit is like any other deposit. You can use it to make a payment or withdraw cash. Fractional reserve banking eroded the commanding power of money, resulting in lower interest rates.
Fractional-reserve banks can fail when a large number of depositors withdraw their funds at once. The integrity of fractional-reserve money depended on the ability to exchange deposits for cash. That is where central banks come in. They can help banks in times of trouble by printing additional cash and lending it to them at interest. That safety net reduced the risk associated with bank deposits, allowing interest rates to drop even lower, which, in turn, promoted more lending and economic development.
If it sounds too good to be true, then it usually is. Lower interest rates have fuelled the economic boom since the Industrial Revolution and will eventually lead to a technological-ecological apocalypse. Critics of fractional-reserve banking and central banking further argue that lower interest rates encourage poor investment decisions and that the safety net provided by central banks creates moral hazard. If interest rates were to rise, these investments would become unprofitable, leading to bankruptcies and unemployment. And if central banks rescue banks in times of trouble, it will promote irresponsible lending.
There is overcrediting, and lower interest rates promote irresponsible lending by increasing profit margins for usurious lending. The way to end usurious lending is to set a maximum interest rate. More recently, critics have argued that central banks, through extraordinary measures such as quantitative easing, have suppressed interest rates. However, central banks believed that interest rates were too high. They couldn’t lower them because of a price control known as the zero lower bound, which distorts the market. By printing money, central banks aimed to generate inflation so that they could raise interest rates later.
Reserve requirements
Banks hold reserves, which are money issued by a central bank. Reserves include banknotes and coins, as well as balances held by banks at the central bank. The primary reason for holding reserves was to meet cash withdrawals from depositors or to make payments to other banks when depositors transfer money to another bank and the other bank demands payment in kind rather than an IOU. A reserve requirement is a liquidity requirement. A bank must have enough cash on hand to meet its short-term obligations. Two developments have profoundly affected the need for reserves:
Contrary to the past, depositors rarely withdraw their funds in cash, so the money remains within the banking system.
There are alternative sources of liquidity such as government debt. Government debt issued in the government’s currency is as safe as cash.
A government can guarantee repayments of debts issued in its own currency by printing more of that currency, with a so-called independent central bank as cover, which has become a core foundation of confidence in the current usury-based financial system. The central bank will not let the usury-based financial system fail, so it will print money to buy government debt, which reduces the supply of debt and increases the supply of currency by which to buy government debt, thereby lowering interest rates and allowing the government to borrow more, making new money available to pay interest.
These profound changes have made traditional reserve requirements of central bank currency largely redundant. Banks hardly need any cash in their vaults. If they pay another bank in kind, government debt is as good as central bank currency. Or a bank could borrow at the central bank or another bank and pledge government debt as collateral. The experts have concluded that reserve requirements in the form of central bank currency are now superfluous. High-quality assets such as government debt have become the actual reserve. And so, banking regulations today focus on solvency, or the ability to meet long-term obligations. Still, it would be a most serious oversight to ignore liquidity.
Globalisation, liberalisation, and derivatives
Advances in information technology and financial innovations have driven the globalisation of financial markets over the past few decades. In the 1980s and 1990s, governments liberalised financial markets and removed capital controls. Capital controls can lead to higher interest rates and higher costs of capital.3 Globalisation and liberalisation expanded the possibilities for borrowing and lending worldwide.4 The increased competition reduced the price of financial intermediation. As a result, the level of financial intermediation exploded, leading to the financialisation of economies and increased profits in finance.
Globalisation and liberalisation made financial markets more liquid. It became cheaper and easier to exchange financial instruments, such as bonds and stocks, as well as goods and services, for cash. This development is known as financialisation. Like fractional-reserve banking, financialisation eroded money’s commanding position as the most liquid asset, thereby diminishing the commanding position of money holders in demanding interest.
Globalisation and liberalisation also caused trouble. Money and capital could move more freely, making it easier for changing expectations to lead to financial instability. Central bank interventions neutralised a series of financial crises in the 1980s, 1990s and 2000s. Lower interest rates prompted investors to seek higher yields and take on more risk. However, trust and, therefore, liquidity can suddenly evaporate. Some countries used capital controls to counter financial instability while central banks provided liquidity.
Innovations in risk management and derivatives enabled the financial sector to further increase lending. These innovations spread risk, allowing the total amount of risk in the system to grow. Due to a lack of regulatory oversight, derivatives also enabled scammers to sell fraudulent mortgages, contributing to the 2008 financial crisis. Still, banks that professionally used derivatives to hedge their risks weathered the crisis better and had fewer loan write-offs.5
The notional value of outstanding derivatives can be mind-boggling. Their actual value is much lower. You can best compare them with insurance policies. The notional value of your fire insurance policy is typically based on the value of your home. The actual value is the premium you pay. That is, until your house burns down, and the actual value becomes the notional value. Insurers can handle that until many homes catch fire simultaneously.
The actual value of an interest rate derivative on a 3% ten-year bond with a notional value of €1,000,000 might change by €81,109 if the interest rate increases to 4%. As long as parties use derivatives to hedge risks, and counterparties, the ‘insurers’, can absorb the losses, the system will function. An equivalent to all houses catching fire simultaneously could be a sudden increase in interest rates. When the system is more stable, the need for these instruments decreases.
Wealth effect and bubbles
Lower interest rates increase the value of assets via discounting. In theory, the price of an asset is the net present value of its future revenues. Even though that is often not the case in practice, the theory explains why the prices of assets such as bonds, real estate, and stocks rise when interest rates decrease. In this sense, lower interest rates can promote wealth inequality, but only when we consider the net present value of assets. If future revenue streams don’t change, wealth inequality is merely a temporary side effect.
There was, however, another dynamic operating beneath the surface. Lower interest rates allow consumers to borrow more by taking out higher mortgages, thereby financing their unsustainable lifestyles. Critics called it a wealth effect promoted by an asset bubble. Lending propped up consumer spending when the incomes of many working-class people were lagging, and the wealth of the rich ‘trickled down’ via lower interest rates as they were running out of sensible investment options, giving them yet another avenue by which to squeeze the working class. In a system of usury, lower interest rates are of no help.
Financial sanity
Interest compounds to infinity. Three grammes of gold at 4% interest turn into an amount of gold weighing twelve million times as much as the Earth after 2020 years. Most of us aren’t long-term planners. We are busy fixing holes rather than solving underlying problems until things fall apart. Economists do this as well. John Maynard Keynes invented government borrowing as a fix for usury-induced debt problems. He once justified his short-term thinking with the world-famous quote, ‘In the long run, we are all dead.’ And this man was the founding father of modern economic policies.
More debt has now become the standard solution for debt problems. Today, most money comes into existence as a loan on which the borrower must pay interest. Every loan creates a deposit. The depositor automatically becomes the lender. If the interest rate is 5%, and €100 is circulating, then €105 must come back. So, where does the extra € 5 come from? Here are, once again, the options:
Depositors (on aggregate) spend some of their balances so borrowers (on aggregate) can pay interest from existing funds.
Some borrowers default and do not return (part of) the balance.
Borrowers (on aggregate) borrow the extra €5.
The government borrows the extra €5.
The central bank creates €5 out of thin air to cope with the shortfall.
Depositors can spend their balances, so interest payments do not necessarily cause a shortage of money. Still, in practice, they do, mainly because depositors, like Scrooge McDuck, find it difficult, emotionally or otherwise, to part with their money. New debt fills most of the holes left by depositors’ Scrooge McDuckism. That is why debt levels nearly always increase. Still, money doesn’t always reach the right places, which causes financial crises. A few defaults are acceptable, but too many can cascade into a financial crisis, triggering an economic downturn or even a depression.
The cost of allowing the financial system to fail is so great that it is not an option. The 2008 financial crisis could have meant the end of civilisation as we know it, had central banks not saved us from a financial apocalypse caused by usury. When no one else is borrowing, the government and the central bank must step in, either by borrowing or printing money outright, to introduce new money into circulation to repay existing debts with interest. In this way, debts continue to grow, and we have become the hostages of the usurers.
The end of the road
The road to the end of usury ran through financial innovations. They lowered interest rates. Today, the world is awash in debt, and interest payments strangle the global economy, to the point that future interest rates may be negative. That could either be the end of usury or, if usury remains, the end of the economy. The world economy may collapse, or we can have a graceful decline, promoted by the efficiency of a usury-free financial system. The efficiency of Natural Money can help us build a high-trust world economy founded on moral values.
In a simplified world, we rely more on family and community, and less on markets and states, so the economy will also become simpler. Natural Money eliminates risk from the financial system, so that, after its implementation, several modern financial instruments may become obsolete, joining fossil fuels and marketing strategies. Still, economies of scale apply to several essential products and services, including finance. Negative interest rates require risk management that only scale can provide.
Latest revision: 4 November 2026
Featured image: Loan shark picture circulating online, origin unknown.
1. Capital in the Twenty-First Century. Thomas Piketty (2013). Belknap Press. 2. Keynes, John Maynard (1936). General Theory of Employment, Money and Interest. Palgrave Macmillan. 3. Edwards, Sebastian (1999). How Effective are Capital Controls? Anderson Graduate School of Management, University of California. 4. Issing, Otmar (2000). The globalisation of financial markets. European Central Bank. 5. Norden, Lars, Silva Buston, Consuelo, Wolf Wagner (2014). Financial innovation and bank behaviour: Evidence from credit markets. Tilburg University.
Here comes another joke about economists. Suppose you just have found a tenner on the street. You are very excited about your windfall and tell the next person you meet about your find. You say, ‘I just found a tenner on the street.’ Now, this individual happens to be an economist. And he replies, ‘That is impossible. If there really was a tenner on the street, someone would have picked it up already.’
Economists also say, ‘There is no such thing as a free lunch.’ Some people get a free lunch, but someone else has to pay for it. If you find a tenner, someone else paid for it. If there is money for free, people will take it and let others pay for it. Economists call it arbitrage. It is also what trade is about. Traders try to make money by finding money for free, but in doing so, they work and take risks.
Economics assumes humans are rational in economic matters and do not leave tenners on the street. We make the best of our money by choosing the right products. And we make as much as we can with our abilities. If we get cash for free, many would not work or only do jobs they like to do. And even though we often are not rational, it explains much of our behaviour, most notably what happens in markets. If there is a tenner on the street, it will not be there for long.
If gold costs € 50 per gramme in France and € 40 in Germany, traders can make money by buying gold in Germany and selling it in France. The demand for gold in Germany will rise, as will the supply in France. The law of supply and demand says that the price goes up when demand increases and goes down when supply increases, so the price in Germany and France will be the same.
Economists call it arbitrage. Smuggling comes from the same principle. Cigarettes are more expensive in the United Kingdom than on the European continent. You can make money smuggling cigarettes into the United Kingdom and selling them there illegally. The price difference promotes smuggling. The difference between arbitrage and smuggling is that arbitrage is legal.
Markets without morals
Even though most individuals have moral values, markets do not have them. There are always people willing to market a harmful product. Their excuse often is that if they do not, someone else will. Laws can illicit smuggling and black markets. It helps if laws and enforcement are the same everywhere. Still, supply always equals demand at a specific price. So, if you outlaw harmful substances or practices, say alcohol, prostitution, cocaine, gambling, or cigarettes, you promote crime and violence because criminals make more money.
And so, the War on Drugs is a failure, like the prohibition in the United States in the 1920s. If selling cocaine is legal, the price difference between Colombia and the United States would be close to the production and transport costs. In that case, a gramme of cocaine might cost $ 5 in Colombia and $ 6 in the United States. But if it is illegal, and governments enforce the law, a gramme of cocaine might cost $ 10 n Colombia and $ 100 in the United States, and criminals make lots of money in the trade.
As crime-related violence engulfs more and more countries, gangs of criminals undermine governments and societies by giving poor people an income, bribing officials and hiring hitmen to eliminate those who stand in their way. Seeing it as an economic problem might help to find solutions, for instance, undermining the criminal business model by letting governments supply harmful substances and gambling and regulating prostitution. If governments keep repressing the drug trade, they make the criminal enterprise unprofitable by bringing their cost above the price for which governments sell.
It brings moral dilemmas, but unlike criminals, governments do not do marketing, for instance, by giving drugs to children to turn them into addicts. Governments have no profit motive, which allows governments to help drug addicts and give them treatments. But this does not stop the fentanyl crisis in the United States. This drug is too cheap and too deadly. Only unconventional measures like taking all the addicts off the streets and locking them up might end the suffering. To solve this issue, we might need to be as committed as the Taliban and accept the human cost. The human cost will be higher if we are lax. If an addict dies because of these measures, this person would have died anyway, and the gain is in the people we save.
Trust but verify
Similar issues arise when governments tax, punish criminals, give subsidies or provide social benefits. If that elicits the desired behaviour, that is good, but that does not always happen. Businesses shift their profits to tax havens. Wealthy individuals do the same with their assets. If there are social benefits, people who do not like to work or dislike their job try to get on the dole. Many people need those benefits, but fraud undermines their legitimacy.
Reasonable people are willing to pay taxes for people who need help but not for fraudsters. Tax and welfare fraud may get understated or overstated for political reasons. If you can commit fraud and gain financially, some will do it. And if they get away with it, more will do it. That undermines trust. Regulations need enforcement. For instance, not enforcing building regulations allows contractors to make money using inferior materials. And that happens with devastating consequences.
When private contractors perform public tasks, and the government pays for them, there is an opportunity for fraud. In the Netherlands, the government decentralised several forms of social work to the municipalities. Since then, criminals and fraudsters have set up businesses in those areas. The choice is either for governments to do these tasks themselves or to work with reliable suppliers by vetting them, perhaps even licencing them, and monitoring their performance.
Trade as finding tenners
Trade is like looking for tenners on the street and keeping them, even if you know the previous owner. You might call it pickpocketing. The difference is not always clear. Hermes, the Greek god who was the protector of the merchants, was also the refuge of the thieves. Popular culture views traders with suspicion. Value is subjective. If you bought an item for € 50 but could have bought it elsewhere for € 40, did the seller dupe you, was the item worth € 50, or were you stupid?
And we cannot do without trade. Few people have the time to go to all the producers for the things they need, nor have these producers the time to handle each individual that needs their product. If you had looked around, you might have found the same item for sale for € 40, but perhaps, you were too busy and happy to get the item instantly without looking around. Trade performs the following functions:
Goods are made in one place and used somewhere else. Trade bridges distance.
Goods are produced first and consumed later. Trade bridges time.
Goods usually are made in large batches and used in smaller ones. Trade matches volumes.
Crucial to trade is information. A trader must know what is on offer for what price and where, and for what price it might sell when and where. Gathering that information costs time and effort. If you trade potatoes, you buy them in large quantities from farmers during the harvest and sell them in smaller quantities to greengrocers throughout the year. You must offer an attractive price to the farmers and the greengrocers. Otherwise, they will go elsewhere. And your business must make a profit. Otherwise, you might as well have stayed in bed to watch television.
Financial markets
A tenner dwells more likely on streets where others do not look. Wall Street firms hire the brightest minds on the planet to find these places. For instance, Apple stock may be for sale for € 150 in Australia while it is doing € 151 in Germany. If you want to pick up that euro, you must be there and act quicker than everyone else. Wall Street firms thus invest in the fastest computers and networks.
So if a tenner falls out of your pocket on the stock market, Wall Street firms have already picked it up before it hits the street. They may soon apply artificial intelligence to look inside your pocket and fetch the tenner before it falls. So if you are willing to sell your stock for € 150 and someone else is willing to pay € 151, Wall Street banks may snatch the securities you offer for € 150 and sell it to the other for € 151.
If the interest rate in one country is lower than in another, you can profit by borrowing money in the first country and lending it out in the other. It can be attractive to borrow yen at 1% to buy dollars to lend them at 5% and pocket the difference. Economists call this a carry trade. You might expect that, like the price of gold, interest rates would converge because the yen interest rate would rise because of the borrowing in yen, while the dollar interest rate would fall because of the lending in dollars.
That did not happen. The central bank sets the interest rate and can create money. The Japanese central bank kept lending yen at 1% and buying dollars because the Japanese government did not like the yen to rise. That could hurt their exports. If the US central bank held the interest rate at 5%, and the Japanese central bank prevented the yen from rising, that meant lots of free money for banks. The Japanese paid for it. They could have bought more with their money if it had been worth more.
One of the most troubling issues with trade, markets and capitalism, is that value is subjective and often depends on irrational emotions. The market value of an empty Gucci bag is higher than that of a shopping bag filled with potatoes. And even though we cannot establish objective value, we need food more than designer bags. The appreciation of subjective value is what makes the current economic system suicidal. A happy shopper today can be a dead one tomorrow.
Lately, I found a tenner on the street. Economists can be wrong. Well, indeed.
Latest revision: 19 August 2023
Featured image: A tenner on the street. Free Shutterstock image from Blackday.
A dictionary defines currency as the system of money used in a particular country. You find both the words ‘general’ and ‘particular’ in this general definition of this particular term. A currency belongs to a specific country. Financial transactions within that country are in that currency. If you go to Sweden to do some shopping, be sure you have some Swedish crowns on you. The economist’s definition of currency is government money. It includes coins, banknotes, and central bank deposits, but not commercial bank deposits.
Under the gold standard, each currency was backed by a fixed amount of gold, and national central banks held gold in their vaults. You could exchange banknotes for the gold they represented. That was the basis of the currency’s value. And so, the underlying currency was not the national currency, but the international currency, gold. Under the gold standard, the world had a single currency, gold. You could exchange bank deposits for currency, thus gold.
Today, we have national fiat currencies, and bank deposits are also money. But what gives fiat currencies their value? It is the national economies backing them, because of the equation known as the Quantity Theory of Money, which says that Money Stock (M) * Velocity (V) = Price (P) * Quantity (Q), so Money Stock (M) depends on Velocity (V), Price (P) and Quantity (Q), and the value of a single unit, such as the Swedish crown, is M / units in circulation. The money stock includes bank deposits.
Honest money
Proponents of the gold standard argue that gold is honest money and that fiat money is a fraud. Yet, the scam is usury, so that charging interest on gold is a fraud. There isn’t enough gold to repay all debts, and interest compounds that problem. In that sense, fiat is honest money because it merely promises to pay in fiat, which a government can honour. Everyone knows that this money will be worth less in the future, and no one knows by how much, which everyone knows. Usury turns money into a Ponzi scheme. And so, only usury-free fiat money is honest money.
Usury may seem victimless, but it corrupts everything, bringing down nations and civilisations. It is the gravest crime against humanity. As a result, honest people become increasingly rare. A society or a civilisation collapses due to scams and greed. Crimes seem victimless when you are unaware of the consequences, don’t care about them, or even deny them. But everything you do affects people, animals, plants, and future generations. Today’s economy is an orgy of planetary destruction, transforming energy and resources into waste and pollution, driven by the pursuit of profit.
Interest is the price of distrust, not only in the currency, but also in debtors. Usury-free money requires honest debtors. Planning not to repay your debts, or hiding the risk that you might not be able to, is a most serious offence, as harmful as demanding interest. Many financial frauds are comparable to usury. These crimes often seem victimless, but they cause distrust. They are worse than murder, because distrust causes interest rates to rise, and usury is a destroyer of civilisations.
A usury-free financial system requires a political economy with high ethical standards. The moral foundation of our civilisation is the ethics of the merchant, which is no ethics at all. And as long as there is no permanent world peace, nation-states will do anything to finance their war effort, such as offering interest on loans. Humans are a self-destructive species that may only do the right thing when inspired by fairy tales. And so, an honest political economy and permanent world peace will remain unthinkable unless an inconceivable event, such as the emergence of a new world religion, were to occur.
Import and export
International trade affects a currency’s value. When a country exports more than it imports, demand for its currency exceeds supply, driving its currency higher against other currencies. That makes foreign products more affordable than domestic products, allowing exports and imports to balance. Conversely, the opposite happens if a country imports more than it exports. After World War II, the German mark became a strong currency because Germany was exporting more than it imported.
That isn’t always the case. Countries lend and borrow in international markets. The central bank of Japan printed yen to buy US dollars, thereby increasing the supply of yen and decreasing the supply of US dollars by lending those yen to traders. As a result, Japan continued to export more than it imported for decades. The Japanese central bank set interest rates at a low level. Traders borrowed yen to buy US Treasuries with higher interest rates, pocketing the difference, subsidised by Japan’s willingness to depress the value of their currency. Without usury, that might have been impossible.
Likewise, countries that import more than they export can borrow foreign currency to cover their import costs. These countries can run into trouble as they borrow a currency they can’t print. They can borrow because, in a usury-based financial system with national currencies, interest is a reward for the risk of default. Had borrowing at interest been impossible, deficit nations would have to balance imports and exports. Instead, they go into debt and export more than they import to pay the interest on their debts.
The primary reasons for these persistent imbalances are usury and the existence of independent nations with national currencies and economic policies. The alternative would be to let these imbalances correct themselves, which would require the free movement of people around the world so they can settle where the opportunities are, or government policies to support weaker regions, such as ordering corporations to employ people in these areas. That becomes possible with a single world government and currency.
Reserve currency
Reserve currencies facilitate international trade. Since World War II, the US dollar has been the most widely used reserve currency. The arrangement allowed the United States to enjoy a higher standard of living and have a large military paid for by foreign nations. In the 1960s, the French Minister of Finance, Valéry Giscard d’Estaing, referred to it as the US’s ‘exorbitant privilege’. The US dollar and Wall Street have been the pillars upon which the US financial empire rested. Previously, Great Britain had a similar privilege, as the City of London was the world’s financial centre. Financial power was also the basis of the British Empire. Great Britain also ran into deficits, as having the reserve currency is disadvantageous to domestic industries.
Economists call the ailment the Dutch disease. As the Dutch had large natural gas reserves, demand for the currency rose, causing it to appreciate and undercutting the competitiveness of Dutch industries. Reserve currency status generates similar demand for the currency. It gave exporting industries in foreign nations a competitive advantage. By buying US dollars for their currency reserves, competitors of the United States were able to suppress the value of their own currencies and sell their products at a lower price, leading to the deindustrialisation of the US. If you own a money printing press, printing money is also an easy way out. The US dollar’s reserve-currency status harmed US exports and enabled other countries, such as China and Japan, to build their industries.
The US Dollar’s reserve status also made the Fed responsible for the international financial system. The Fed had to rescue foreign banks during the 2008 financial crisis. Americans felt they ended up paying to prop up foreign banks. That is incorrect, as the holders of US dollar-denominated debts paid for it, not indebted Americans. And had the Fed not acted and the global economy collapsed, they would have discovered that the rest of the world had been funding their American Dream, even as the American Dream gradually became out of reach for more and more Americans.
Due to usury, debtor nations face a shortage of US dollars, making them hostages to the US dollar-based usury financial system. Meanwhile, creditor nations, lured by interest payments, stored their wealth in US dollar-denominated debt. That has been the basis of the US empire. It was a deliberate choice by US policymakers to financialise the US economy under the guise of Reaganomics and neoliberalism, and to generate profits in the bullshit economy to attract investment capital to support the reserve-currency status of the US dollar, as competing in the real economy had become more challenging.
Belief in the US dollar’s value and the promise of financial profits fueled the neoliberal economic boom. The imbalances in the system accelerated the conversion of energy and resources into waste and pollution, a process that economists refer to as wealth creation. By their excessive consumption, Americans generated ‘wealth’ by exporting US dollars. It is indeed one of the most bizarre side-effects of this setup. The US dollar’s reserve-currency status meant that Americans could live beyond their means, with the costs paid for by austerity in the rest of the world. In other words, Americans could spend their way into prosperity while other countries had to export their way into it.
Government debt and liquidity
A government doesn’t need to borrow if it can print currency. Such a scheme doesn’t instil confidence in currencies. For that reason, central banks became independent of governments to promote trust in their currencies, as creditors don’t trust politicians. Instead of printing currency outright, the usurers made governments borrow and pay interest. Still, when a government borrows in its own currency, it can always repay the loan, with interest if needed, by printing money. And short-term debt carries little interest-rate risk. That makes short-term government debt as safe as the currency itself. Hence, banks could use it as a liquidity reserve in the financial system.
It has become unthinkable that a sovereign government would go bankrupt, so banks use government debt as collateral or investment, thereby promoting liquidity in the financial system and generating profits for the usurers who operate it. When a bank lacks cash, it can sell government bonds or pledge them as collateral for a loan from another bank. Government debt is a pillar upon which trust in the financial system rests. US banks hold more in government debt than in commercial loans. Therefore, when the government goes bankrupt, the financial system collapses with it.
With fiat currencies, the currency is as good as the political economy backing it. Ideally, a stable society, industrious people, and a prudent, honest government help a fiat currency maintain its value. In reality, tax evasion also plays a role. High-net-worth individuals take their wealth from the societies that helped them generate it because they don’t want to pay for the public education and infrastructure that made their wealth possible, and transfer it to tax havens that parasitise on productive economies. A single tax regime for the entire world can remedy that issue.
Under a gold standard, there was no guarantee that a government could repay its debts in gold. And so, only gold itself was a safe reserve, which constrained liquidity in the financial system. Fiat currencies in the usury financial system are not a store of value, but they usually suffice as a medium of exchange. With inflation rates of 10%, lending and borrowing can continue at higher interest rates. Therefore, under normal circumstances, interest-bearing investments in a fiat currency can retain their value.
Gold money requires interest, as you can store gold without loss. Therefore, gold can’t be money in a usury-free financial system. Other forms of backing, such as food reserves, are also problematic, as they create monetary demand for these items, thereby making them more expensive. By owning gold, you can protect yourself against the failures of the political economies backing the world’s fiat currencies. Precious metals, however, offer little protection against societal collapse or revolution. Gangs or revolutionaries may take your possessions and murder you, so you are as safe as the society you live in.
Single currency
The member states of the eurozone have embarked on a curious monetary experiment. What is novel, and also unusual, about the single currency is that the member states are sovereign, yet they share a single fiat currency. Eurozone member states can still issue debt, despite having agreed to limit their debt and deficits under the Stability and Growth Pact. The problems that arose demonstrate the relationship between sovereign governments and the currencies they issue. In a broader historical context, the euro is a prelude to a single world currency, and the euro experiment highlights the problems that come with it:
Under the gold standard, there was a single currency, gold.
After the gold standard had ended, states began issuing fiat currencies.
Under the euro standard, the Eurozone has a single fiat currency, the euro.
A state’s prerogative to issue currency confers a degree of independence in making political choices that affect the economy. If France still had the franc and decided to lower the retirement age, it could finance the entitlements by printing francs. The franc would have lost value, and prices in France would have increased, with the French paying the cost. The Quantity Theory of Money makes it clear. Money printing raises M, and lowering the retirement age lowers Q, so P increases. To compensate for the loss in purchasing power, lenders will demand higher interest rates.
The French socialists would then blame higher prices on price-gouging corporations and higher interest rates on usurious bankers, and the French would go on strike to demand lower prices and interest rates. Now that France has entered the Eurozone, the consequences of its political and economic choices are felt across the entire Eurozone, and going into debt or printing currency to lower the retirement age has become a scam at the expense of other Eurozone member states.
In a fiat currency regime, government debt is ‘safe’, meaning that the government borrows in its own currency and promises to repay both the principal and interest in that same currency. In the past, France could borrow French francs in the market and repay them with interest, as it could print francs if needed. France could always repay its debts in French francs. Banks hold government debt as a liquidity reserve based on its presumed safety. Government debt is a pillar upon which trust in the financial system rests. So, to make the eurozone work, its member states must underwrite each other’s debts.
The underwriting was not part of the initial eurozone setup. That problem came to light during the eurozone crisis that escalated in 2012. ECB President Mario Draghi decided to do ‘whatever it takes’ to save the euro. Investors were losing trust in the debts of several eurozone countries. The recession following the 2008 financial crisis had deteriorated their finances. Due to the higher interest rates they had to pay on their debts, these countries were heading toward default, which would bring down the euro. It forced the ECB to underwrite these debts by buying them until their interest rates dropped.
The underlying cause of the crisis is usury. High interest rates pushed these countries toward default, while lower interest rates made their debts safe again. The fiscal irresponsibility, insofar as there was one, also relates to usury. Had these governments not been allowed to borrow at interest rates above zero, their finances would have been in excellent shape. And finally, the crisis began with subprime lending in the United States, which wouldn’t have occurred without usury, since there would have been no reward for the risk of default. And so, a global fiat currency can only work when it is usury-free.
International Currency Unit
The euro experiment has shown that a single world currency, or International Currency Unit (ICU), doesn’t require a one-world government if all the world’s governments yield their prerogative to issue the currency, as the Eurozone members have done, and accept that they can’t issue debt if no lenders are willing to lend at a negative interest rate. In a Natural Money usury-free financial system based on a currency with a holding fee, the ICU serves only as a unit of account, as no one wants to pay the 10-12% holding fee. Government debt, rather than currency, will be the liquidity in the financial system.
All the world’s governments can issue their debt in the ICU, provided lenders are willing to lend them at zero or negative interest rates. Hence, a global usury-free financial system founded on the International Currency Unit (ICU) can be politically neutral. It doesn’t require reserve currencies that can benefit specific nations or harm their industries. The ban on usury ensures the system’s integrity, as there is no reward for taking on risk, while debt issuance depends on a lender’s willingness to lend without interest. That includes government debt. Enforcement still requires a higher authority to oversee nation-states.
Governments can issue debt only to the extent that lenders are willing to lend them funds at a negative or zero interest rate. When a government can’t borrow, it must either raise taxes or reduce spending. With Natural Money, government debt becomes a separate currency that also backs banknotes and coins. If nation-states continue to exist, these will be the national currencies. The same applies to a world government. The world government needs a tax base and may issue ICU-denominated debt that may become the Global Reserve Currency (GRC).
Private vouchers and crypto vouchers
Private vouchers and crypto vouchers are not currencies because no government has issued them, and there is no law requiring us to accept them for payment. They are comparable to supermarket chains’ value stamps and value tokens in computer games. If your employer proposes to pay you in Dogecoin or bottles of wine, you can refuse and request payment in the national currency. It is your prerogative by law. But you can’t refuse the national currency. The government doesn’t accept crypto vouchers for tax payments. The proponents of crypto vouchers promise that they provide an alternative payment system independent of governments and banks. For criminals, they do.
Proponents of cryptocurrencies believe that the private sector does a much better job of scamming the public with cryptocurrencies than the government does. You can legally invest in crypto, just as you can in stock market scams. Those who hold crypto vouchers see them as a hedge against state-issued currencies, since crime will persist long after governments have collapsed. They play a role similar to that of precious metals, but crypto vouchers don’t offer as much protection as gold, since they depend on a technological infrastructure that can fail. Gold has kept its value throughout the ages, even though it is a problematic type of money, as it makes usury inevitable.
National currencies hand nation-states a degree of political and economic autonomy. Governments have usurped the prerogative to issue currency and, through legal-tender laws, to determine what constitutes money. A contentious issue is that governments permit private banks to exploit their national money systems for private gain through usury, thereby undermining the currency. The crypto vouchers don’t have that issue, as lending and borrowing can’t increase their supply, so their sales teams market them as a store of value. But they aren’t gold, so the question is: who will end up empty-handed?
Latest revision: 3 November 2026
Featured image: Amazon Blue Front Parrot. Beverly Lussier (2004). Wikimedia Commons. Public Domain.