
The problem with cash
Cash is cumbersome for both businesses and banks, so they increasingly opt for digital payments. It reduces costs. People also choose digital payments more often, while authorities have sought to limit cash use because it has long been the preferred method of payment for criminals and tax evaders. In the European Union, many people use cash for smaller transactions. A more recent development is digital cash. Like banknotes, digital cash is central bank money, thus currency, not bank debt. If your bank goes bankrupt, you may lose your deposit, but you will not lose your digital cash.
Cash, as it exists today, including digital cash, bars the road towards negative interest rates. When interest rates fall below zero, cash can become an attractive investment because its interest rate is zero. In Switzerland, where interest rates had been the most negative at -0.75%, 1,000 franc banknotes and safe deposit boxes had been in short supply. As long as cash yields zero, interest rates below -1% remain impossible. And with digital cash, negative interest rates become impossible. Depositors will then withdraw their money from the bank and stash it in digital wallets.
That can jeopardise the financial system. When depositors take their money from the bank, the bank can run into trouble when interest rates fall below zero. A 12% per year holding fee on central bank money, which includes cash, can make it attractive to lend at negative interest rates, such as -2%, since you don’t pay the holding fee on the funds you lend. Bank deposits are money lent to banks, thus loaned funds. If cash has a lower interest rate than bank deposits, you may keep your money in a bank account. Still, a 12% annual penalty is steeper than necessary to keep the economy operational.
Cash as a loan to the government
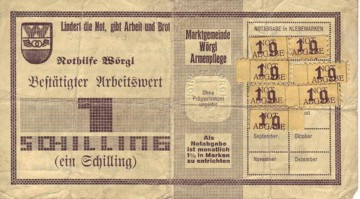
In Wörgl, the townspeople bought stamps and glued them to the banknotes to keep them valid. It would be more practical if we didn’t have to do such awkward things that might involve licking. A holding fee of 12% per year is also forbidding. The charge doesn’t need to be that low to prevent people from withdrawing their money from the bank and putting it in a safe deposit box. If the interest rate on cash were slightly lower than the interest rate on bank accounts, that would be enough to stop people from hoarding banknotes.
When cash is a loan to the government, the interest rate on cash could be the same as that on short-term loans to the government. That rate would be better than the holding fee and could be as low as -3%. There can be an exchange rate between cash and central bank money. The value of cash would gradually decrease by 3% per year, and you don’t have to glue stamps on banknotes to keep them valid. The situation resembles 3% inflation, but it is a negative interest rate.
That difference is crucial because currencies with negative interest rates may not require government or central bank management. They provide financial stability themselves. There is no shortage of money due to interest charges, so there is no permanent need to expand debt to sustain the usury scheme, which requires government and central bank management. With negative interest rates, the money supply can be stable or even shrink without adverse consequences for the financial system or the economy. The future role of the central bank may centre on managing the payment system once monetary policy has become obsolete.
Human psychology
Negative interest rates visibly reduce the currency balance in your account, while inflation operates more stealthily, by robbing you while you believe you get more. Wage changes are more noticeable than price changes, as some prices decrease while others increase. Even when negative interest rates and deflation are a better deal, and even if we all know it, we might not opt for them. The phenomenon is known as the money illusion. We resist a reduction in monetary units, even if it would make us better off.
It also affects how we look at negative interest rates. When interest rates are negative, money disappears, so inflation is likely to be lower, and prices may even decrease. That could be a better deal for depositors if their real return were higher, but most people dislike seeing their account balance decrease due to a negative interest rate. They might get edgy about their money vanishing into thin air. Negative interest rates sparked outrage among some Belgian depositors, who demanded a ban on these rates.
We prefer the illusion of a small gain that amounts to a loss in reality to the illusion of a similar loss that is, in fact, a better deal. It is not rational, but human psychology is the way it is. We are emotional beings that can think rather than thinking creatures with emotions. There is a fix: hiding negative interest rates and making them appear as inflation. To explain how, we can look at the characteristics of Natural Money:
- The administrative currency carries a holding fee of approximately 12% per year. If you own this money, then €1.00 turns into €0.88 after a year. It can make lending at negative interest rates attractive.
- Interest rates on bank accounts might be around -2% per year. Depositors don’t pay the holding fee, but they do pay the interest rate the bank offers.
- Cash is a short-term loan to the government and carries the interest rate of short-term government loans, which might be -3%.
- The administrative currency and cash become separate currencies. Cash gradually loses value relative to the administrative currency.
Making cash the money in people’s minds
When bank account statements are in cash currency rather than administrative currency, we don’t notice that the interest rate is below zero. The interest rate on short-term government loans is one of the lowest. Banks must be able to offer at least this interest rate so we won’t see our balance shrink due to negative interest. And if shops express their prices in the cash currency, it will become the currency in our minds.
If the interest rate on cash is -3%, its value decreases by 3% per year in terms of the administrative currency. If a bank offers an interest rate of -2% and settles the account in cash, the interest on the bank account appears to be +1%. And if the deflation rate is 1%, prices go down by 1%. Meanwhile, the value of cash decreases by 3% in the administrative currency, so prices in the cash currency increase by 2%. And so, we experience 2% inflation.
You can see it as a deception to prevent people from deceiving themselves. People get aggravated by negative interest rates, but largely ignore inflation. They also fall for the illusion of getting more when interest rates are positive. When the interest rate on bank accounts is 1% and inflation is 3%, you would lose 2% in purchasing power per year by holding a balance in a bank account. A 1% loss is a better deal for depositors. Natural Money can improve the economy, allowing real interest rates to be higher.
Critics might argue that we could be fooled by this scheme, just like inflation fooled us before. We won’t notice the negative interest rate, just like we did with inflation. Separating cash from the administrative currency and expressing prices and the value of bank accounts in cash currency can clear the psychological barrier that stands in the way of the public adopting negative interest rates.
The administrative currency remains the accounting unit in the financial system for bank accounts, debt, and interest, as well as the prices of financial assets, such as stocks and bonds. A similar situation existed in Europe between 1999 and 2002. After introducing the digital euro, cash continued to be the national currency. With Natural Money, the maximum interest rate of zero applies to the administrative currency and not to the cash currency, so interest rates in the cash currency may be above zero.
Latest revision: 3 November 2026
Featured image: Wörgl bank note with stamps. Public Domain.


I wonder how much negative interest rates work in terms of stimulating economic activity. It seems to me that ultra-low interest rates can exist for a long time without producing the (apparently) desired income (sustainable and inclusive growth). This can be partly due to the human psychology you refer to, but it may be that a change to job-creating fiscal policy is required as a stimulus. On the other hand, the environmental crisis is now so bad that it could be time to abandon growth as a target.
LikeLiked by 2 people
Negative interest rates are the result of ‘capital surplus’, meaning that more stuff is produced than people can or are willing to buy.
Negative interest rates can provide stimulus if they are low enough like -3% or -5%. Current rates like -0.5% probably do very little.
Lower interest rates are possible considering market conditions. But how low the market interest rates are we can only find out by implementing a fee on central bank currency.
Under those conditions governments might borrow money at negative rates in order to provide addional funding for an income guarantee, which is explained here:
https://theplanforthefuture.org/2020/07/04/free-money-for-everyone/
LikeLiked by 1 person