The Gospel of John remarkably differs from the other Gospels in several ways. Among those differences is that Matthew and Luke say that Jesus’ mother was a virgin. Mark doesn’t mention it, while John claims that Jesus was with God in the beginning, and not only that, but also that in him was life, and that life was the light of all humankind. It refers to Genesis, where, in the beginning, God created the heavens and the earth. But that earth was formless, empty, and covered by darkness, so God said, ‘Let there be light,’ and there was light. That is noteworthy, to say the least. John remains cryptic and goes on to add a few more transcendental musings of the Platonic kind (John 1:9-13),
The true light that gives light to everyone was coming into the world. He was in the world, and though the world was made through him, the world did not recognise him. He came to that which was his own, but his own did not receive him. Yet to all who did receive him, to those who believed in his name, he gave the right to become children of God- children born not of natural descent, nor of human decision or a husband’s will, but born of God.
Christians are born of God. Jesus gave us the right to become children of God. It could be why Jesus said he was the life, apart from being the way and the truth (John 14:6). John seemingly contradicts himself by calling Jesus God’s only begotten Son (John 3:16), since begetting refers to the male role in procreation. The idea of a begotten son, an emanation of the transcendent God within the physical cosmos, was widespread among religious philosophers of the time. John borrowed the idea to fix his theological problem by making the manner in which Jesus was God’s Son transcendental rather than physical. If you do that, it doesn’t matter whether God is a man or a woman or the particulars about how God spawned Jesus. It is all in the magic realm.
Men cannot give birth, so if God birthed Jesus, God could be a Mother, and the transcendental begotten formula could be how John masked it. Now, John doesn’t say Jesus was Adam, who begot humanity by being the husband of Eve, who was God. To avoid the unplatonic phrasing of God having sex with Jesus, he reformulated it, again in a transcendental manner, as Jesus giving us the right to become children of God. The same author, who was not the Apostle John, clarifies in his first epistle what it means that Jesus is the Son of God (1 John 5:1),
Everyone who believes that Jesus is the Christ is born of God, and everyone who loves the Father loves His child as well.
How come that God the ‘Father’ gave birth to Jesus? Somehow, everyone ignores the glaringly obvious, and no one asks that question. When there has always been a giant, stinky rat decomposing in the kitchen, you stop noticing its smell. The phrase born of God occurs several times in this letter (1 John 2:29, 3:9, 4:7, 5:1, 5:4, 5:18). Today, Christians assume that the phrase ‘born of God’ has only a spiritual meaning, as Jesus likened entering the kingdom of God to being born again when answering a question posed by a Pharisee named Nicodemus (John 3:3-6),
Jesus replied, ‘Very truly I tell you, no one can see the kingdom of God unless they are born again.’ ‘How can someone be born when they are old?’ Nicodemus asked. ‘Surely they cannot enter a second time into their mother’s womb to be born!’ Jesus answered, ‘Very truly I tell you, no one can enter the kingdom of God unless they are born of water and the Spirit. Flesh gives birth to flesh, but the Spirit gives birth to spirit.’
Nicodemus mentions the womb, so the phrase ‘born of God’ implies that God is a Mother. That raises a question. If the early church leaders went to such great lengths to remove the evidence of God being a Mother, how could they have overlooked the phrase ‘born of God’? The correct answer is that they didn’t. The language of the Gospels is Greek. Greek culture dominated the ancient Eastern Mediterranean, where Christianity spread. Learned Jews like Paul were well acquainted with Greek thought. Greek thought and mythology helped the early church fathers reconstruct their religion after changing God’s gender.
In Greek mythology, Athena, the goddess of wisdom, was born from the head of the male deity Zeus. As the tale went, Zeus’ head opened to let Athena out and closed again. In this way, a male deity could give birth. And that was very convenient. When the church fathers altered God’s gender, they may have initially thought of the Zeus-and-Athena analogy, so Jesus was born of the Father. There is another enlightening piece of evidence, the Odes of Solomon. These are first-century Christian writings, thus of the earliest days of Christianity. Ode 19 (here is that number again) comes with the following lines,
A cup of milk was offered to me: and I drank it in the sweetness of the delight of the Lord. The Son is the cup, and He who was milked is the Father. And the Holy Spirit milked Him: because His breasts were full, and it was necessary for Him that His milk should be sufficiently released. And the Holy Spirit opened His bosom and mingled the milk from the two breasts of the Father, and gave the mixture to the world without their knowledge.1
No other ancient Christian text explicitly mentions gender-related attributes of God. Here, God has female physical characteristics despite being called Father. And because it is an ancient text dating from Christianity’s first century, the Father was first a Mother.
Latest revision: 15 September 2026
Featured image: Bible: Only God Knows What Jesus Really Said. Loesje.org.
1. The Lost Bible: Forgotten Scriptures Revealed. J.R. Porter (2001).
Autistic individuals have a social handicap. Yet, it comes with a benefit. We all can think logically, but if you’re autistic, you are less prone to group pressure. Humans are social animals who cooperate by sharing their fictions, such as money, laws, and nation-states, as well as religions and ideologies. We share beliefs to cooperate, so groups pressure their members into accepting them. Most people accept false beliefs or do stupid things to get accepted by the group. That ailment doesn’t plague autistic persons. That sets them apart. Autism is also a failure of intuition, so that autistic people can be inept and poorly adapted to their environments. They might make up for that by analysing the situation. Sometimes, it yields better results because intuition can fail us.
Most of our thinking happens intuitively. Intuition works fast. You can call it fast thinking.1 When our intuition fails us, which may happen when the situation changes, our reason steps in. You can call it slow thinking. You consider and evaluate the options. If intuition suffices, that is a waste of time and energy. Evolution made this happen. Wasting energy reduces your chances of survival, as you must find a new meal sooner, and that meal may not be forthcoming. You could die of starvation because of thinking too much, because your brain consumes a lot of energy. And species that considered all the possibilities when a hungry pride of predators was coming their way didn’t survive.
Great chess players don’t consider all the options. Their intuition presents a few options that their reason consciously evaluates. They thereby ignore billions of options, most of which are not worth considering. That’s what makes them such great chess players. Training and experience help improve our intuition, so intuition is not entirely innate. Our brains have limited processing capabilities. Clogging a brain with countless useless options downgrades its performance. That’s also why we train for our jobs. Chess players may fail to see the best moves. Computers don’t have intuition to consider options and calculate through them. They have sufficient processing power to find better moves than chess players, enabling computers to beat the best human chess players.
So, what if intuition fails you more often than most people? In that case, you consider options other people don’t think of. They may call you crazy or insane. Indeed, most options you consider may not be worthwhile, but you don’t know that until you have found that out yourself. If that applies to you, then you may be autistic. If the condition is sufficiently mild or you are sufficiently intelligent, you can still lead an ordinary life like everyone else, with a job and a spouse. As you lack innate intuition, you must train yourself to do what comes naturally to most people.
An example can illustrate that. Yuor brian autmotaically corercts speillng erorrs. You were probably able to read the previous sentence without any effort. Otherwise, you must solve the puzzle by trying different words in various orders to see if they make sense. In that case, you consider several possible meanings, and perhaps you find something no one else has found. And if there is a hidden meaning, you might only find it in this way.
Many people think of autistic people as weirdos cracking riddles no one else can. Fixing broken mirrors requires patience, dedication, imagination, and determination. Perhaps Newton and Einstein were autistic. They may have appeared to be geniuses simply because they tried ideas others didn’t think of. In this way, they may have discovered things other people couldn’t. Autistic people can keep working on their eccentric projects despite constant rejection. And sometimes, they are on the right track.
Figuring out social rules by trying actions and evaluating others’ responses is a recipe for trouble. Most people make sense of the world intuitively, but if you are autistic, you may have to do it like so. To you, reality appears like a 10,000-piece jigsaw puzzle or a shattered mirror. You must fit the pieces together by applying logic to evidence. That takes a lot of time and effort, and the pieces hardly ever fit perfectly. What you end up with is something similar to what other people consider reality. If you are normal, you make sense of the world intuitively by ignoring misfitting pieces in your model of reality and filling in the gaps with the fairy tales others tell you to believe. However, if you do not, you’re out there, alone in the wilderness, making sense of it yourself.
That can give autists an advantage. As people say, good judgment comes from experience, and experience comes from bad judgment. And autism makes irrational conduct appear irrational, and if you are not autistic, rational behaviour can seem insane. Humans are social animals rather than rational beings. They see crazy as the opposite of normal rather than of rational. So, if irrational is normal, normal people think that rational is insane. And normal is believing fairy tales that have been proven untrue and fighting over them until we are all dead. A group’s survival may depend on the eccentric who walks a different path and accepts the consequences, such as rejection and ridicule. For who else can find the answers when everybody’s intuition fails?
Latest revision: 24 June 2026
1. Thinking, Fast and Slow. Daniel Kahneman (2011). Penguin Books.
Imagine that Jesus’ mother had put a small gold coin weighing 3 grammes in Jesus’ retirement account at 4% interest just after he was born in the year 1 AD. Jesus never retired but he promised to return. Suppose now that the account was kept for this eventuality. Imagine now that the end is near, and that Jesus is about to return. How much gold would there be in the account in 2018?
It is an amount of gold weighing 11 million times the mass of the Earth. The yearly interest would be a gold nugget weighing 440,000 times the mass of the Earth. There is a small problem, a fly in the ointment so to say. It would be impossible to pay out Jesus because there simply isn’t enough gold.
It might seem that the bank had to close long ago because of a lack of gold, but that isn’t true. As long as Jesus doesn’t show up it can remain open, at least if the borrowers are allowed to borrow more to pay for the interest. If the economy grows 4% it may not be such a big deal. The interest can be created out of thin air by making new loans that allow borrowers to pay for the interest. And if Jesus doesn’t claim his gold when he returns and accepts bank credit, everything will be fine.
There is a limited amount of gold while compound interest is infinite. As long as bankers can create money out of thin air to pay for the interest and people accept bank deposits for payment, everything is fine. Problems only arise when people demand real gold. A bank can go bankrupt when depositors want to take out their deposits in gold.
Central banks
Perhaps Jesus’ retirement account isn’t such a big problem after all. Our money isn’t gold but currencies central banks can print. Assume now that Jesus’ mother had put one euro in the account instead. One euro at 4% interest makes 22,000,000,000,000,000,000,000,000,000,000,000 euro after 2017 years. That may seem an intimidating figure, but the European Central Bank can take 22 pieces of paper and print 1,000,000,000,000,000,000,000,000,000,000,000 euro on each of them. And there you are. Something like this happened during the financial crisis of 2008. This is called quantitative easing. You may have heard that word before.
Central banks can print new dollars and euros to cope with a shortfall. In fact, this is what central banks often do. There is always a shortfall because of interest because most money is debt and interest on this debt needs to be paid. To make up for the shortfall, there are two options. First, people can borrow more. Second, central banks can print new currency. Both things can happen at the same time. Central bank decisions about interest rates are also about dealing with the shortfall caused by interest charges.
When central banks lower interest rates, people can borrow more because interest rates are lower. Central banks lower interest rates when people are borrowing less than is needed to cope with the shortfall. If central banks raise interest rates, people can borrow less because interest rates are higher. Central banks raise interest rates when people are borrowing more than is needed to cope with the shortfall and the extra money makes people want to buy more stuff than can be made. And if people don’t borrow at all, this is a crisis, and central banks may print more currency to cope with the shortfall.
Interest on capital versus economic growth
There is a problem central banks can’t fix by printing more currency. Interest is more than just interest on money. Interest is any return on investment. Throughout history returns on investments were mostly higher than the rate of economic growth. Most of these returns have been reinvested so a growing share of total income was for investors. This can’t go on forever because who is going to buy the stuff corporations make in order to keep these investments profitable? A simple example can illuminate that.
Interest income (red) versus total income with interest income growing faster than total income
The graph above shows how total income and interest income (in red) develop with an economic growth rate of 2% and an interest rate of 5% when interest income starts out as 10% of total income and all interest income is reinvested. After 25 years the economic pie has grown faster than interest income and wages have risen. At some point interest income starts to rise faster than total income, and wages go down. After 80 years there’s nothing left for wages. This graph explains a lot about what is going on in reality.
In the short run it was possible to prop up business profits and interest rates by letting people go further into debt to buy more stuff. In the long run, the growth rate of capital income cannot exceed the rate of economic growth. Interest rates depend on the returns on capital so this can explain why interest rates went down in recent years. In the past interest rates below zero weren’t possible but from time to time there were economic crises and wars that destroyed a lot of capital. This created new room for growth.
Wealth inequality and income inequality
When interest rates go down, the value of investments tend to rise. If savings yield little this benefits the wealthy as most people have their money in savings while the wealthy own most investments. But it is important to know the cause otherwise you might think that interest rates should rise. The graph above shows that wealth inequality causes interest rates to go lower, hence redistributing income, for example via higher wages or taxes on the wealthy, can bring higher interest rates.
There is a difference between wealth inequality and income inequality. Your labour income and the returns on your investments are your income. If you are rich but make no money on your investments, your wealth doesn’t contribute to your income. In reality wealthy people make better returns on their investments than others because they have better information and can take more risk. Still, the graph shows that income and wealth inequality can’t increase indefinitely, and that returns on investments can’t exceed the reate of economic growth in the long run, hence interest rates need to go lower.
Most people pay more interest than they receive. The interest paid on mortgages and loans is the proverbial tip of the iceberg. Interest is hidden in rents, in taxes because governments pay interest on their debts, and the price of every product and service because investments have to be made to make these products and services. German research has shown that 80% of the people pay more in interest than they receive, while only the top 10% of richest people receive more in interest than they pay. Lower interest rates benefit most people despite some side-effects that work in the opposite direction.
Economic cycles
Humans are herd animals. They buy stuff and even go into debt to buy stuff when others are going into debt to buy stuff too. Suddenly they may realise that they have bought too much or have gone too deeply into debt, and all at the same time. One day they may be borrowing money, queueing up before the shops, and bidding up prices. The next day, they may decide to pay off their debts, leaving the shop owners with unsold inventories they have to get rid of at fire sale prices. So prices may go up when people are in a buying frenzy and may go down when sales dry up.
When there is a buying frenzy business owners are optimistic and do a lot of investments, and often they go into debt to make those investments. But if suddenly customers disappear, they may be stuck with unsold inventory and debts they cannot repay. Businesses may then have to fire people. Those people are then left without income, and cannot repay their debts too, so sales will go down further. If their debts are not repaid, banks could get into trouble. In most cases the economy will recover. In the worst case banks go bankrupt, money disappears, the economy collapses, and an economic depression takes off.
Interest can make things worse. Assume that you have a business and expect to make a return of 8%. You have € 100,000 yourself and you borrow € 200,000 at 6%. You expect to make 8% so borrowing money at 6% seems a good idea. If you only invest your own € 100,000 you can make € 8,000, but if you borrow an additional € 200,000 you can make € 12,000 (8% of € 300,000 minus 6% of € 200,000, which is € 24,000 minus € 12,000). The balance sheet of your business might look like this:
debit
credit
inventory
€ 250,000
loan 6%
€ 200,000
cash, bank deposits
€ 50,000
owner’s equity
€ 100,000
total
€ 300,000
total
€ 300,000
If sales disappoint and you only make a return of 2% on your invested capital of € 300,000, which is € 6,000, you make a loss because you pay € 12,000 in interest charges. You may have to fire workers. Businesses can go bankrupt because they have borrowed too much and have to pay interest, even when they are profitable overall. Sales often disappoint when the economy fares poorly. This means that more businesses face the same difficulties and make losses because of interest payments. They may have to fire workers and these workers lose their income. This can worsen the slump.
Interest, economic depressions and war
Silvio Gesell discovered that interest rates can’t go below a certain minimum because lending would then stop. Money would go on strike as he put it. Why is that? Low yields make investing and lending money unattractive because of the risks involved. Debtors may not repay and banks may go bankrupt. Depositors then prefer to take their money out of the bank and keep it with themselves.
This can cause economic crises and depressions. Silvio Gesell lived around 1900. Interest rates below zero weren’t possible because of the gold standard. Depositors could go to the bank and withdraw their deposits in gold so that they didn’t have to accept negative interest rates. From time to time there were bank runs, economic crises and wars that destroyed a lot of capital. And this created new room for growth.
There may be a relationship between interest, economic depressions and war. In 1910 the amount of capital income (the red circle in the graph) relative to total income (the two circles together) was close to what it was in 2010. This could have led to an economic depression but then came World War I. The war destroyed a lot of capital so that there was new room for capital growth and interest rates could remain positive.
A few decades later the Great Depression arrived. If interest rates could have gone below zero in the 1930s, the Great Depression might not have happened, Adolf Hitler would not have risen to power and World War II would not have occurred. The currency of Wörgl demonstrates that negative interest rates could have ended the depression. After World War II interest rates never came near zero again. Governments and central banks printed more money. This caused inflation, which eroded trust in money.
People feared that inflation would make their money worth less so interest rates rose. In the 1970s the link between money and gold was abandoned because there was a lot more money than there was gold to back it. In the 1980s governments and central banks started policies to bring down inflation and to promote trust in money. As of 1983 interest rates went down gradually as a consequence of a renewed trust in money and central banks. Debt levels rose and interest rates went near zero.
Promoting inflation might not be a good idea. The end result is unpredictable. The best one can hope for is a poor performing economy and a lot of inflation like in the 1970s. But if interest rates rise because lenders lose their trust in money and debts, people may not be able to repay their debts, and the financial system might get into serious trouble. This can cause another great depression or another great war. But if the alternative is negative interest rates, stability and prosperity, then why not opt for that?
Featured image: Of Usury, from Brant’s Stultifera Navis (the Ship of Fools). Albrecht Dürer (1494). Public domain.
In the middle of the Great Depression, the Austrian town of Wörgl was in deep trouble and prepared to try anything. Of its population of 4,500, 1,500 people were without a job, and 200 families were penniless. Mayor Michael Unterguggenberger had a list of projects he wanted to accomplish, but there was not enough money to carry them out. These projects included paving roads, erecting streetlights, extending water distribution across the whole town, and planting trees along the streets.1 2
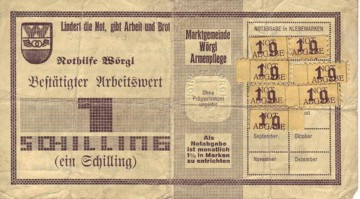
Rather than spending the remaining 32,000 Austrian Schilling in the town’s coffers to start these projects, he deposited them in a local savings bank as a guarantee to back the issue of a currency known as stamp scrip. A crucial feature of this money was the holding fee. The Wörgl money required a monthly stamp on the circulating notes to keep them valid, amounting to 1% of the note’s value.1 2 An Argentine businessman named Silvio Gesell had come up with this idea in his book The Natural Economic Order.
Nobody wanted to pay for the monthly stamps, so everyone spent the notes they received. The 32,000 schilling deposit allowed anyone to exchange scrip for 98 per cent of its value in schillings. Hardly anyone did this because the scrip was worth one Austrian schilling after buying a new stamp. But people did not keep more scrip than they needed. Only 5,000 schillings circulated. The stamp fees financed a soup kitchen that fed 220 families.1 2
The municipality carried out the intended works, including new houses, a reservoir, a ski jump and a bridge. The key to this success was the fast circulation of the scrip money within the local economy, fourteen times higher than the schilling. It increased trade and employment. Unemployment in Wörgl dropped 25% while it rose in the rest of Austria. Six neighbouring villages copied the idea successfully. The French Prime Minister, Édouard Daladier, visited the town to witness the ‘miracle of Wörgl’ himself.1 2
In January 1933, the neighbouring city of Kitzbühel copied the idea. In June 1933, Mayor Unterguggenberger addressed a meeting with representatives from 170 Austrian towns and villages. Two hundred Austrian townships were interested in introducing scrip money. At this point, the central bank decided to ban scrip money.1 2
Since then, several communities have issued local scrip currencies. None of them was as successful as the currency of Wörgl. The reasons probably are:
There was no economic depression, and the economy could support interest, so introducing scrip money had little effect.
If scrip money is not widely accepted, people will exchange it for regular currency if they can’t use it.
In Wörgl, the payment of taxes in arrears generated additional revenues for the town council, which the town council spent on public projects. Once the townspeople had paid their taxes, they would have run out of spending options and might have exchanged their scrip for schillings to avoid paying for the stamps. That never happened because the central bank halted the project.
There are, however, a few issues to consider. The economy of Wörgl did well without issuing debt because the money kept circulating. A negative interest rate induces people to spend the money they have, so no new money has to be borrowed into existence to stimulate the economy. A holding fee makes negative interest rates possible as you do not have to pay it when lending money. For instance, lending out money at an interest rate of -2% is more attractive than paying 12% for the stamps. If we can uncover the conditions for it to work, remove its flaws, and plan for the consequences, we can have a usury-free financial system.
Natural Money
Introducing negative interest rates in the global financial system may have great benefits. The website Naturalmoney.org features an in-depth research of the feasibility and consequences of negative interest rates.
Ancient Egypt had a similar type of money for more than 1,000 years. There is an account in the Bible that may explain how this money came into existence.
Featured image: Wörgl bank note with stamps. Public Domain.
1. The Future Of Money. Bernard Lietaer (2002). Cornerstone / Cornerstone Ras. 2. A Strategy for a Convertible Currency. Bernard A. Lietaer, ICIS Forum, Vol. 20, No.3, 1990. [link]
On 15 July 2011, two television towers in the Netherlands caught fire. One collapsed spectacularly. There had never been a fire in a television tower in the Netherlands. These television towers had been there for over fifty years. And there were only twenty-four of them. A few people speculated about these incidents having a common cause.1 The towers are in different areas, making a common cause unlikely unless there is intent. After all, what is the chance of two aeroplanes crashing into both towers of the World Trade Center in New York on the same day? Only there was no evidence suggesting intent or a common cause. That makes it very mysterious.
Consider this coincidence from Bermuda, which is near the mysterious Bermuda Triangle. In 1975, a 17-year-old boy had a deadly accident while riding his moped. He died exactly a year after his 17-year-old brother died in an accident while riding the same moped in the same intersection and collided with the same taxi with the same driver, carrying the same passenger. Repeating patterns may have contributed to the incident. Perhaps it was a dangerous point where accidents frequently occurred. The passenger may have visited Bermuda once a year and taken a taxi from the airport to the same destination each time.
In 1992, I was bicycling in Groningen, where I lived at the time. On the way, a car door suddenly opened just before me. I could barely avoid a collision. About ten minutes later, on the same trip, it happened again with another car on another road. Never before or after this trip had a car door opened in front of me, even though I had made bicycle trips nearly every day for several decades. It is odd. But what are the odds?
Those incidents might be random events. Many things happen all the time, so bizarre accidents occur by chance. It doesn’t require a Supreme Puppet Master to make them happen. It may be hard to calculate the probability of an event like two television towers catching fire in one country in one day, but it is very low. Only, the number of possible strange incidents is very high.
But how low and how high? That matters tremendously. If there are a million possible events, and the chance of one happening on any given day is one in a million, we should not be surprised when one does. On average, an event like that should happen every day. If it is one in a trillion, and such an event occurs quite frequently, we are on to something, because, on average, it should happen once every million days.
The number of possible strange coincidences is infinite, so it shouldn’t surprise us that simple coincidences, such as a car door opening in front of me twice on a single bicycle trip, happen from time to time. It is, however, odd that it happened twice on one trip and never on any other. Coincidences come in different types. The more intricate a coincidence is, the less likely it is to occur. Indeed, some complicated coincidences are far less likely to occur than two car doors opening on one bicycle trip.
The following falls in the latter category. Once, I entered a do-it-yourself store. There was a couch near the entrance. The price tag of € 389 caught my attention. As a student, I lived in dormitory 389 on the campus. Price tags often end with a nine, so there was nothing suspicious about it, I concluded. Strange things had happened, so I tried to convince myself that it was not unusual. I realised it would be far more curious to find a price tag of € 401, as I had also lived in building 401, and price tags rarely end in a 1.
A few seconds later, I ran into a pile of bags of potting soil. These bags had a conspicuous lettering ’40l’, indicating they contained 40 litres of potting soil. That was close enough to 401 to be intriguing. There were no other types of bags on the spot. Potting soil is available in 10, 20, 25, 40, and 50-litre sizes. Sacks of 40 litres also come with markings such as ’40L’ and ’40 litres’. Hence, the ’40l’ was indeed remarkable.
Two years later, I returned to the same store. These bags of potting soil, marked ’40l’, stood conspicuously stacked near the entrance, reminding me of the previous incident. There was no couch, and I did not see a € 389 price tag there. I contemplated this while fetching the item I planned to buy. Its price tag was €3.89, and I had gone to the store to purchase that one item.
That is far less likely to happen than two car doors opening before me on the same bicycle trip. The events interacted with my thoughts, and the sequel made it even more improbable. The car doors opening could be a coincidence, but the do-it-yourself store incident should boggle the mind, provided one is allowed to think. In one of those dormitories, I met a most peculiar Lady. Since then, a series of noteworthy coincidences have transpired, reminding me of that. This coincidence thus also fits into this scheme, further heightening its peculiarity.
To make the coincidence happen, the bags of potting soil had to be in place, so I would run into them just after thinking of 401. And later, I had to go there to buy an item for € 3.89. And it goes much further than that. The scheme encompasses the item having a price tag of € 3.89, and my having lived in dormitories 389 and 401. That is most peculiar indeed. So much can go wrong. Imagine the bags’ content being 50 litres, the lettering being different, or me visiting another do-it-yourself store or buying another item the second time, and the scheme would fall apart. Perhaps it is a mere coincidence, but it is less likely than two car doors opening in front of me during the same bicycle trip.
On the evening of 11 October 2025, my wife and I watched episode ‘Demon 79’ of the Netflix series Black Mirror. The story played in Great Britain in 1979. It turned out that the murder of two people by a psychotic shoe saleswoman, following orders of a demon disguised as Boney M band member Bobby Farrell, proved insufficient to ward off the apocalypse. The apocalypse proved to be a nuclear war. After watching it, I went to bed. The next morning, I first read the news headlines on the teletext page 101 of the Dutch public television, and found out that two people had died at age 79, actress Diane Keaton and singer Joost Nuissl. So, two people died, thus not enough to ward off nuclear war. Two days later, on 14 October 2025, a NATO exercise named Steadfast Noon began. It included dropping fake atomic bombs above the area where I live. ‘You can sleep peacefully,’ a NATO spokesman added.
Latest revision: 14 October 2025
Featured image: Number 381 dormitory. University Of Twente (2013). [copyright info]
1. Onderzoek: Hoe konden twee zendmasten vandaag in brand vliegen? Algemeen Dagblad (15-07-2011). [link]