1919 Cover of The Natural Economic Order

Feasibility of Interest-Free Demurrage Currency

Setup

Natural Money is an interest-free demurrage currency. It features a holding fee on currency and a maximum interest rate of zero on money and loans. The Natural Money currency is an accounting unit only, as the holding fee, which may range from 0.5% to 1% per month, makes the currency unattractive to hold. Therefore, the currency will not circulate, nor will anyone invest in it. Cash, bank deposits, bonds, stocks, real estate, and other investments aren’t currency and therefore not subject to the holding fee. Not paying the holding fee and curtailing credit, thereby promoting inflation, can make negative-interest lending attractive.

Natural Money distinguishes between regular banking, also known as commercial banking, which involves lending and borrowing, and investment banking, also known as participation banking, which involves participating in businesses. Regular banks guarantee returns to their depositors and use their capital to cover losses. Participating banks have shareholders who share in the profits and the losses. These two bank types should remain separated, even though one bank might offer both in distinct accounts. A commercial bank’s funds should be used only for lending. The maximum interest rate limits lending, allowing equity to replace debt in the financial system.

Evidence from history

There is little historical data on interest-free demurrage currency. Financial systems founded on interest-free money with a holding fee have never existed. There were holding fees and interest bans, but not a combination of both. In other words, it is a theoretical fantasy land. But so are many scientists working on fundamental breakthroughs. Moreover, a usury-free financial system requires a high-trust society founded on moral values, in which investments are safe. That is only feasible with the help of several relatively modern financial innovations. It all seems too good to be true, but we can have dreams. In any case, historical evidence is of limited value.

Ancient societies have seen usury-induced economic crises. Extreme wealth inequality, often accelerated by usurious lending, coincided with societal collapses. Yet other factors, like misharvests, trigger the problems. It is a recurring pattern that has existed since time immemorial. The Sumerians were already familiar with charging interest and its disastrous social consequences. Sumerian rulers began implementing debt jubilees as early as 2,400 BC, cancelling debts and freeing debt slaves. Other cultures, such as those in Israel, have banned charging interest. Israel also had debt jubilees every fifty years.

The Egyptian grain-backed currency existed for over 1,000 years, suggesting it provided monetary stability. Nevertheless, ancient Egypt has experienced economic crises, often due to droughts that caused crop failures, high taxation during warfare, or a weakening central government. The government mitigated famines with its grain reserves, but prolonged famines depleted these facilities, leading to civil unrest and, sometimes, a collapse of order. There is no evidence of social benefits of this money for Egyptian society. Charging interest was common, and Egypt had debt cancellations.

In the Middle Ages, the Church forbade charging interest. Christians, like Jews, were each other’s brothers and couldn’t charge each other interest. When economic life became more developed, the ban on interest became difficult to enforce. In the 14th century, partnerships emerged where creditors received a share of the profits from a business venture. As long as the share remained profit-dependent, it was not illegal, as it was a participation in a business rather than lending at interest.1 Islamic finance works with similar principles.2

In the 17th and 18th centuries, interest ceilings replaced bans. To circumvent the interest ceilings, a creditor and debtor could secretly agree on a fraud, whereby the creditor handed over less money than stated in the loan contract, so that the borrower actually paid more interest.3 More recent experiences with Regulation Q in the United States, which imposed maximum interest rates on bank accounts, suggest that a maximum interest rate is enforceable only if it does not significantly impact the bulk of borrowing and lending.4

A ban on usury requires a society grounded in moral values rather than profit. It requires us to live modestly and within the planet’s limits. It also requires societies to care for vulnerable individuals, so that they don’t fall prey to usurers. You shouldn’t charge interest, not merely because it is illegal, but because it contributes to something profoundly evil. That points to a broader problem. We should care about the world and consider the consequences of our actions. Even when what we do is legal, it doesn’t mean that it is good.

Implementation

To implement Natural Money, interest rates must already be low or negative. Efforts to lower interest rates when market conditions don’t warrant it scare investors. Low interest rates require trust, which in turn requires financial discipline, including fiscal discipline by governments. That doesn’t equal austerity, since governments earn interest on their debts when interest rates are negative. The transition is preferably a gradual process that the authorities communicate in advance. Whether that is possible at all remains to be seen, as the implementation may occur in exceptional times.

If there is a functional currency, the government should balance the budget first, allowing interest rates to decline. The second step is to decouple cash currency from the administrative or central bank currency. The move encompasses retiring central bank-issued banknotes and replacing them with treasury-issued banknotes. Not everyone will hurry to a local bank office to exchange banknotes, so the central bank-issued banknotes must be exchangeable at par for the new banknotes for a considerable period.

As long as interest rates are significantly above zero, a holding fee won’t bring them down. Setting a maximum interest rate can lower interest rates by curtailing credit, thereby cooling the economy. To avoid disrupting financial markets, the implementation must be gradual. The maximum interest rate should be high enough to avoid disrupting the economy. Initially, authorities could set the holding fee at a low percentage, or not at all. As interest rates fall, authorities can lower them.

The zero lower bound is a minimum interest rate. It operates like a price control by preventing interest rates from moving freely to the rate where supply and demand for money and capital balance. That is to the advantage of the wealthy, as they can take the economy hostage by demanding a minimum return on their investments. When returns are low, investors may prefer cash over investments, which can hinder an economic recovery. Economists call it liquidity preference.

Low interest rates can prompt lenders to seek higher yields and take on more risk. Low interest rates allow borrowers to take on more debt. Low interest rates can encourage investments that become unprofitable when the economy slows. A maximum interest rate can prevent these situations from happening. A maximum interest rate caps the risk lenders are willing to take and promotes balance-sheet deleveraging, so that low-yielding ventures don’t go bankrupt because of interest-bearing debt.

Issues with the maximum interest rate

A holding fee will cause few difficulties, but a maximum interest rate is more problematic. Insofar as the maximum interest rate affects questionable segments of credit, such as credit card debt and subprime lending, this is beneficial overall. More serious issues can emerge with financing small and medium-sized businesses. Partnership schemes can fill in the gap, but it is hard to predict how that will play out. The maximum yield on loans is zero, making partnerships more attractive, as they can offer higher returns.

There may be objections to the limits Natural Money imposes on consumer credit. Still, there is little doubt that a maximum interest rate can improve consumers’ purchasing power, as borrowers won’t have to pay interest. As a result, there are fewer borrowing options, which may lead to the emergence of black markets. To make illegal schemes unattractive for lenders, lenders who charge interest could lose the money they have lent.

Zero is the only non-arbitrary number, making it more difficult to change the maximum interest rate. That may happen for political or other reasons. If it is one, why not two? Zero is a clear line. A positive interest rate, however small, contributes to financial instability. All positive growth rates compound to infinity, so once we start the fire of usury, it will eventually consume us.

A maximum interest rate seems feasible if it is above the rate at which most borrowing and lending occur, thereby limiting the effects on liquidity in the fixed-income market. A maximum interest rate creates room for alternatives, such as private equity and partnership schemes. These alternatives can supplement the fixed-income market and mitigate the effects of the maximum interest rate. A maximum interest rate is beneficial overall if it mainly affects questionable segments of credit, such as subprime lending.

For bonds, the maximum interest rate is zero at issuance. Due to economic circumstances or issues with the debtor, the interest rate may rise and enter positive territory. Likewise, governments may issue long-term bonds that may yield positive returns if interest rates rise later. That is not a serious issue, as long as the interest rate was zero or lower at the time of issuance.

A serious issue is liquidity. When interest rates rise, less credit becomes available at zero or lower rates. Interest rates might increase due to a strong economy with inflationary pressures. There are always economic agents who must borrow at all costs to meet their present obligations. If they can’t borrow, they might go bankrupt. Businesses and individuals need to deleverage and arrange credit in advance, such as an overdraft facility, with their banks.

Another equally serious question is the profitability of banks with Natural Money. Their lending business will likely shrink. The assumption is that risk-free lending will be profitable. But what if it isn’t? In that case, banks may need to lower deposit account interest rates below the interest rate on short-term government debt. In that case, the cash interest rate may need to be lower than the interest rate on short-term government debt for it to work.

Inherent stability

Ending usury is impossible without investors’ trust in the political economy or in the political and economic institutions of the polity issuing the currency. The most trusted political economies have the lowest interest rates because their governments are fiscally responsible. Natural Money requires taking it to the next level. With Natural Money, to borrow, the government must find lenders willing to lend in the currency at negative interest rates. The government will be better off borrowing at negative interest rates, which provides an incentive for budgetary discipline. That is the foundation of stability.

Extracting a fixed income from a variable income stream contributes to financial instability. Fixed interest payments can bankrupt a corporation even when it is profitable overall. Interest contributes to moral hazard by serving as a reward for taking risks. Investors expect to earn higher yields on riskier debt, so lenders take on these risks. The more uncertain an income source, the higher the interest rate needs to be to compensate for the risk of lending; but the higher the fixed interest rate, the more likely failure becomes, revealing the destructive consequence of interest being a reward for taking risks.

All parts of the financial system are intertwined. Individual banks can transfer these risks to the system. And so, the risk management of individual agents can increase the system’s overall risk level. The payment and lending system is a key public interest, so governments and central banks back it. Banks take risks and reap rewards in the form of interest, while public guarantees back up the financial system. The arrangement leads to moral hazard, a mispricing of risk and private profits at the expense of the public. A maximum interest rate can end these problems.

A maximum interest rate causes a deleveraging and a reduction in problematic debts, which has a stabilising effect on the financial system and the economy. Individuals and businesses must already take action before their debts become problematic. Maximum interest rates can distort financial markets. Most notably, there will be fewer options for smaller firms to borrow. Partnership schemes should fill that void.

Interest payments also affect business cycles. The mainstream view is that central banks should raise interest rates during economic booms to curb investment and spending, thereby preventing the economy from overheating. A rosy view of the future prevails during a boom, so higher interest rates seem justified, and borrowing continues for some time. When the bust sets in, the picture alters, and an overhang of debt at high interest rates worsens the woes. It would have been better if these debts hadn’t existed in the first place.

That makes a usury-based financial system inherently unstable. Natural Money changes this dynamic. When the economy improves, higher interest rates increase the attractiveness of equity investments relative to debt. That reduces the funds available for lending. The curtailment of credit will prevent the economy from overheating and avoid a debt overhang. When the economy slows, negative interest rates provide stimulus. In the absence of a debt overhang, the economy is likely to recover soon. A Natural Money financial system is inherently stable.

Featured image: 1919 Cover of The Natural Economic Order. Wikimedia Commons.

1. Simon Smith Kuznets, Stephanie Lo, Eric Glen Weyl (2009). The Doctrine of Usury in the Middle Ages. Simon Smith Kuznets, transcribed by Stephanie Lo. An appendix to Simon Kuznets: Cautious Empiricist of the Eastern European Jewish Diaspora.
2. Sekreter, Ahmet (2011). Sharing of Risks in Islamic Finance. IBSU Scientific Journal, 5(2): 13-20.
3. K. Samuelsson (1955). International Payments and Credit Movements by the Swedish Merchant Houses, 1730-1815. Scandinavian Economic History Review.
4. R. Alton Gilbert (1986). Requiem for Regulation Q: What It Did and Why It Passed Away. Federal Reserve Bank of St. Louis.
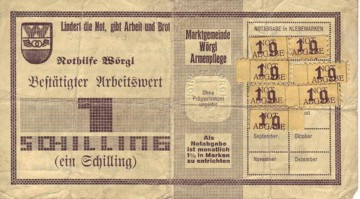
Wörgl bank note with stamps. Public Domain.

Short Introduction

End of growth

The last 200 years have been an era of exceptional economic growth, unlike anything the world has ever seen. As with any exponential phenomenon in a limited space, the growth of human economic activities will end in one way or another. An innovation drive fuels economic growth. Economists call it creative destruction. We are now reaching the point where humans will be no match for artificial intelligence, and humanity is about to be creatively destroyed in the process. If humanity is to survive, and I have worked with that hypothetical scenario in mind, it will have implications for financial markets. And we have limited resources. If we halt innovation, we can be sure this will remain the case. For most of history, people had barely enough. Today, there is a massive excess in the bullshit economy, transforming energy and resources into waste and pollution to make money for investors by producing and marketing non-essential products and services.

For most of history, economic growth has been negligible. However, it averaged 1.5% over the last two centuries. It will soon return to zero, or possibly lower, in the hypothetical scenario that seems to require a miracle. Miracles are outside the scope of finance and economics, so also outside the scope of this treatise. It has implications for returns on investments, the financial system and interest rates. Investors have become hooked on positive returns. Without growth, investors lose confidence, which may cause collapse because the economy runs on credit, and credit means trust. And so, it is grow or die. Before modern times, humans managed to live without economic growth because there was hardly any capital or interest-bearing debt. Past civilisations facing usury-induced economic collapses either disappeared, banned interest, or instituted debt cancellations.

Indeed, the past 200 years have been an exceptional phase in human history. And because we don’t live that long, we think growth is normal. Low interest rates were essential for prosperity. Efficient financial markets promoted growth by depressing interest rates, thereby making the Industrial Revolution profitable. Low interest rates have brought unprecedented wealth, albeit at the expense of the planet and future generations. That doesn’t sound all good. Yet, after growth has ended, low interest rates remain key to prosperity, even when it is making the most of what we have. The benefit of low interest rates is an enduring rule that doesn’t depend on temporary economic conditions. Even more so, when economic growth returns to sustainable levels, so close to zero, there is no growth to pay interest from, so that we will either have to end lending or end usury. Luckily, a usury-free financial system already exists: Natural Money.

The nature of usury

Suppose Jesus’ mother, as a lady of great foresight, had opened a retirement account for Jesus shortly after his birth in 1 AD at the Bank of the Money Changers next to the Temple in Jerusalem. Suppose further that she had put a small gold coin weighing three grammes in Jesus’ retirement account at 4% interest. Jesus never retired, but he promised to return. Suppose now that the bank held the money for this eventuality. How much gold would there be in the account in the year 2020? It would be an amount of gold weighing 12 million times Earth’s mass. There isn’t enough gold to pay out Jesus if he returns.

And so the usurers hope he doesn’t come back, also for other reasons, of course. For every lending, there is borrowing. The bank is merely an intermediary. And so, there must be people in debt for an amount of gold weighing twelve million times the mass of the Earth. That would never happen. The scheme would have collapsed long before that, and the debtors would have become the serfs of the moneylenders. That is why religions like Christianity and Islam forbade charging interest on money or debts.

Yet, the usurers, those sneaky goatlike creatures, have found a way around the issue. Our money isn’t gold anymore. Banks create money from thin air, so the nature of usury has changed. When you go to a bank and take out a loan, such as a car loan, you receive a deposit in exchange for a debt, which the bank creates on the spot through two bookkeeping entries. This magic is commonly referred to as creating money. You keep the debt, but the deposit becomes someone else’s money once you purchase the car. When you repay the loan, the deposit and the debt vanish into thin air. You must repay the loan with interest. If the interest rate is 5% and you have borrowed €100 for a year, you must return €105. Something doesn’t add up there.

Nearly all the money we use is created from loans that borrowers must repay with interest. If our borrowing creates money, and we repay our debts with interest, then we may do so by borrowing the interest. That is also what happens in reality, and that is why debt levels continue to rise. So, where does the extra €5 come from? Here are the options:

  • Borrowers borrow more.
  • Depositors spend some of their balance.
  • Borrowers fail to repay their loans.
  • The government borrows more.
  • The central bank prints the money.

Problems arise when borrowers don’t take on more debt and depositors don’t spend their money. In that case, borrowers as a group are short of funds, and some of them are unable to repay their loans. If too many borrowers can’t pay at once, a financial crisis occurs. To prevent that from happening, the government borrows more, and the central bank prints money. They bring that money into the economy, allowing debtors to pay off their debts with interest. Interest compounds to infinity, and there is no limit to human imagination, so frivolous accounting schemes like usury can go a long way before they collapse. But eventually, they collapse. And others may attribute it to different causes. It is possible to have responsible lending at interest. And so, it is pointless to argue.

Necessity of interest

We take interest for granted, and economists believe that we need it. Without lending and borrowing, a modern capitalist economy would have been impossible. And without interest, making loans would be impossible. Money is to the economy what blood is to the body. If lending and borrowing halt, money stops flowing, and the economy comes to a standstill. That is akin to a cardiac arrest. If left untreated, it brings about the economy’s funeral. That is why the financial press reads the lips of central bankers as if our lives depend on it. They manage the flow. Lenders have reasons to demand interest. These are:

  • When you lend out money, you can’t use it yourself. That is inconvenient. And so, you expect compensation for the use of your money.
  • The borrower may not repay the loan, so you desire compensation for that risk.
  • You can invest your money and earn a return. To lenders, the interest rate must be attractive relative to other investments.

That has been the case for a long time, and economists have gradually become quite good at explaining the past. Since then, we have seen financial innovations and are now facing the end of growth. Changes in the economy and the economic system may lead to the end of interest on money and debts. These are:

  • You can use the money in a bank account at any time. You can use the money you have lent as if it were cash. And a debit card is more convenient than cash.
  • Banks spread their risks, central banks help out banks when needed, and governments guarantee bank deposits, so bank deposits are as safe as cash.
  • There is a global savings glut. There are ample savings and limited investment options, which can make negative interest rates attractive for lending.

Negative interest rates are possible. In the late 2010s and early 2020s, the proof came when most of Europe entered negative interest-rate territory. The ECB was unable to set interest rates below -0.5%. Had it set interest rates even lower, account holders would have emptied their bank accounts and stuffed their mattresses with banknotes to avoid paying interest on their deposits, disrupting the circular flows.

As interest rates couldn’t go lower, the ECB took extraordinary measures, flooding the banking system with new money to boost the economy. Had there been a holding fee on cash, interest rates could have gone lower, and there would have been no need to print money. It has happened before. The Austrian town of Wörgl charged a holding fee on banknotes during the Great Depression, which led to an economic miracle by encouraging existing banknotes to circulate more freely rather than printing new money. Ancient Egypt had a similar payment system for over a thousand years under the Pharaohs.

Miracle of Wörgl

In the midst of the Great Depression, the Austrian town of Wörgl was in dire straits and prepared to try anything. Of its 4,500 residents, 1,500 were jobless, and 200 families were penniless. Mayor Michael Unterguggenberger had a list of projects he wanted to accomplish, but there wasn’t enough money to fund them all. These projects included paving roads, installing street lights, extending water distribution throughout the town, and planting trees along the streets.1

Rather than spending the remaining 32,000 Austrian Schilling in the town’s coffers to start these projects, he deposited them in a local savings bank as a guarantee to back the issue of a currency known as stamp scrip. A crucial feature of this money was the holding fee. The Wörgl money required a monthly stamp on circulating notes to keep them valid, at 1% of the note’s value. The German-Argentine businessman Silvio Gesell had first proposed this idea in his book The Natural Economic Order.2

Nobody wanted to pay for the monthly stamps, so everyone spent the notes they received. The 32,000 schilling deposit allowed anyone to exchange scrip for 98 per cent of its value in schillings. Few did this because the scrip was worth one Austrian schilling after buying a new stamp. But the townspeople didn’t keep more scrip than they needed. Only 5,000 schillings circulated. The stamp fees paid for a soup kitchen that fed 220 families.1

The municipality carried out the works, including the construction of houses, a reservoir, a ski jump, and a bridge. The key to this success was the circulation of scrip money within the local economy. It circulated fourteen times as often as the schilling. It increased trade and employment. Unemployment in Wörgl decreased while it rose in the rest of Austria. Six neighbouring villages successfully copied the idea. The French Prime Minister, Édouard Daladier, visited the town to witness the ‘miracle of Wörgl’ himself.1

In January 1933, the neighbouring city of Kitzbühel copied the idea. In June 1933, Mayor Unterguggenberger addressed a meeting with representatives from 170 Austrian towns and villages. Two hundred Austrian townships were interested in introducing scrip money. At this point, the central bank decided to ban scrip money.1 The depression returned, and in 1938, the Austrians turned to Hitler, as they voted to join Germany.

Since then, several local scrip monies have circulated, but none has been as successful as the one in Wörgl. In Wörgl, the payment of taxes in arrears generated additional revenue for the town council, which it then spent on public projects. Once the townspeople had paid their taxes, they would have fewer spending options and might have exchanged their scrip for schillings to avoid paying for the stamps. Once all the taxes in arrears had been paid, the economic boost would have petered out. That never happened because the central bank had halted the project prematurely.

The economy of Wörgl also did well because the holding fee kept the existing money circulating. A negative interest rate encourages people to spend their money, eliminating the need to borrow and keeping the money circulating in the economy. It demonstrated that the economy performed better under negative interest rates. A holding fee makes negative interest rates possible, as lenders do not have to pay it after lending the money. The one who holds the money pays the charge. That can make lending money at an interest rate of -2% to a reliable borrower more attractive than paying 12% for the stamps.

Joseph in Egypt

In the time of the Pharaohs, the Egyptian state operated granaries for over 1,500 years. Wheat and barley were the primary food sources in Egypt. Whenever farmers brought their harvest to one of the granaries, state officials issued them receipts stating the amount of grain they had brought in. Egyptians held accounts at the granaries. They transferred grain to others as payment or withdrew grain after paying the storage cost.

The Egyptians thus used grain stored in their granaries for making payments. Everyone needed to eat, so grain stored in the granaries had value.1 Due to storage costs, the money gradually lost its value. With this kind of money, interest-free loans might be possible. If you save grain money, you pay for storage. And so, lending the money interest-free to a trustworthy borrower can be attractive. There is no evidence that this happened.

The origin of these granaries remains unclear. Probably, the state collected a portion of the harvests as taxes and stored them in its facilities. The government storage proved convenient for farmers, as it relieved them of the work of storing and selling their produce. And it made sense to have a public grain reserve in case of harvest failures.

The Bible includes a story claiming that a Jewish man named Joseph built these granaries. As the story goes, a Pharaoh once had a few dreams that his advisers couldn’t explain. He dreamed about seven lean cows eating seven fat cows and seven thin, blasted ears of grain devouring seven full ears of grain. Joseph explained those dreams to the Pharaoh. He told the Pharaoh that seven years of good harvests would follow, followed by seven years of crop failures. Joseph advised the Egyptians to store food for hard times. They followed his advice and built grain storehouses. In this way, Egypt managed to survive the seven years of scarcity that followed.

The grain money gradually lost value due to storage costs. It works like buying stamps to keep the money valid, like in Wörgl. Both are holding fees. The difference is that you don’t have to buy stamps to keep the money valid. Instead, the granary officials netted the charge with the principal when someone made a payment or exchanged a voucher for grain. The grain money circulated for over 1,500 years until the Romans conquered Egypt around 40 BC. It didn’t end in a debt crisis, which suggests that a holding fee on money or negative interest rates can create a stable financial system that lasts forever.

Storing food makes sense today, even when it costs money. Harvests may become more unpredictable due to global warming and intensive farming. We have enough food in storage to feed humanity for only a few months, as storing more is unprofitable. Food storage ties up capital, so there is an interest cost. But you can’t eat money, so storing food to deal with harvest failures is as sensible now as it was in the time of the Pharaohs. It reveals the foolishness of our money-centred thinking. We only survive if it is financially viable. Imagine how that will play out once artificial intelligence and robots do a better job than we do at a lower cost.

Natural Money

The miracle of Wörgl suggests that national currencies with holding fees could have ended the Great Depression. A myth circulating in the interest-free currency movement is that had the Austrian central bank not banned the experiment, the idea would have spread, the Great Depression would have ended, Hitler wouldn’t have come to power, and World War II wouldn’t have happened. That is a tad imaginative, to say the least, but a holding fee could have allowed for negative interest rates, and they could have prevented the Great Depression from starting in the first place.

And such money can last. The grain money in ancient Egypt provided a stable financial system for over 1,000 years. The grain backing provided financial discipline. The holding fee prevented money hoarding that could have impeded the flow of money. The money, however, didn’t promote interest-free lending, so the Egyptian state regulated interest-bearing lending to prevent debt slavery. Egyptian wisdom literature condemned greed and exploitative lending, encouraging empathy for vulnerable individuals.

A holding fee of 10-12% per year punishes cash users. If the interest rate on bank accounts is -2%, a -3% interest rate on cash is sufficient to prevent people from withdrawing their money from the bank. That becomes possible once cash is a separate currency backed by government debt, on which the interest rate on short-term government debt applies. Banknotes and coins can be separate from the administrative currency. So, if the interest rate on the cash currency is -3%, one cash euro will be worth 0.97 administrative euros after one year. And now, we have a definition of Natural Money:

  • Cash is a separate currency backed by short-term government debt and has the negative interest rate of short-term government debt.
  • Natural Money administrative currencies carry a holding fee of 10-12% per year, allowing for negative interest rates.
  • Loans, including bank loans, have negative interest rates. Zero is the maximum interest rate on debts.

Consequences

Natural Money doesn’t fundamentally alter the nature of bank lending. Banks borrow from depositors at a lower rate to lend it at a higher rate. With Natural Money, banks may offer deposit interest rates of -2% and lend at 0% instead of borrowing at 2% to lend at 4%. A maximum interest rate of zero, however, has a profound impact on lending volume, as it severely constrains it, most notably speculative lending and usurious consumer credit, and it favours equity financing over borrowing in business. The strict lending requirements affect business loans, leading to deleveraging.

Businesses still need to attract capital. To address the issue, Natural Money distinguishes between regular banks and investment banks. Regular banks can guarantee promised returns and have government backing because the payment system is a public service. Investment banks invest in businesses and take risks. They are comparable to Islamic banks. Investment banks don’t guarantee returns. Depositors take on risk to earn higher returns, but they might incur losses or temporarily lose access to their deposits.

While the maximum interest rate restricts lending, the holding fee provides a stimulus, thereby stabilising the financial system. When the economy slows, interest rates decrease, and more money becomes available for lending as risk appetite increases, making zero-interest lending more attractive. Conversely, if the economy booms, interest rates increase, and the maximum interest rate curtails lending. Consequently, central banks don’t need to set interest rates and manage the money supply, and governments don’t need to manage aggregate demand with their spending.

Reasons to do research

Stamp scrip and other kinds of emergency money have helped communities during times of economic hardship. The economic miracle of Wörgl during the Great Depression of the 1930s, however, was exceptional. The payment of local taxes inflated the impact of the money. Many townspeople had been late on their taxes, but once the economy recovered, they had the money to pay them. Some even paid their taxes in advance to avoid paying the holding fee. It generated additional revenues for the town, which it could spend on the projects. It provided a boost that would have petered out once the villagers had paid their taxes.3 It was not a miracle. It was too good to be true. However, there is more to it, which makes the idea worth researching.

Once interest rates reach zero, the markets for money and capital cease to function, as interest rates can’t go lower. Money is to an economy what blood is to a body, so it must flow. When the money stops flowing, the effect is like a cardiac arrest, and the economy is in dead waters. To keep the money circulating, those with a surplus must lend it to those with a deficit, and the interest rate should be where the supply and demand for money are equal. When the interest rate reaches zero, lenders stop lending because the return is not worth the risk. They wait for interest rates to rise. Money ends up on the sidelines, leading to a cardiac arrest that can entail an economic depression.


It happened during the Great Depression. Had interest rates been lower, the markets for money and capital could have remained operational. We had seen negative interest rates in Europe for nearly a decade. They could have gone lower had there been a holding fee on cash, or, even better, a negative interest rate low enough to prevent people from hoarding it. Once interest rates can go lower, a usury-free global financial system may become possible. It gives rise to several questions. Is it possible? Under which circumstances? What are the benefits and the drawbacks? What are the implications for individuals, businesses and governments? And how does it affect the financial system?

There is no alternative

Several monetary reform proposals do not view the financial system as a system, which it is, and that isn’t hard to guess because the term ‘financial system’ already implies this. You can’t attach the wings of a Boeing to an Airbus and expect the thing to fly. The financial system is complex, with numerous relationships that many existing reform proposals overlook. For instance, if you shut down the central bank without further measures, the economy will crash, even if it is flying smoothly. And that isn’t even hard to find out.

Also, private currencies are a troublesome idea. The payment system is a key public interest, so governments and central banks stand behind it. Most banks are private corporations driven by profit. They take risks that might bring down the economy. And so, governments and central banks make regulations and oversee the banks. And banks create money, from which they profit, and we all pay for it via inflation. That is not good, but replacing the system with something worse is worse, like the word ‘worse’ implies.

Finally, Natural Money itself comes with serious consequences, most notably, credit not being as readily available as it is now. Charging interest on money and loans is the root cause of many dysfunctions in the financial system, so it is usury for good reason, but rooting out usury leads to restrictions. Yet, a sound reform proposal acknowledges that the financial system is complex, with intricate relationships that interact with one another. And so, we have to be aware of the consequences. There is no free lunch here.

The theory of Natural Money encompasses a systems approach to identify the relevant relationships within the financial system and the consequences of altering them. It is a comprehensive design that focuses on the whole. As the tale about the fictional island Barataria makes abundantly clear, seemingly minor oversights can have enormous consequences. It would be a grave error to pick only the elements you like. That design will never fly. Nor would an Airbus take off with Boeing wings. You either buy Airbus or Boeing, not some hybrid of both.

A focus on the whole comes at the expense of detail. Natural Money is an outline for a global usury-free financial system. There is no prototype, let alone one that has proven to fly. Local currencies with a holding charge exist, so the project is like envisioning a jet aeroplane just after the Wright brothers had proven that planes can fly. Natural Money is a leap into the unknown, and if prototypes crash, that doesn’t prove that we can’t do it. Natural Money comes with constraints. Credit will not be as abundantly available as it is today. Still, the theory is sound, and there might be no alternative.

Latest revision: 1 November 2025

Featured image: Wörgl bank notes with stamps

1. The Future Of Money. Bernard Lietaer (2002). Cornerstone / Cornerstone Ras.
2. The Natural Economic Order. Silvio Gesell (1918).
3. A Free Money Miracle? Jonathan Goodwin (2013). Mises.org.

Dark Side

Trade and finance

Capitalism has lifted billions out of poverty, but sadly, there is a price to be paid. Welcome to the dark side. Trade and finance, thus the profit motive, power the system we live in. And that will eventually end humanity. Worse yet, we are almost done. Most notably in the past, ordinary people regarded merchants and bankers with suspicion. In popular culture, trade and banking were the domains of people of questionable ethics. It is hard to pin down the issue, but they do not only bring the good things in life. Everywhere you see the death and destruction they cause. The ethic of the merchant is profit, nothing else. We think we can’t do without trade and finance, but can we do without moral values? The distinction between trade and crime is elusive. When governments fight the drug trade, they intervene in the market for opioids and prevent businesspeople from doing business.

Hermes, the Greek god of trade, was also the god of thieves. Like thieves, traders don’t like to toil and produce something. They live off other people’s work. That is a caricature. Trade can be useful. Competition can be tough. And we can’t live without trade anymore, because we buy everything we need in the market, yet also many things we don’t need. Still, as the number of unnecessary products and services increases, trade proliferates. The pace at which we transform energy and resources into waste and pollution hastens as traders facilitate a competition, so we end up supporting an ever-expanding class of traders with our labour. The alternative is to produce all we can locally and accept a lower standard of living. That was also Mahatma Gandhi’s advice.

Jesus Christ chased the money changers from the temple. Yet, in The Parable of the Talents, he said that you must put your talent to work. Talents were money, so it could mean putting your money to work. And Jesus never said anything about usury. Yet, Muhammad did. Jesus further said that it is easier for a camel to go through the eye of a needle than for a rich man to enter the kingdom of God. You can take your pick and pimp your argument with Jesus’ words. Was Jesus a socialist or a capitalist?

It is silly to think in such terms. Jesus lived 2,000 years ago, when economics as a field didn’t exist. Someone claiming to be Paul added that the love of money is the root of all sorts of evil. The Jewish writer Jesus Sirach noted, ‘A merchant can hardly avoid doing wrong. Every salesman is guilty of sin.’ Sirach made a few other peculiar remarks, like, ‘A man’s wickedness is better than a woman’s goodness. Women bring shame and disgrace.’ And so, you’d better take his ‘wisdom’ with loads of salt.

Humans chasing money is indeed a most terrible force. Eliminating it might require drastic measures that few people have the stomach for. The Taliban are among the exceptions. You get the idea. You will only do that if the disease is worse than the cure. The prohibition in the United States led to increased crime, as did the relaxed drug law enforcement in the Netherlands. Markets have no morals, and the ethic of the merchant is no ethics at all. The individual businessperson may have moral values and refrain from a trade, but merchants as a group never do. Traditional moral systems accept that you should be able to make a living, but they hold that greed is wrong. We have gone a long way since then. Today, we see trade as mutually beneficial, so we believe that those who engage in a trade do so voluntarily because they all benefit, or believe they do.

The pursuit of wealth, regardless of the consequences, became not only the foundation of our economic system but also of our morality. And so, Friedrich Hayek could write, ‘The disdain for profit is due to ignorance and to an attitude that we may, if we wish, admire in the ascetic who has chosen to be content with a small share of the riches of this world, but which, when actualised in the form of restrictions on others, is selfish to the extent that it imposes asceticism, and indeed deprivations of all sorts, on others.’ Our ethic is that we can do as we please, as if consequences don’t exist. And the ascetic is selfish when he says everyone should live like him. It is moral depravity at its finest. And so, what was once good has become evil, and what was once evil has become good.

Economists would even argue that someone who is altruistic maximises personal utility, so that altruism becomes a selfish act. And the ascetic tries to maximise his personal utility by attempting to force others to live as he does. An economist can’t imagine that we would do something good for its own sake. The problem is not self-interest as such, but greed or the merchant’s ethic, and the difference isn’t clear. In any case, we have a suicidal appreciation of wealth. Had we looked down on riches and luxury and aspired to have just enough and do with less, this world could be a much better place.

Many merchants are people like you and me without evil intent. Shop owners make a living by providing their customers with a service. They are often people who care, not the greedy, evil kind that run Wall Street or sell weapons to warring factions in Africa. Still, something is profoundly wrong with trade. Individual merchants may have ethical values, but markets never have them. And trade drives the creative destruction that will ultimately destroy us. Yet, suppressing trade promotes illicit markets and crime. And so, we accept the drawbacks, thinking the alternatives are worse. And that is a fatal mistake.

A pragmatic approach is that outcomes matter more than intent. If the result of evil intent, such as greed, is good, it is good. And if the outcome of good intent is terrible, it is wrong or perhaps even evil. If factory owners destroy artisans’ businesses and pay their employees low wages, but overall opulence increases as clothing becomes cheaper, then it is good. Likewise, if a country switches to socialism out of good intentions, but the population starves, it is evil. Before the Industrial Revolution, nearly everyone was as miserable as today’s poorest. Capitalism has lifted billions out of poverty. So why bother?

Trade and finance became the engine of growth, bringing industrialisation, modernisation, colonisation, the slave trade, mass migration, the loss of livelihoods for craftspeople, and the depopulation of the countryside. Various movements, such as socialists, anti-globalists, religious groups, small-is-beautiful, environmentalists, and also the Nazis, attempted to provide alternatives to the current order with their visions of Paradise. They all failed. The system is a brute force driven by our sentiments and urges. As consumers, we crave the best service at the lowest price, and as investors, we desire corporations to increase their profits. And we don’t think about the consequences.

Usury: the destroyer of civilisations

Money is to the economy what blood is to the body. It must flow. Otherwise, the economy will die. If we stop buying stuff, businesses go bankrupt, we become unemployed, the government receives no taxes, and everything comes to a standstill. That doesn’t happen because we keep spending on necessities like food and clothing. When we buy less, the economy slows, and a recession ensues; if it gets worse, a depression- the ultimate economic nightmare that policymakers desperately try to prevent. If that happens, businesses go bankrupt, and people become unemployed and depressed. Usually, the economy recovers, but it may take time. To prevent that misery, we must keep buying more stuff or pay more for the same, to make the economy grow.

Money must flow, so those who have more than they need must bring it back into circulation. If they don’t spend, they must lend it out. And they will do so only if they receive a reward in the form of interest. The scheme of usury is that those who are short of money borrow it from those who have more than they need, and pay for it, so that they will be even more short of money, while those who have more than they need get even more. For some reason that mathematicians can explain, that usually doesn’t end well. Finance can get complicated because traders in financial markets make it complex with their get-rich-without-working schemes, but usury makes much of it possible.

In the past, when borrowers couldn’t repay their debts, they became the serfs of the moneylenders. It is why several ancient civilisations had regular debt cancellations and why religions like Christianity and Islam forbade interest on money or debts. Usury is the practice of paying for the use of money, which is profoundly evil. The evil of it lies in the circular flows. We all need a medium of exchange. A simple explanation helps to clarify the issue. Imagine the Duckburg economy running on 100 silver coins. With these 100 coins, everyone has enough money, and the Duckburg economy operates smoothly. Scrooge McDuck owns ten, but he is a miser and doesn’t use them to buy items from others.

The circular flows of Duckburg now suffer a 10-coin shortfall. Products remain unsold, and several ducks lose their jobs. To prevent that, Scrooge McDuck can lend these silver coins for one year at 10% interest to ducks who come short, so the money keeps flowing. At the end of the year, the economy is 11 short. Scrooge McDuck then lends 11 coins at 10% interest. In this way, he will own all the coins after 25 years. Scrooge McDuck can implode the Duckburg economy by storing the money in his vault. When the citizens of Duckburg become desperate, Scrooge McDuck can buy their homes, let them pay rent, and become even richer. If you think that is smart, you have the ethics of a merchant.

Barataria: an economic fairy tale

It is not easy to step out as the system hooks on our inner drives, such as the desire for comfort and riches. The alternatives couldn’t compete. It is not that they couldn’t provide for us. A few people step out or go off grid, but it is like a rehab from a consumption addiction. It is a sober life while everyone around you keeps on living the good life. After Us Is the Deluge is the prevailing mood among consumers. But what are our options anyway? In the early 1990s, the Strohalm Foundation published The Miracle Island Barataria, an economic parable by the Argentinian-German economist Silvio Gesell.1 I rewrote the narrative to better highlight its message. Gesell explores three options: (1) communism or socialism, (2) private property and markets without traders and bankers, and (3) a fully capitalist economy.

As the story goes, in 1612, a few hundred Spanish families landed on Barataria, an island in the Atlantic, after their ships had sunk. No one searched for them, and they became an isolated community. They worked together to build houses, shared their harvests, and held meetings to decide on matters that concerned everyone. It was democracy and communism. After ten years, the teacher, Diego Martinez, called everyone into a meeting. The previous year, several crops had remained unsown, while a part of the harvest had been rotting in the fields. As they were on the brink of famine, something had to change. Martinez noted that working together and sharing had helped them build their community, but the islanders had become lazy.

They came to work late, took long breaks, and left early. They spent their time at meetings discussing what to do, but much work remained undone. ‘If someone has a good idea, he must propose it in a meeting to people who don’t understand it. We discuss it, but we usually don’t agree or we don’t do what we agree to. Nothing gets done anymore. We could do better if we had the right to the fruits of our labour and take responsibility for our actions,’ Martinez said. He added, ‘The strawberry beds suffered damage because no one had covered them against night frost.’ He mentioned several other examples. Martinez said, ‘If the strawberries are yours, you protect them. And if you have a plan you think is worthwhile and you can keep the earnings, you do it yourself and hire people to help you.’

He proposed splitting the land into parcels and renting them to the highest bidder to finance public expenses. Fertile lands would fetch a higher price than barren ones, giving everyone an equal opportunity to make a living. He also proposed introducing home and tool ownership to make the islanders feel responsible for them. But with property and having the right to the fruits of your efforts, you need a medium of exchange or money. The islanders decided to use potatoes as money. Everyone needed potatoes. They had value, so they were good money.

Potatoes are bulky, thus difficult to carry, and they rot. At the next meeting, Santiago Barabino proposed establishing a storehouse for the potatoes and issuing paper money that could be exchanged for potatoes when needed. So, you had banknotes of 1, 2, 5, and 10 pounds, and 10 pounds of potatoes. The Baratarians agreed. The notes had an issue date and gradually lost their value due to storage costs and rot. If you returned the banknote to the potato storage after a year, you received 10% less than you had paid for it. And because the issue date was on the banknote, buyers and sellers knew its value.

For several years, Barataria issued banknotes backed by stored potatoes. Their value declined over time to cover storage costs and the cost of rot. Borrowers didn’t pay interest. If you had savings, you would lend them to trustworthy villagers, provided they agreed to return notes of the same weight. The notes lost value, prompting everyone to spend their money and to store food in their storehouses. As a side benefit, there was still enough food in case of a harvest failure. The islanders did well. There were no poor or rich people. There were no merchants buying goods at low prices to sell them at high prices. And no one paid interest. Things were cheap in Barataria. The chronicle notes that the islanders acted as good Christians and helped each other.

Then Carlos Marquez had a new idea. He addressed the Baratarians, ‘How many losses do housewives suffer from keeping food in their cellars? We shouldn’t put our savings in perishable products, but use money that has a stable value. We can back our money with something we don’t need and doesn’t deteriorate. The Pinus Moneta is a nut we can’t eat, and doesn’t rot,’ he said, ‘We don’t have to back money with a commodity of value like potatoes. The things we buy and sell give the money its value. If we do that, we can buy things when we need them and don’t have to store them ourselves.’

What a great convenience that would be. It seemed too good to be true. Diego Martinez argued against the proposal. He told his fellow islanders that a medium of exchange passes from hand to hand. It remains in circulation. But savings stay where they are unless those who are short of money borrow them and pay interest. You end up paying interest to use the currency you need to buy the things you need. His argument was to no avail. And that is the price of democracy. People decide about questions they don’t understand. And no one knows the future, so what seems a good idea often has unexpected consequences.

And if you are doing well, you can’t imagine that seemingly insignificant errors can ruin you. Marquez spoke passionately, while Martinez warned cautiously, saying things were fine as they were and he couldn’t foresee the consequences. That swayed opinions. The islanders switched to money backed by the Pinus Moneta. This money didn’t lose its value. That made it attractive to save money. Suddenly, everyone tried to exchange their supplies for the Pinus Moneta, causing mayhem in the marketplace. Everyone brought everything they had to the market. But no one could sell their goods as everyone wanted money.

The company Barabino & Co. came up with a cunning plan that didn’t require a tail to be called a weasel. Barabino & Co. set up a bank with accounts that Baratarians could use to save and make payments. Everyone could bring their money to the bank and receive an extra 10% after a year. The naive Baratarians agreed. They could have known there weren’t enough Pinus Moneta nuts to pay the interest. And they didn’t ask themselves how Barabino & Co. would generate the profits to pay that interest. With borrowed money, Barabino & Co. bought goods from the islanders and deposited the funds into their accounts, but they purchased only food and seeds.

The following spring, Barabino & Co. hiked food and seed prices. Most islanders paid more for food and seeds than they received in interest. They went into debt with Barabino & Co. With the profit, Barabino & Co. bought the next harvest and cranked up food prices even further. Soon, Barabino & Co. owned everything. Most were in debt and worked hard, but a few wealthy people lived off interest income. They didn’t work and lived a life of luxury on the interest on their accounts. The Baratarians needed money to pay for the items they bought from Barabino & Co. They had to borrow this money from Barabino & Co. and pay interest to use it. There weren’t enough nuts to repay all the loans with interest, so the islanders went further into debt year after year. They paid interest on money the bank created out of thin air, giving it to the wealthy.

The Baratarians worked harder and grew more creative in making money, only to find themselves deeper in debt every year. That is how usury works. There was no money to pay the interest, so the debtors borrowed more. The islanders invented, produced, and sold more products, most notably wooden items made from the island’s trees. Not everyone could keep up, and more people lived in sheds, eating scraps. At least, the economy grew, and the Baratarians grew accustomed to luxuries they hadn’t had before. They had wooden chairs, boxes, ornaments, toys, outhouses, carts and tables.

The change came with other unfavourable consequences. The Baratarians became agitated, deceitful, and immoral. Crime rose as everyone desired the luxuries the rich enjoyed, which they didn’t have to work for. Of their Christian faith, not much remained except an empty shell. They were busy making money. Then came the day the Baratarians had cut down all the trees on the island. They suddenly lacked the wood needed to make the tools for harvesting their crops, and they starved. That was the day the Pinus Moneta lost its value. After all, you can’t eat money.

Adam Smith and the Wealth of Nations

In the original tale, the Baratarian economy didn’t collapse, but the British rediscovered the island and found a class society much like their own. What the story has wrong is that trade doesn’t make things more expensive, but cheaper. Yet, that comes at a price. The revised story tells how devious acts contributed to an outcome most of us now deem desirable. By subjecting ourselves to this system of trade and usury, most of us live far more comfortably than people in the Middle Ages. By saving and investing, capitalists build their capital. Capitalism is about making present sacrifices by saving to have more in the future through investing. It promotes competition via innovation and economies of scale. But there is no ultimate goal, no vision of Paradise, only creative destruction without end.

The Baratarians were in debt, worked hard and were ingenious in finding new ways to transform scarce resources into money. The competition was tough. Those who couldn’t keep up became homeless. As there was never enough money to repay the principal with interest, the Baratarians went deeper into debt, worked even harder, and became more creative by inventing and selling new products, generating an economic boom that ended in starvation once the trees were gone. We face a similar problem. The Earth’s resources are finite. Money becomes worthless once there is nothing left to buy or sell.

Adam Smith, the founder of modern capitalist thought, claimed that pursuing our private interests promotes the public good. A baker doesn’t bake bread to serve the community but to make a living. It is why we have something to eat. The baker doesn’t want to lose customers, so he bakes what they desire. Otherwise, they go to his competitor. Smith believed it would work out well, as humans are moral creatures. We temper our behaviour to avoid harm to others. That is why moral relativists might argue that we don’t need a public interest. The private interest will do just fine. Yet, it is not how markets operate. Individuals may have ethical values, but markets never have them. As the least scrupulous usually win the competition, things are gradually growing more evil.

Factory owners didn’t consider the plight of the artisans they put out of business or the miserable working conditions their workers endured. And they often couldn’t, as the competition was tough. They would have gone out of business if they had done so. Moral considerations don’t drive business decisions. Without self-interest and trade, we would be poorer, and poverty was Smith’s primary concern. Increasing production was the way out. Self-interest and trade were the tools to achieve that. And it succeeded marvellously. Since the Industrial Revolution, increases in production have lifted billions of people out of poverty. When Smith lived, the Industrial Revolution hadn’t started yet. No one could foresee how it would end. Smith argued:

  • The division of labour drives increases in production. If you specialise in a trade, you can do a better job or produce more at a lower cost.
  • A market’s size limits the division of labour. Transport costs limit market sizes. Energy costs drive the volume and distance of trade.
  • Merchants preferred precious metals as money. It enabled them to store their gains, allowing them to wait for opportunities to profit.

Producers produce items at different times and in other locations, and in quantities that consumers do not need. That is why we trade. Traders bridge those gaps by storing, transporting, and dividing goods. Trade promotes large-scale production and labour efficiency, so fewer people are needed to provide for our necessities. That allows for more fanciful products, services, and industries, thus a higher standard of living, but we don’t need most of these products and services, and producing them takes energy and resources. Adam Smith already guessed what the division of labour and the convenience of organised society would do to humans when he wrote,

The man whose whole life is spent in performing a few simple operations, the effects of which are perhaps always the same, or very nearly the same, has no occasion to exert his understanding or to exercise his invention in finding expedients for removing difficulties that never occur. He naturally loses, therefore, the habit of such exertion, and generally becomes as stupid and ignorant as it is possible for a human creature to become.

Evil empire of trade and usury

Economic and financial power translate into military power. The Europeans didn’t finance their conquests with taxes as previous conquerors did, but with profits from their colonial enterprises. No one likes paying taxes, but everyone loves making a profit. The scheme thus became an unprecedented success. Venture capitalists funded the first ships, hoping to find new trade routes and riches. And they found them. The Europeans reinvested their profits, allowing their capital to grow and their financial and military strength to increase.

After the bourgeoisie took control of the British government during the Glorious Revolution, the British state became a venture of the propertied class, much like the Dutch Republic. The Netherlands was an oligarchic republic run by merchants, the most successful and wealthiest nation at the time, and was organised like the earlier republic of Venice. The British imported knowledge of Dutch governance by appointing a Dutch governor as their king. In the following centuries, Great Britain became the world’s largest empire.

Contrary to the Dutch, who had a minimal state and relied on private armies, the British bourgeoisie benefited from a functioning state and was willing to pay for it. The propaganda storyline became that taxation became legitimate because it had the consent of the taxed. The British bourgeoisie didn’t like to pay for corruption or ineptitude, so the state’s performance improved.3 With its secure and expanded tax base, the clampdown on corruption and ineptitude, and the invention of modern banking, trust in British financial markets improved, and Great Britain could borrow more at lower interest rates.

It helped Great Britain defeat France, which had twice the wealth and twice the population. In France, the wealthy didn’t pay taxes, and the government was always short of funding. France defaulted on its debts several times. The French government was inept and corrupt, which made lenders reluctant to lend to it. The British economic successes led them to build an extensive colonial empire, creating a large market, low interest rates, and high wages, which helped ignite the Industrial Revolution.

During the Napoleonic age, several European countries modernised their governments, establishing bureaucracies with career paths based on qualifications and merit. The British also later modernised their administration, aligning it more closely with the rational principles of government adopted by other European countries after the French Revolution.4 The benefits of the division of labour imply it is better to let bureaucrats run bureaucracies and businesspeople run businesses. You don’t let government bureaucrats run a business, nor do you allow your businesspeople to run the government.

The United States followed a different path. The Founding Fathers established the new state based on the most modern principles of their time. In doing so, they were ahead of their European counterparts. There were regular elections for the president and parliament, and a separation of powers among the executive, legislative, and judicial branches. Later, the US also became the first democracy.4 Several European countries later followed suit, but by then, their states had become professional bureaucracies.


The US administration, however, didn’t become a fully modern professional bureaucracy, so it remained plagued by corruption, cronyism, and unqualified appointees. Politicians gave their supporters government offices after winning an election.4 In 1881, a disgruntled campaigner for US President Garfield who had sought a diplomatic job as compensation shot the president. Appointing people for political reasons had become uncommon in much of Western Europe as professional bureaucracies rely on qualified people. Modernisation efforts in the US began in the 1880s, took decades, and never fully succeeded.

The Founding Fathers established the United States as an oligarchic republic ruled by the propertied classes, similar to Great Britain and the Dutch Republic. Rather than relying on a clean government like the British elites, they relied on political corruption to get things done, for instance, via campaign financing, bribing judges, and funding think tanks that advise the US government. After World War II, the United States emerged as a superpower, and the gold-backed US dollar became the currency used in international trade. To finance its military, the US began running deficits in the 1960s and ended the convertibility of the US dollar into gold in 1971. The US dollar then became the de facto reserve currency, most notably because oil-exporting countries accepted it.

The US dollar’s reserve-currency status enabled US elites to utilise the productive capacity of the rest of the world to sustain their empire. Foreign countries delivered goods and labour in exchange for US dollars, which the United States printed out of thin air. Americans had relatively low taxes and high deficits because foreign countries financed the extravagant lifestyles of wealthy Americans, even as many people remained poor.

The US financial elites at institutions such as the World Bank and the IMF pushed developing countries into US-dollar debt, making them dependent on exports to sustain the US empire. As a result, many industries in the United States began to suffer from the Dutch Disease, with demand for the US dollar driving up its price. The US dollar has become an international store of value, and so has US government debt. As a result, deficits have escalated further, and the American economy depends on controlling the world’s financial markets. The American empire became an evil empire of trade and usury, but the end of that empire will not necessarily make things better.

Latest revision: 11 November 2026

Featured image: cover of The Miracle Island Barataria

1. Het wondereiland Barataria. Silvio Gesell (1922).
2. 1 in 5 business leaders may have psychopathic tendencies—here’s why, according to a psychology professor. Tomas Chamorro-Premuzic (2019). CNBC.
3. The Origins of Political Order: From Prehuman Times to the French Revolution. Francis Fukuyama (2011).
4. Political Order And Political Decay. Francis Fukuyama (2015).

Deutsche Bank Towers in Frankfurt am Main

What Is the Use of banks?

Turning debt into money

The previous episode about money discussed some imaginary trades between you, a hatter, a lawyer, a barber and a fisherman. It is shown that if people promise to pay this might suffice for payment. So if the fisherman promises you to pay next week for the hat you just made, you could say to the lawyer that you expect the fisherman to pay in a week, and ask her if you can pay in a week too. The lawyer could then ask the same of the barber and the barber could ask the same of the fisherman. If all these debts cancel out then no cash is needed.

In most cases, debts cannot be cancelled out so easily. A hat may cost € 50, legal advice € 60, a hairdo € 30, and the fish € 20. If you are the hatter, you could lend € 10 to the barber and the lawyer could lend € 20 to the fisherman. Perhaps the lawyer doesn’t trust the fisherman because he smells fishy. But if the lawyer trusts the barber and the barber trusts the fisherman then the lawyer could lend € 20 to the barber and the barber could lend € 20 to the fisherman.

That could become complicated quite easily. And this is where banks come in. Banks can lend money because they know the financial situation of their customers. The fisherman can borrow money from his bank to make payments because the bank knows that he has an unstable but good income and a vessel that can be sold for cash if needed.

If the fisherman borrows money to pay for the hat you made, this money ends up in your account. You can use it to pay the lawyer. And so the fisherman’s debt becomes the lawyer’s money until she uses it to pay the barber. People that have a deposit lend money to the bank and the bank is lending this money to those who have a loan, in this case, the fisherman. Depositors trust the bank even though they do not know the people the bank is lending money to.

Most people think of money as coins and banknotes but more than 90% of the money just exists as bookkeeping entries in banks. When a fisherman borrows money from his bank, he can spend it on a hat. This means that the bank creates money and that this money is debt. Most of our money is debt so the value of money depends on the belief that debtors pay back their debts. This seems scary and it keeps quite a few people awake at night.

Some people argue that debts and banking are frauds because they are based on a belief. But banks and debts help to boost trade and production by creating money that doesn’t exist to start businesses that don’t yet exist to make products which will be bought by the people those businesses will hire with this newly created money. Banking and debts are the basis of the capitalist economy.

Banking as bookkeeping

Banking is more or less just bookkeeping and balance sheets. Balance sheets can be used to explain the magic trick banks do, which is creating money. Balance sheets are simple. There are no intimidating formulas, only additions and subtractions. The important thing to remember with balance sheets is that the total of the amounts on the left side must always equal those on the right side.

On the left is the value of your stuff and your money. On the right side is the value of your debts. Your net worth is what remains when you sell all your stuff and pay off your debts. It is on the right side too in order to make it equal to the left side. Your net worth can be a negative value. If that is the case, you might be bankrupt because you can’t repay your debts by selling your assets. The left side is named debit and the right side is called credit. Your balance sheet might look like this:

debit
 
credit
 
house
€ 100,000
mortgage
€ 80,000
other stuff
€ 50,000
other loans
€ 30,000
cash, bank deposits
€ 20,000
your net worth
€ 60,000
total
€ 170,000
total
€ 170,000

When you buy a car, you own more stuff, but also another loan or fewer bank deposits as you have to pay for the car. This is because debit always equals credit. When you drive the car, it goes down in value, as does your net worth, because debit always equals credit. If your salary comes in, your bank deposits as well as your net worth rise because debit always equals credit. If you pay down a loan, the amount in your bank account, as well as the amount of your loan, goes down because debit always equals credit. If debit doesn’t equal credit then you have made a calculation error.

Also for a bank, the total of the amounts on the left side must always equal those on the right side, so that debit always equals credit. Your debt is on the debit side of the bank’s balance sheet. You have borrowed this money from your bank. The bank owns this loan. Your bank deposits are on the credit side of the bank’s balance sheet. The loans of the bank are paid for by deposits. Banks lend money to each other. This may happen when you make a payment to someone who has a bank account at another bank. Your bank may borrow this money from the other bank until another payment comes the other way. The balance sheet of a bank may look like this:

debit
 
credit
 
mortgages and loans
€ 70,000,000
deposits
€ 60,000,000
loans to other banks
€ 10,000,000
deposits from other banks
€ 20,000,000
cash, central bank deposits
€ 10,000,000
the bank’s net worth
€ 10,000,000
total
€ 90,000,000
total
€ 90,000,000

How banks create money

Banks create money. How do they do that? It is easy if you understand balance sheets. Assume that you, the hatter, the lawyer, the barber, and the fisherman all have € 10 in cash. Together you decide to start a bank. You all bring in the € 10 you own so that you all have a deposit of € 10 and the bank has € 40 in cash. The bank allows everyone to withdraw deposits in cash. This is no problem as long as the total of deposits equals the total amount of cash. After everyone has put in the deposit, the bank’s balance sheet looks as follows:

debit
 
credit
 
cash
€ 40
your deposit
€ 10
  
deposit lawyer
€ 10
  
deposit barber
€ 10
  
deposit fisherman
€ 10
total
€ 40
total
€ 40

First, there was only € 40 in cash. Now there are € 40 in bank deposits too. You might think that the bank created money. Only, that isn’t true because the depositors can’t spend the cash unless they take out their deposits. In other words, the depositors don’t have more money at their disposal than before. If you look at the total, there is still € 40. This is bookkeeping. You have to write down the total twice as debit must equal credit.

But now things are going to get a bit wild. The fisherman comes to you and he wants to buy a hat. The hat costs € 50 but the fisherman has only € 10 in his account. To make the sale possible, the bank is going to do its magic. The fisherman calls the bank and asks if he can borrow some money. The bank grants him a loan of € 40 and puts the money in his deposit account so that he can spend it. And look:

debit
 
credit
 
cash
€ 40
your deposit
€ 10
loan fisherman
€ 40
deposit lawyer
€ 10
  
deposit barber
€ 10
  
deposit fisherman
€ 50
total
€ 80
total
€ 80

Who says that miracles can’t happen? The deposits miraculously increased from € 40 to € 80 so € 40 is created from thin air. There is still only € 40 in cash but the fisherman’s debt created new money. This is how banks create money. And that is only because bank deposits are money. This is all there is to it. So much for the mystery. The fisherman then pays € 50 for the hat. And so it becomes your money:

debit
 
credit
 
cash
€ 40
your deposit
€ 60
loan fisherman
€ 40
deposit lawyer
€ 10
  
deposit barber
€ 10
  
deposit fisherman
€ 0
total
€ 80
total
€ 80

And now comes the dreadful part that keeps some people fretting. Everyone can take out his or her deposits in cash. There are € 80 in deposits and only € 40 in cash. If you go to the bank and demand your € 60 in cash, the bank would go bankrupt, even when the fisherman pays off his loan the next day. You could bankrupt the bank by buying € 50 in fish with cash. If you go to the bank to get € 50 in cash it would not be there so the bank would go bankrupt before the fisherman can pay off his loan with the same cash.

A bank could get into trouble in this way even when debtors repay their debts. Clever minds already figured out a solution. Central banks can print money too. If the European Central Bank (ECB) prints € 20 on a piece of paper and lends this money to the bank, there would be enough cash to pay out your deposit. Banning the use of cash and only using bank deposits for payments would be another option. So, after the ECB deposited € 20 in cash, the bank’s balance sheet might look like this:

debit
 
credit
 
cash
€ 60
your deposit
€ 60
loan fisherman
€ 40
deposit lawyer
€ 10
  
deposit barber
€ 10
  
deposit fisherman
€ 0
  
deposit ECB
€ 20
total
€ 100
total
€ 100

After you pay the fisherman, he can pay off his loan, and the bank will have enough cash to pay out all deposits. The bank can repay the central bank and everything is fine and dandy again. In this case the bank could not meet the demand for cash but the value of cash and loans wasn’t smaller than the deposits (the bank’s debt). After the fisherman pays back his loan and the bank pays back the ECB, the bank’s balance sheet might look like this:

debit
 
credit
 
cash
€ 40
your deposit
€ 10
loan fisherman
€ 0
deposit lawyer
€ 10
  
deposit barber
€ 10
  
deposit fisherman
€ 10
  
deposit ECB
€ 0
total
€ 40
total
€ 40

If banks can’t create money, trade would be difficult. If the hat is € 50, the legal advice € 60, the hairdo € 30, and the fish € 20, and you, the lawyer, the barber and the fisherman all have only € 10, nothing can be bought or sold. If the bank lends € 40 to the fisherman, he can buy a hat from you, you can buy legal advice from the lawyer, the lawyer can buy a hairdo and the barber can buy fish. Debt is the basis of the capitalist economy. Nearly all money is debt, and without debt, the economy would come to a standstill.

How much money can banks create?

The amount of money a bank can create is limited by the bank’s capital, which is the bank’s net worth. Regulations stipulate that banks should have a minimum amount of capital. This is the capital requirement. If the capital requirement is 10%, and the bank’s capital is € 10,000,000, it can lend € 100,000,000, provided that there are enough deposits. If the bank makes a loan, a new deposit is created. If the deposit leaves the bank, the bank must borrow it back from another bank or cut back its lending. That is because debit must always equal credit.

debit
 
credit
 
mortgages and loans
€ 70,000,000
deposits
€ 60,000,000
loans to other banks
€ 10,000,000
deposits from other banks
€ 20,000,000
cash, central bank deposits
€ 10,000,000
the bank’s net worth
€ 10,000,000
total
€ 90,000,000
total
€ 90,000,000

When a deposit leaves the bank, it ends up at another bank. The other bank can use it for lending, provided that it has sufficient capital. There may be a reserve requirement, which is a minimum of cash and central bank deposits the bank must hold. If the reserve requirement is 10%, the bank can lend out as much as ten times the amount of cash and central bank reserves it has available. In the past, reserve requirements were important as people often used cash and could go to the bank to demand their deposits in cash. For that reason banks needed to hold a certain amount of cash.

Featured image: Deutsche Bank building CC BY-SA 4.0. Raimond Spekking. Wikimedia Commons. Public Domain.

Coin hoard

What Is Money?

Why do we have money?

Money was invented because trade would be difficult without it. For example, if you are a hatter in need of legal advice, then without money, you have to find a lawyer who craves a hat. That is unlikely to happen. Maybe there is a fisherman dreaming of a hat, but he can’t give you legal advice. Maybe there is a lawyer in need of a hairdo instead of a hat. With money, all these problems disappear like magic. You can buy the services of the lawyer so that she can go to the barber. After that, the barber can buy some fish so that the fisherman can buy a hat from you.

Despite these mind-blowing advantages humans didn’t need money for a long time because they lived in small bands and villages where everyone depended on each other and everyone helped each other. This meant, for example, that when a fisherman needed a hat, you would make a hat for him, and if you needed anything, someone else would provide it to you. You did someone a favour so that he or she was obliged to do something back. Villagers produced most of what they needed themselves. Trade with the outside world was limited and was done with barter.

Uses of money

Later cities, kingdoms and empires emerged. People living in cities, kingdoms and empires didn’t know each other so it became difficult to track whether or not everyone was contributing. Favours and obligations didn’t suffice. They were replaced by a formal system for making payments and tracking contributions and obligations. Commerce and tax collection needed a means of payment as well as administration. It is therefore not a coincidence that writing and money were invented around the same time in the same area. The earliest writings were bookkeeping entries. Money has the following uses:

  • buying and selling stuff (payment) so money is a medium of exchange
  • saying how much something is worth, so money is a unit of account
  • keeping track of contributions and obligations (saving and borrowing) so money is a store of value.
catdog
Nickelodeon character CatDog

Money being a medium of exchange as well as a store of value is like your pet being a cat as well as a dog. The result is not really a success. The parts of the pet may often quarrel, for example, because the dog part wants to play while the cat part wants to sleep. If someone keeps some money for a rainy day and does not spend it, others cannot use this money for buying stuff. And this can be a problem. A simple example can explain this.

Imagine that everyone decides to save all his or her money. Nothing would be bought or sold anymore. All businesses would go bankrupt and everybody would be unemployed. All the money that has been saved would buy nothing because there isn’t anything to buy anymore. This is a total economic collapse.

In reality, it doesn’t get that bad as people always spend on basic necessities like tablets and mobile phones, and perhaps food. When people only spend money on necessities there is an economic depression, which is not as bad as a total economic collapse but still very bad. Saving can make you poorer, but only when there are too many savings already. Savings are used to invest in businesses and hire workers to make products and services. Only if there are more savings than investments, does money remain unused.

The value of money

Money has no value when there isn’t any stuff to buy or when there aren’t any other people to trade with. Imagine that you get the offer to be dropped alone on a remote and uninhabited island in the Pacific with 10 million euros. Probably you would decline the deal, even if you can keep your mobile phone. It is other people and stuff that give money its value. But how? The answer is remarkably simple. The value of money is just a belief.

People are willing to work for money and sell their stuff for money. And because others do this, you do the same. For example, you may think that euro notes have an appalling design as well as an unpleasant odour, but nevertheless, you desire to own them because other people want them too. The euro’s value is based on the belief that other people accept euros for payment.

This is just a belief as the following example demonstrates. Suppose that you wake up one day to hear on the news that the European Union has been dissolved overnight. Suddenly you may have second thoughts about your precious stockpile of foul-smelling unstylishly decorated euro banknotes.

You may ask yourself in distress whether or not your precious bank notes still have any value. What is the value of the euro without the European Union? You may find yourself hurrying to the nearest phone shop in an effort to exchange this pile of banknotes for the latest model mobile phone.

And to prove this point even further, suppose that the phone shop gladly accepts your euros. Suddenly they become desirable again and you may start to have second thoughts about that latest model you are about to buy. It may not remain hip for much longer, so you may change your mind again and prefer to keep your precious euros because there may be a newer model next month. So, because the shop wants your euros, you wants them too.

Types of money

At first, money was an item that people needed or desired. Grain was one of the earliest forms of money. Everybody needed food so it was easy to make people believe that others accept grain for payment. In prison camps during World War II cigarettes became money because they were in high demand. Even non-smokers accepted them because they knew that other people desired them very badly. For that reason, cocaine can be money too.

Wares like grain, cigarettes and cocaine have disadvantages. They degrade over time so they aren’t a very good store of value. This makes them a great medium of exchange because people won’t save them. An example can demonstrate this. Imagine that apples are money and you want to buy a house. A house costs 120,000 apples but your monthly salary is just 2,500 apples of which you can save 1,000. It takes 10 years of saving to buy a house. Soon you will discover that apples rot and that you will never be able to buy a house. Then you will spend all your apples right away.

Saving is difficult with apples. This is where gold and silver come in. Gold and silver do have not much use, but humans were always attracted to shiny stuff. Gold is rare so a small amount of gold can have a lot of value because some people feel a strong desire for shiny stuff. Gold and silver coins can be made of different sizes and purity so that they are suitable for payment and can be used as a unit of account.

More importantly, gold and silver do not deteriorate in quality like apples, grain or cigarettes. They do not even rust after 1,000 years. This makes gold and silver an excellent store of value. But this should make us suspicious. A perfect cat makes a lousy dog so a perfect store of value can fail the test for being a good medium of exchange. People can store gold and silver so that there is less money available for buying and selling stuff. And this can cause an economic depression as we have seen.

Governments create money too, for example by printing “10 euro” on a piece of paper. Governments require by law that this money should be used for payments and taxes. This makes people believe that others accept this money too. Government money is called fiat currency or simply currency. The authority of a government is limited to the area it controls so in the past government currencies had little value outside the country itself unless this money consisted of coins containing gold or silver.

In fact, another reason why gold and silver are attractive as money is that the value of gold and silver does not depend on the authority of a government. This made gold and silver internationally accepted as money. In the 19th century, most government currencies could be exchanged for a fixed amount of gold. This is the gold standard. The gold standard boosted trade because gold was internationally accepted as money.

Most money is debt

Debts can have value and so debts can be money too. This may seem strange or even outrageous, but money is just a belief. For example, money is the belief that you can exchange a hat for money and then exchange this money for legal advice. Hence, if you believe that the debtor is going to pay, you can accept his or her promise to pay as payment. And if others believe this too, you can use this promise to pay someone else.

So if the fisherman promises you to pay next week for the hat you just made, you could say to the lawyer that you expect the fisherman to pay in a week, and ask her if you can pay in a week too. The lawyer could then ask the same of the barber and the barber could ask the same of the fisherman. If all debts cancel out then there is no need for cash. Most of the money we currently use is debt. In most cases, debts don’t cancel out and there are many more people involved so it would be complicated to keep track of all debts and savings. That is where banks come in.

Featured image: Close up of coin hoard CC BY-SA 2.0. Portable Antiquities Scheme from London, England (2010). Wikimedia Commons.

Other images: Nickelodeon character CatDog, Sméagol character from The Lord of the Rings [copyright info]