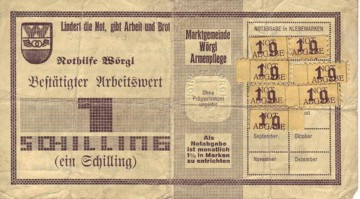
Wörgl bank note with stamps. Public Domain.

Complementary Currencies

Collapse of complex societies

In today’s globalised economy, imports and exports account for 40-60% of most nations’ GDP, so nearly every country has integrated into the world economy. That may change if the world economy collapses. A possible cause is a sudden loss of confidence in the US dollar, which is the world’s reserve and trade currency. A collapse of the world economy may trigger a reduction in complexity, commonly referred to as the collapse of world civilisation. Such a scenario is plausible, so it is prudent to plan for it. Perhaps, we can rebuild our civilisation with local initiatives. Usually, a collapse is involuntary. Things fall apart, not because we want to, but because we can’t afford our lifestyles anymore.

In his book ‘The Collapse of Complex Societies,’ Joseph Tainter argues that collapse is a sudden loss of complexity, and that collapses occur because the cost of complexity outstrips its benefits, leaving us better off with simpler lives. If you can’t afford food, life can be better without mortgages, taxes, medical bills, tuition, and most other things you buy, if it means you have something to eat. It is not that housing, government, education, and businesses have no use. After all, complexity solves problems. We could do with less, accept life as it is, and lead agreeable lives without social media and new treatments for cancer. It may seem disagreeable, but the Amish are content with such a lifestyle.

If we simplify the organisation of society, communities and families take on a greater role at the expense of markets and states. Village life in the past was far from ideal. Abusive parents could often do as they pleased and get away with it. And if you were gay, you had better not tell. Today, the idea of community has changed. You can set up a community with like-minded people. And there has been some progress in how much diversity people accept. Simplification means that states and markets retreat, even though the degree to which they will is unknown at present. Ideally, self-sufficiency and widely agreed-upon moral values will fill the void, while we will not return to the dark ages.

Perhaps we can learn to live in harmony with one another and with nature. That requires us to break free from the stranglehold of usury and trade. Local money enabled Wörgl to achieve some economic independence by keeping the money circulating within the local economy and encouraging townspeople to buy local products. When you use regular money, such as the euro, you can buy on international markets. If you do, the money will leave the community and may end up anywhere. You don’t know what your money will do there. It might facilitate drug trades or child labour. If you don’t care, don’t expect the market to, because the market is like a psychopath that might come for you.

Breaking free from markets

Thousands of local and regional vouchers circulate, but few were as successful as the Wörgl scrip. One notable exception was the Red Global de Clubes de Trueque (Global Network of Barter Clubs) during the Argentine Great Depression of 1998-2002. It was an even more spectacular success. The network emerged from local initiatives following the collapse of the Argentine banking system, enabling millions to exchange goods and services using local vouchers called créditos. Argentinians lacked a reliable medium of exchange, so barter clubs, which had initially been a lifeline for the unemployed, eventually helped middle-class people, many businesses, and some factories.

You can see the role of usury and international trade and finance in these crises. In Wörgl, a holding fee on money brought the local economy back to life, indicating that the global economy required negative interest rates, which were impossible in a usury-based financial system. To maintain a stable currency for their payments, the Argentinians could have borrowed US dollars in global markets. Due to Argentina’s creditworthiness, it could only do so at a high interest rate, which would have further eroded the country’s finances. The Argentinians would have used these US dollars to purchase foreign goods on international markets, leaving them without a means of payment again soon.

Had Argentina been a closed economy that had bartered with the outside world, the crisis wouldn’t have materialised. That is only hard to carry out. Traders would smuggle marketable goods in and out of the country. Only a few totalitarian regimes, like Nazi Germany and North Korea, have succeeded in doing this. These aren’t agreeable places. Still, it explains why these barter clubs were so successful. And it partly explains the economic miracle of Nazi Germany. The Argentinians participating in the barter clubs had nothing to offer to international markets. Or, they supported the clubs to help their communities and were willing to forego better deals available in global markets.

Limitations

Amid a worsening depression, the Wörgl economy improved, and unemployment dropped. Wörgl achieved this by breaking free from the usury financial system and world markets. The Argentinian network of barter clubs also did. And there lies a significant issue. Modern economies utilise goods and services that require a scale that only larger markets or global initiatives can provide. One of them is finance. It is probably impossible to develop financial markets for local scrip, let alone make them usury-free. The options for spreading risks in small markets are limited. The day you can go to the bank to get a mortgage in local scrip may never come.

The local initiatives were also successful because of an emergency. There was no reliable medium of exchange. The Argentinian barter vouchers weren’t legal tender and had no backing of a national currency. Millions of people joined the network, but it declined after 2001. The network had no organised structure. There were thousands of barter clubs in the network, each with its own notes. The clubs accepted each other’s vouchers, so some clubs committed fraud by printing additional vouchers. The Argentinian economy recovered in 2002, so the need for the barter clubs also diminished.

Whether the local or regional money is a currency or a voucher depends on the setup. An exchangeable government currency inspires trust. Most initiatives issue vouchers, but some have a currency reserve backing them. Most are private, and the money is hardly ever legal tender. Typically, these initiatives have a specific goal, such as strengthening the local community or economy. The money issued by the Austrian town of Wörgl was as close to a currency as local money can get. A government issued it, accepted it for tax payments, and guaranteed the exchange rate with the regular currency.

The Wörgl scrip and the Argentinian barter clubs demonstrate that local currencies and vouchers can succeed in times of crisis when the circular money flows have collapsed, either due to deflation (leading people to hoard money) or inflation (making the country’s currency worthless). It is also possible to integrate these local economies into a larger economy through these monetary exchanges. However, when the economy is doing well and the circular flows are functioning, the role of these monies becomes marginal. And so, they complement the regular financial system and are complementary currencies.

If you can receive internationally accepted currency, such as euros, you prefer it to barter vouchers because it inspires more trust. In times of crisis, you may be willing to take less trustworthy money if that is the only one available. It will be impossible to have a global network of local vouchers. Money operates in a hierarchy of trust. Exchangeability in a regular currency makes them more trustworthy. Imagine that there are 1,000,000 barter clubs issuing vouchers worldwide. How can you know that a note is genuine, and, if so, that the club issuing it is not scamming the system? And so, a voucher or currency can best only circulate in the area where everyone knows it.

Credit means trust, and as a Dutch proverb says, trust comes on foot and leaves on horseback. It is hard to build, but easy to lose. There are always individuals trying to scam the system. The human desire to live off the work of others is eternal. It is the foundation of capitalism, as it is what investors seek to do. And people try to use the government for their gain by demanding benefits, favourable regulations, or lower taxes. It is also a reason why trade and usury exist, not the only one, of course, but it is good to keep this in mind. The Greek god of the merchants was also the god of the thieves. It is a cynical view, as most people are honest, but systems of trust are as strong as their weakest link.

A local economy typically offers fewer choices and often poorer-quality products than international markets. You may accept these drawbacks to support your local community, since the best deal in the market may not be the best deal for your village or country. Walmart might be cheaper and offer a wider variety of choices, but buying at Walmart comes at the expense of local stores, factories, and suppliers, so that if you buy at Walmart, your sister or neighbour ends up unemployed and must move to the city to find a telesales job in the bullshit economy.

Making it work

Imagine that everyone does something helpful rather than wasting energy and resources in the bullshit economy, that no one is on the dole, and that people with limited abilities contribute what they can. Imagine that we respect nature and that the economy is sustainable. That might be possible after ending the stranglehold of usury and markets. In that case, we may work only twenty hours per week, have enough to live on, and can do as we please for the remainder of our time. Okay, we can’t visit Disney World, watch Formula 1, or ruin the planet with other senseless, wasteful activities, so we must entertain ourselves with other things, like playing football or singing in a choir. For the rest, we may have to rely on a trustworthy friend named Boredom to pass our time.

The ground is hard
The time is long
Life plods along
Its leaden way
There’s work to do
There’s time for play
But mostly, there’s
A lot of boredom

Yet, viewed from
The other side—
The little village
In the rigid land,
A sanctuary
Wrapped in snow—
It brings to mind
A different age

Drs. P, Winterdorp

Since 1934, Switzerland has been home to a business-to-business barter cooperative, WIR, which issues credit, the WIR franc backed by assets the members have pledged in collateral. Businesses trade goods and services without using cash, allowing them to work with less financial capital, clear excess inventory, and build new business relationships. Today, the WIR, like any other banking cooperative, looks like a traditional bank. That is mainly due to market pressures. A cooperative must offer a competitive product and deal with credit risk. Otherwise, cooperative members are often better off in the market. The United States has several barter organisations with varying credibility. Most are for-profit, so serving a community is not their primary objective.

Another scheme that can strengthen the local community is the Farmer-Citizens Initiative, also known as the Pergola Association. The market for agricultural produce is competitive, subjecting farmers to international finance and global markets. That is why immigrants often take these jobs and work long hours for low wages. Farmer-citizens’ initiatives have varying setups. Usually, citizens pay a subscription fee to cover the farm’s expenses in exchange for a share of the produce. It enables farms to diversify and offer a broader range of food products. Rather than exploiting immigrants, farmers may hire local workers to do chores at fair wages. The transactions can be in local scrip.

That might seem impossible, but community economics can be highly efficient because in ‘advanced’ economies, 75% of the people may now work in bullshit jobs. In contrast, in ‘developing’ economies, many live in slums wasting their time or doing bullshit jobs that pay little. People who produce the things we need keep them alive, either by buying unnecessary products and services or paying taxes. Things could be better if there were no IT specialists, salespeople, lawyers, actresses, financial advisors, and, most notably, traders, as they organise the competition that makes it hard to earn a living wage doing essential jobs at a reasonable pace.

Trade drives the inefficiency. When we don’t have to pay for people occupying themselves with bullshit, and more people can do the work, living sustainably comes within reach. Working the land and other essential jobs will then require shorter working weeks and bring acceptable, even though not higher, wages. After all, the standard of living will be lower because we won’t buy non-essential items. If working twenty hours per week on average is enough, and it might be, we will have plenty of time to pursue more gratifying activities. That is what Paradise might look like. It is not realistic to have a world without trade, but trade is the core problem that we face.

Government support can help. The municipality of Wörgl accepted its currency for tax payments. Complementary currencies are not a recent invention. Accepting a currency as payment for taxes, or even requiring payment in that currency, has been a way for governments to generate demand for it, allowing them to issue currency without backing it with precious metals. In England, tally-stick money circulated within the country, as it had value only there, allowing local state money to coexist alongside the merchant’s money, gold coin, insulating the nation’s economy from the whims of international trade.

In a Natural Money financial system, local governments, such as municipalities, can issue local and regional currencies backed by national currencies or by the global reserve currency (GRC), which is a debt of national governments or the world government in the International Currency Unit (ICU). In a more decentralised world with a uniform law system, nation-states aren’t the highest authority. They, however, issue debts in the ICU, so there can be national currencies based on these debts. Municipalities can issue debts in the ICU. Using them as backing for local currencies makes it challenging to maintain parity with the national currency. And so, full backing is essential.

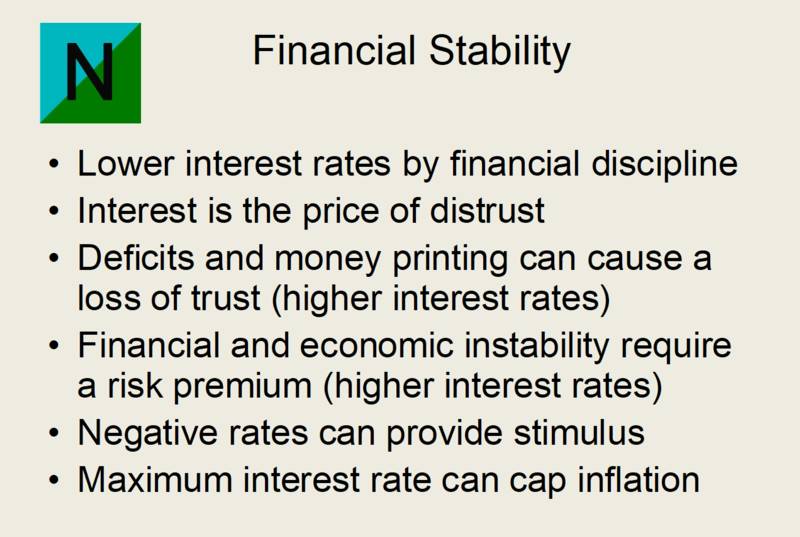
To end usury and enable lending, you need not only trust but also efficient financial markets. Interest rates below zero can only exist when lenders expect repayment and the currency to have a stable value. In a small community, there are few lenders and borrowers, resulting in limited options. Raising capital for a new business or a mortgage in a local currency is probably impossible. And if a single business fails, a small bank can get into trouble. In larger financial markets, banks can diversify their investments.

Local monies are complementary, supplementing the regular financial system rather than replacing it. Preferably, their value stays on par with the regular currency. Only a full backing, as in Wörgl, can guarantee that. Small-scale lending and borrowing in these currencies, based on personal trust, are possible. It is not feasible to develop financial markets in them. Still, in a future where communities become increasingly self-sufficient, complementary currencies will play a more significant role than they do today.

To make it work, we should have motives beyond securing the best deal or maximising profit. So far, these other motives haven’t moved mountains. That is because only faith can. Money gives us a false sense of security. It promises us that we can buy anything we want, at any time we want. But money is not a basement full of foodstuffs or safety on the streets. Once we have ruined this planet and society falls apart, we will find out. Still, we put our faith in money. If it is not the euro, we put our faith in gold and silver rather than our communities. That is because trade and usury destroy them.

Requirements for a post-apocalyptic economy

As we could be heading for an economic apocalypse, it is a good idea to prepare, develop a vision of what the future world civilisation should look like, and see whether we can make it a reality. Without a vision to guide us, we will remain clueless victims of circumstances. Complementary currencies likely play a larger role in the future world economy than they do today. The solution needs to be global, meaning that no country can opt out. A global community-centred usury-free economy will probably need:

  • A global social contract guaranteeing a fundamental equality of all humans. The ecological footprint divides us into givers and takers.
  • A greater role of communities and families in the political economy, and a reduction of the role of markets and states.
  • A modest lifestyle and accepting life as it is to live sustainably within the planet’s limits. We are not individuals, but an integral part of creation.
  • An honest society with social trust and motives other than wealth and profit driving decisions. That also requires dealing with those who don’t fit in.
  • Local governments administering and supporting complementary currencies by providing an exchange for them.
  • Local initiatives, such as barter clubs and farmer-citizen initiatives utilising community currencies to strengthen the local economy.
  • Discouraging long-distance trade with tariffs. Banning the use of harmful products, or taxing them, for instance, in the case of fossil fuels.
  • People helping each other as the consequences of the shift will be enormous due to the massive imbalances in the global economy.
  • An equal right to means of existence for everyone, which will require land reform and people migrating in search of a living.
  • Limiting the right to property to our needs and what is functional in society. Existing property rights can’t stand in the way of what we must do.

Land reform may be required, but having competent farmers working the land is even more crucial. Some land reforms have failed because they were political projects that took no heed of the issue. And so the greatest caution is advised, as ill-conceived plans or poor execution may result in famines. At least in theory, everyone has the same right to land, and existing property rights shouldn’t be an obstacle. A computer system for administering complementary currencies already exists. The Dutch non-profit STRO (formerly the Strohalm Foundation) has developed Cyclos, the most widely used system for this purpose and, likely, the best. Their experience can help us to restart the world economy with local and regional initiatives on short notice.

Latest revision: 3 November 2026

Featured image: Wörgl bank note with stamps. Public Domain.
Wörgl bank note with stamps. Public Domain.
Short Introduction

End of growth

The last 200 years have been an era of exceptional economic growth, unlike anything the world has ever seen. As with any exponential phenomenon in a limited space, the growth of human economic activities will end in one way or another. An innovation drive fuels economic growth. Economists call it creative destruction. We are now reaching the point where humans will be no match for artificial intelligence, and humanity is about to be creatively destroyed in the process. If humanity is to survive, and I have worked with that hypothetical scenario in mind, it will have implications for financial markets. And we have limited resources. If we halt innovation, we can be sure this will remain the case. For most of history, people had barely enough. Today, there is a massive excess in the bullshit economy, transforming energy and resources into waste and pollution to make money for investors by producing and marketing non-essential products and services.

For most of history, economic growth has been negligible. However, it averaged 1.5% over the last two centuries. It will soon return to zero, or possibly lower, in the hypothetical scenario that seems to require a miracle. Miracles are outside the scope of finance and economics, so also outside the scope of this treatise. It has implications for returns on investments, the financial system and interest rates. Investors have become hooked on positive returns. Without growth, investors lose confidence, which may cause collapse because the economy runs on credit, and credit means trust. And so, it is grow or die. Before modern times, humans managed to live without economic growth because there was hardly any capital or interest-bearing debt. Past civilisations facing usury-induced economic collapses either disappeared, banned interest, or instituted debt cancellations.

Indeed, the past 200 years have been an exceptional phase in human history. And because we don’t live that long, we think growth is normal. Low interest rates were essential for prosperity. Efficient financial markets promoted growth by depressing interest rates, thereby making the Industrial Revolution profitable. Low interest rates have brought unprecedented wealth, albeit at the expense of the planet and future generations. That doesn’t sound all good. Yet, after growth has ended, low interest rates remain key to prosperity, even when it is making the most of what we have. The benefit of low interest rates is an enduring rule that doesn’t depend on temporary economic conditions. Even more so, when economic growth returns to sustainable levels, so close to zero, there is no growth to pay interest from, so that we will either have to end lending or end usury. Luckily, a usury-free financial system already exists: Natural Money.

The nature of usury

Suppose Jesus’ mother, as a lady of great foresight, had opened a retirement account for Jesus shortly after his birth in 1 AD at the Bank of the Money Changers next to the Temple in Jerusalem. Suppose further that she had put a small gold coin weighing three grammes in Jesus’ retirement account at 4% interest. Jesus never retired, but he promised to return. Suppose now that the bank held the money for this eventuality. How much gold would there be in the account in the year 2020? It would be an amount of gold weighing 12 million times Earth’s mass. There isn’t enough gold to pay out Jesus if he returns.

And so the usurers hope he doesn’t come back, also for other reasons, of course. For every lending, there is borrowing. The bank is merely an intermediary. And so, there must be people in debt for an amount of gold weighing twelve million times the mass of the Earth. That would never happen. The scheme would have collapsed long before that, and the debtors would have become the serfs of the moneylenders. That is why religions like Christianity and Islam forbade charging interest on money or debts.

Yet, the usurers, those sneaky goatlike creatures, have found a way around the issue. Our money isn’t gold anymore. Banks create money from thin air, so the nature of usury has changed. When you go to a bank and take out a loan, such as a car loan, you receive a deposit in exchange for a debt, which the bank creates on the spot through two bookkeeping entries. This magic is commonly referred to as creating money. You keep the debt, but the deposit becomes someone else’s money once you purchase the car. When you repay the loan, the deposit and the debt vanish into thin air. You must repay the loan with interest. If the interest rate is 5% and you have borrowed €100 for a year, you must return €105. Something doesn’t add up there.

Nearly all the money we use is created from loans that borrowers must repay with interest. If our borrowing creates money, and we repay our debts with interest, then we may do so by borrowing the interest. That is also what happens in reality, and that is why debt levels continue to rise. So, where does the extra €5 come from? Here are the options:

  • Borrowers borrow more.
  • Depositors spend some of their balance.
  • Borrowers fail to repay their loans.
  • The government borrows more.
  • The central bank prints the money.

Problems arise when borrowers don’t take on more debt and depositors don’t spend their money. In that case, borrowers as a group are short of funds, and some of them are unable to repay their loans. If too many borrowers can’t pay at once, a financial crisis occurs. To prevent that from happening, the government borrows more, and the central bank prints money. They bring that money into the economy, allowing debtors to pay off their debts with interest. Interest compounds to infinity, and there is no limit to human imagination, so frivolous accounting schemes like usury can go a long way before they collapse. But eventually, they collapse. And others may attribute it to different causes. It is possible to have responsible lending at interest. And so, it is pointless to argue.

Necessity of interest

We take interest for granted, and economists believe that we need it. Without lending and borrowing, a modern capitalist economy would have been impossible. And without interest, making loans would be impossible. Money is to the economy what blood is to the body. If lending and borrowing halt, money stops flowing, and the economy comes to a standstill. That is akin to a cardiac arrest. If left untreated, it brings about the economy’s funeral. That is why the financial press reads the lips of central bankers as if our lives depend on it. They manage the flow. Lenders have reasons to demand interest. These are:

  • When you lend out money, you can’t use it yourself. That is inconvenient. And so, you expect compensation for the use of your money.
  • The borrower may not repay the loan, so you desire compensation for that risk.
  • You can invest your money and earn a return. To lenders, the interest rate must be attractive relative to other investments.

That has been the case for a long time, and economists have gradually become quite good at explaining the past. Since then, we have seen financial innovations and are now facing the end of growth. Changes in the economy and the economic system may lead to the end of interest on money and debts. These are:

  • You can use the money in a bank account at any time. You can use the money you have lent as if it were cash. And a debit card is more convenient than cash.
  • Banks spread their risks, central banks help out banks when needed, and governments guarantee bank deposits, so bank deposits are as safe as cash.
  • There is a global savings glut. There are ample savings and limited investment options, which can make negative interest rates attractive for lending.

Negative interest rates are possible. In the late 2010s and early 2020s, the proof came when most of Europe entered negative interest-rate territory. The ECB was unable to set interest rates below -0.5%. Had it set interest rates even lower, account holders would have emptied their bank accounts and stuffed their mattresses with banknotes to avoid paying interest on their deposits, disrupting the circular flows.

As interest rates couldn’t go lower, the ECB took extraordinary measures, flooding the banking system with new money to boost the economy. Had there been a holding fee on cash, interest rates could have gone lower, and there would have been no need to print money. It has happened before. The Austrian town of Wörgl charged a holding fee on banknotes during the Great Depression, which led to an economic miracle by encouraging existing banknotes to circulate more freely rather than printing new money. Ancient Egypt had a similar payment system for over a thousand years under the Pharaohs.

Miracle of Wörgl

In the midst of the Great Depression, the Austrian town of Wörgl was in dire straits and prepared to try anything. Of its 4,500 residents, 1,500 were jobless, and 200 families were penniless. Mayor Michael Unterguggenberger had a list of projects he wanted to accomplish, but there wasn’t enough money to fund them all. These projects included paving roads, installing street lights, extending water distribution throughout the town, and planting trees along the streets.1

Rather than spending the remaining 32,000 Austrian Schilling in the town’s coffers to start these projects, he deposited them in a local savings bank as a guarantee to back the issue of a currency known as stamp scrip. A crucial feature of this money was the holding fee. The Wörgl money required a monthly stamp on circulating notes to keep them valid, at 1% of the note’s value. The German-Argentine businessman Silvio Gesell had first proposed this idea in his book The Natural Economic Order.2

Nobody wanted to pay for the monthly stamps, so everyone spent the notes they received. The 32,000 schilling deposit allowed anyone to exchange scrip for 98 per cent of its value in schillings. Few did this because the scrip was worth one Austrian schilling after buying a new stamp. But the townspeople didn’t keep more scrip than they needed. Only 5,000 schillings circulated. The stamp fees paid for a soup kitchen that fed 220 families.1

The municipality carried out the works, including the construction of houses, a reservoir, a ski jump, and a bridge. The key to this success was the circulation of scrip money within the local economy. It circulated fourteen times as often as the schilling. It increased trade and employment. Unemployment in Wörgl decreased while it rose in the rest of Austria. Six neighbouring villages successfully copied the idea. The French Prime Minister, Édouard Daladier, visited the town to witness the ‘miracle of Wörgl’ himself.1

In January 1933, the neighbouring city of Kitzbühel copied the idea. In June 1933, Mayor Unterguggenberger addressed a meeting with representatives from 170 Austrian towns and villages. Two hundred Austrian townships were interested in introducing scrip money. At this point, the central bank decided to ban scrip money.1 The depression returned, and in 1938, the Austrians turned to Hitler, as they voted to join Germany.

Since then, several local scrip monies have circulated, but none has been as successful as the one in Wörgl. In Wörgl, the payment of taxes in arrears generated additional revenue for the town council, which it then spent on public projects. Once the townspeople had paid their taxes, they would have fewer spending options and might have exchanged their scrip for schillings to avoid paying for the stamps. Once all the taxes in arrears had been paid, the economic boost would have petered out. That never happened because the central bank had halted the project prematurely.

The economy of Wörgl also did well because the holding fee kept the existing money circulating. A negative interest rate encourages people to spend their money, eliminating the need to borrow and keeping the money circulating in the economy. It demonstrated that the economy performed better under negative interest rates. A holding fee makes negative interest rates possible, as lenders do not have to pay it after lending the money. The one who holds the money pays the charge. That can make lending money at an interest rate of -2% to a reliable borrower more attractive than paying 12% for the stamps.

Joseph in Egypt

In the time of the Pharaohs, the Egyptian state operated granaries for over 1,500 years. Wheat and barley were the primary food sources in Egypt. Whenever farmers brought their harvest to one of the granaries, state officials issued them receipts stating the amount of grain they had brought in. Egyptians held accounts at the granaries. They transferred grain to others as payment or withdrew grain after paying the storage cost.

The Egyptians thus used grain stored in their granaries for making payments. Everyone needed to eat, so grain stored in the granaries had value.1 Due to storage costs, the money gradually lost its value. With this kind of money, interest-free loans might be possible. If you save grain money, you pay for storage. And so, lending the money interest-free to a trustworthy borrower can be attractive. There is no evidence that this happened.

The origin of these granaries remains unclear. Probably, the state collected a portion of the harvests as taxes and stored them in its facilities. The government storage proved convenient for farmers, as it relieved them of the work of storing and selling their produce. And it made sense to have a public grain reserve in case of harvest failures.

The Bible includes a story claiming that a Jewish man named Joseph built these granaries. As the story goes, a Pharaoh once had a few dreams that his advisers couldn’t explain. He dreamed about seven lean cows eating seven fat cows and seven thin, blasted ears of grain devouring seven full ears of grain. Joseph explained those dreams to the Pharaoh. He told the Pharaoh that seven years of good harvests would follow, followed by seven years of crop failures. Joseph advised the Egyptians to store food for hard times. They followed his advice and built grain storehouses. In this way, Egypt managed to survive the seven years of scarcity that followed.

The grain money gradually lost value due to storage costs. It works like buying stamps to keep the money valid, like in Wörgl. Both are holding fees. The difference is that you don’t have to buy stamps to keep the money valid. Instead, the granary officials netted the charge with the principal when someone made a payment or exchanged a voucher for grain. The grain money circulated for over 1,500 years until the Romans conquered Egypt around 40 BC. It didn’t end in a debt crisis, which suggests that a holding fee on money or negative interest rates can create a stable financial system that lasts forever.

Storing food makes sense today, even when it costs money. Harvests may become more unpredictable due to global warming and intensive farming. We have enough food in storage to feed humanity for only a few months, as storing more is unprofitable. Food storage ties up capital, so there is an interest cost. But you can’t eat money, so storing food to deal with harvest failures is as sensible now as it was in the time of the Pharaohs. It reveals the foolishness of our money-centred thinking. We only survive if it is financially viable. Imagine how that will play out once artificial intelligence and robots do a better job than we do at a lower cost.

Natural Money

The miracle of Wörgl suggests that national currencies with holding fees could have ended the Great Depression. A myth circulating in the interest-free currency movement is that had the Austrian central bank not banned the experiment, the idea would have spread, the Great Depression would have ended, Hitler wouldn’t have come to power, and World War II wouldn’t have happened. That is a tad imaginative, to say the least, but a holding fee could have allowed for negative interest rates, and they could have prevented the Great Depression from starting in the first place.

And such money can last. The grain money in ancient Egypt provided a stable financial system for over 1,000 years. The grain backing provided financial discipline. The holding fee prevented money hoarding that could have impeded the flow of money. The money, however, didn’t promote interest-free lending, so the Egyptian state regulated interest-bearing lending to prevent debt slavery. Egyptian wisdom literature condemned greed and exploitative lending, encouraging empathy for vulnerable individuals.

A holding fee of 10-12% per year punishes cash users. If the interest rate on bank accounts is -2%, a -3% interest rate on cash is sufficient to prevent people from withdrawing their money from the bank. That becomes possible once cash is a separate currency backed by government debt, on which the interest rate on short-term government debt applies. Banknotes and coins can be separate from the administrative currency. So, if the interest rate on the cash currency is -3%, one cash euro will be worth 0.97 administrative euros after one year. And now, we have a definition of Natural Money:

  • Cash is a separate currency backed by short-term government debt and has the negative interest rate of short-term government debt.
  • Natural Money administrative currencies carry a holding fee of 10-12% per year, allowing for negative interest rates.
  • Loans, including bank loans, have negative interest rates. Zero is the maximum interest rate on debts.

Consequences

Natural Money doesn’t fundamentally alter the nature of bank lending. Banks borrow from depositors at a lower rate to lend it at a higher rate. With Natural Money, banks may offer deposit interest rates of -2% and lend at 0% instead of borrowing at 2% to lend at 4%. A maximum interest rate of zero, however, has a profound impact on lending volume, as it severely constrains it, most notably speculative lending and usurious consumer credit, and it favours equity financing over borrowing in business. The strict lending requirements affect business loans, leading to deleveraging.

Businesses still need to attract capital. To address the issue, Natural Money distinguishes between regular banks and investment banks. Regular banks can guarantee promised returns and have government backing because the payment system is a public service. Investment banks invest in businesses and take risks. They are comparable to Islamic banks. Investment banks don’t guarantee returns. Depositors take on risk to earn higher returns, but they might incur losses or temporarily lose access to their deposits.

While the maximum interest rate restricts lending, the holding fee provides a stimulus, thereby stabilising the financial system. When the economy slows, interest rates decrease, and more money becomes available for lending as risk appetite increases, making zero-interest lending more attractive. Conversely, if the economy booms, interest rates increase, and the maximum interest rate curtails lending. Consequently, central banks don’t need to set interest rates and manage the money supply, and governments don’t need to manage aggregate demand with their spending.

Reasons to do research

Stamp scrip and other kinds of emergency money have helped communities during times of economic hardship. The economic miracle of Wörgl during the Great Depression of the 1930s, however, was exceptional. The payment of local taxes inflated the impact of the money. Many townspeople had been late on their taxes, but once the economy recovered, they had the money to pay them. Some even paid their taxes in advance to avoid paying the holding fee. It generated additional revenues for the town, which it could spend on the projects. It provided a boost that would have petered out once the villagers had paid their taxes.3 It was not a miracle. It was too good to be true. However, there is more to it, which makes the idea worth researching.

Once interest rates reach zero, the markets for money and capital cease to function, as interest rates can’t go lower. Money is to an economy what blood is to a body, so it must flow. When the money stops flowing, the effect is like a cardiac arrest, and the economy is in dead waters. To keep the money circulating, those with a surplus must lend it to those with a deficit, and the interest rate should be where the supply and demand for money are equal. When the interest rate reaches zero, lenders stop lending because the return is not worth the risk. They wait for interest rates to rise. Money ends up on the sidelines, leading to a cardiac arrest that can entail an economic depression.


It happened during the Great Depression. Had interest rates been lower, the markets for money and capital could have remained operational. We had seen negative interest rates in Europe for nearly a decade. They could have gone lower had there been a holding fee on cash, or, even better, a negative interest rate low enough to prevent people from hoarding it. Once interest rates can go lower, a usury-free global financial system may become possible. It gives rise to several questions. Is it possible? Under which circumstances? What are the benefits and the drawbacks? What are the implications for individuals, businesses and governments? And how does it affect the financial system?

There is no alternative

Several monetary reform proposals do not view the financial system as a system, which it is, and that isn’t hard to guess because the term ‘financial system’ already implies this. You can’t attach the wings of a Boeing to an Airbus and expect the thing to fly. The financial system is complex, with numerous relationships that many existing reform proposals overlook. For instance, if you shut down the central bank without further measures, the economy will crash, even if it is flying smoothly. And that isn’t even hard to find out.

Also, private currencies are a troublesome idea. The payment system is a key public interest, so governments and central banks stand behind it. Most banks are private corporations driven by profit. They take risks that might bring down the economy. And so, governments and central banks make regulations and oversee the banks. And banks create money, from which they profit, and we all pay for it via inflation. That is not good, but replacing the system with something worse is worse, like the word ‘worse’ implies.

Finally, Natural Money itself comes with serious consequences, most notably, credit not being as readily available as it is now. Charging interest on money and loans is the root cause of many dysfunctions in the financial system, so it is usury for good reason, but rooting out usury leads to restrictions. Yet, a sound reform proposal acknowledges that the financial system is complex, with intricate relationships that interact with one another. And so, we have to be aware of the consequences. There is no free lunch here.

The theory of Natural Money encompasses a systems approach to identify the relevant relationships within the financial system and the consequences of altering them. It is a comprehensive design that focuses on the whole. As the tale about the fictional island Barataria makes abundantly clear, seemingly minor oversights can have enormous consequences. It would be a grave error to pick only the elements you like. That design will never fly. Nor would an Airbus take off with Boeing wings. You either buy Airbus or Boeing, not some hybrid of both.

A focus on the whole comes at the expense of detail. Natural Money is an outline for a global usury-free financial system. There is no prototype, let alone one that has proven to fly. Local currencies with a holding charge exist, so the project is like envisioning a jet aeroplane just after the Wright brothers had proven that planes can fly. Natural Money is a leap into the unknown, and if prototypes crash, that doesn’t prove that we can’t do it. Natural Money comes with constraints. Credit will not be as abundantly available as it is today. Still, the theory is sound, and there might be no alternative.

Latest revision: 1 November 2025

Featured image: Wörgl bank notes with stamps

1. The Future Of Money. Bernard Lietaer (2002). Cornerstone / Cornerstone Ras.
2. The Natural Economic Order. Silvio Gesell (1918).
3. A Free Money Miracle? Jonathan Goodwin (2013). Mises.org.

Ara Economicus

Banking Operations

Commercial versus savings banks

Historically, the banking sector comprised several types of banks with different characteristics. The distinction between commercial banks, which create money, and savings banks, which don’t, has lost its relevance due to the existence of efficient financial markets, in which banks resolve mismatches between the terms of loans and deposits by borrowing and lending. The distinction between created money and savings is arbitrary, as the following example demonstrates. Now, this is practical philosophy, so that you know. Suppose I work at a farm, and the farmer rewards me with a plot of land and leftover wood and materials from a defunct shed, which I use to build a home. After finishing my house, I go to the bank and take out a mortgage. The bank creates that money out of thin air.

Yet, until I went to the bank to let it do its magic, no money had changed hands. Still, I saved for a home. In other words, savings aren’t the same as money in a savings account. In this case, my home is my savings, and if the mortgage is a debt, the money I take out is my savings. To further illustrate the point, suppose that I have no money and also own no home. When I go to the bank for a car loan, it creates the money on the spot. If you think there are no savings, you are wrong once again. The person who sold you the car had savings consisting of that car, unless that vehicle had been bought with borrowed money. I can even borrow money and put it in a savings account. I created ‘savings’ by borrowing money and lending it to the bank. In this case, I haven’t saved.

That would have been a rather frivolous philosophical exercise into the definition of savings, but it is crucial to understand what savings are, for many alternative monetary reform proposals go wrong precisely on that point.

Full-reserve banking

A well-known monetary reform proposal is full-reserve banking, as outlined in the Chicago Plan, which means there are only savings banks, with no commercial banks creating money. It often resurfaces when banks go bankrupt. Under full-reserve banking, banks can’t lend out funds deposited in demand or current accounts. Money in these accounts isn’t debt but backed by central bank currency or cash. And depositors can’t withdraw the money from their savings accounts on short notice. In this way, banks can’t go bankrupt because depositors demand cash. With full reserve banking, loans must come from savings, which are funds that depositors can’t withdraw on demand, as they have entrusted them to the bank for an extended period.

Lack of cash is usually not the primary reason banks fail. Rather, it is loan write-offs. That was also the case during the 2008 financial crisis. Full-reserve banking addresses a liquidity problem, whereas the crisis was a solvency issue that subsequently led to a liquidity problem. Banks ran into trouble, not because they lacked cash, but because they incurred losses on their loans. As a result, banks began to distrust one another and stopped lending to each other. The financial system can be safe with zero reserve banking, provided that banks are solvent, thus have sufficient capital, and own adequate liquid assets, such as government bonds, that they can sell to meet withdrawals. And so, a reserve requirement can better include liquid safe assets, such as government bonds, rather than currency alone.

Some proponents of full-reserve banking are socialists who oppose privately controlled money creation, viewing it as a public subsidy to the private banking sector. Others desire a banking sector free from government interference, so a ‘free’ banking market without central bank interventions and deposit guarantees. At least that is something socialists and their free-market opponents might agree on. Bank credit can contribute to economic cycles and financial crises. With full reserve banking, there would be less bank credit, and interest rates would be higher. To enable lending, depositors must part with their money for a designated period, making it available for lending. As a result, fewer funds are available for lending, and interest rates would be higher.

Shadow banks

Full-reserve banking makes financial markets less efficient, allowing alternative schemes, such as shadow banks, to fill the gap. An example can illustrate that. Suppose that God has ordered banks to use only money in savings accounts for lending, so that there is full-reserve banking in Paradise. Eve and Adam only do business with each other. Both have €100 in their current account, which they use for their daily business transactions. This money is suitable for payment because it is in the current account. For that reason, they don’t receive interest. Assume now that the bank also offers savings accounts with an interest rate of 4%, but money in savings accounts isn’t suitable for payment.

Then a financial advisor comes along, disguised as a snake, advising Eve and Adam, for a reasonable fee, on how to manage their payments between themselves and deposit their money into a savings account. So, what you now read in Genesis is made up by bankers to hide their fraud, a conspiracy theorist might infer. But it is just a story. In this way, Eve and Adam both earn interest on their €100. They give each other credit, so that Eve can borrow €100 from Adam, and Adam can borrow €100 from Eve. They don’t need to keep money in their current accounts, so they deposit their funds into a savings account and earn interest. Everybody wins: Eve, Adam, and of course, that snakelike creature.

Initially, Eve and Adam had no savings, only money in their current accounts. The advisor’s scheme allows them to fabricate savings out of credit. It seems like creating money, but Eve and Adam gave each other credit. They agreed to pay later, which exposed both to credit risk. One of them might not repay because you can do so many different things with €100 than put it in a savings account. You can use credit, which is an agreement to pay later, like money. And so, Paradise was lost. Similar schemes exist on a larger scale. These are shadow banks. Shadow banks don’t create money but credit. The difference between fractional-reserve money and this type of credit may not be significant in practice, except that this type of credit is unregulated, resulting in little oversight.

When banks create money, they do the same. The banks act as intermediaries between Eve and Adam, allowing them to lend money to each other even when they do not conduct business together or do not trust each other. The bank also assumes the risk that a debtor will fail to repay and receives a reward in the form of interest. It is also credit, but we refer to it as money because the law regards bank credit as legal tender, thus money. The government backs this scheme, as a stable financial system is a key public interest. Banks must have sufficient capital and reserves to meet emergencies. For that reason, banks are subject to regulations, while shadow banks are not subject to these rules, allowing the latter to offer more competitive interest rates.

The role of traditional banking has declined. Large corporations can borrow funds in money markets at rates better than those offered by banks. At the same time, retail investors can invest directly in money markets and get better yields than banks offer. This development started with corporate borrowing. It later expanded into mortgages. The reason for regulating banks is that they operate the payment system, which is of public interest, and can borrow from the Fed. Regulations prompted banks to take on off-balance-sheet risks to generate higher returns on their capital. Offering an emergency credit line to a shadow bank generated profits while not appearing on the balance sheet, exposing the bank to more risk than its balance sheet would suggest.

The 2008 financial crisis originated in shadow banks that invested in risky assets, rather than conventional banks that create money through lending. Shadow banks aren’t subject to the same regulations as traditional banks, so they made speculative investments in mortgages. These investments appeared safe because rating agencies failed to do their jobs. Regular banks encountered trouble because they had guaranteed emergency credit to shadow banks, which was legal but as dangerous as keeping these mortgages on their own balance sheets, which was illegal. It allowed banks to make more money from the same capital. Money creation, therefore, wasn’t the problem, and replacing regular banks with shadow banks could further destabilise the financial system.

If a financial crisis were to occur, with loan write-offs, full-reserve banking would only ensure that money in current accounts is safe. However, the same problems would emerge in savings accounts. Savings banks can expose themselves to off-balance-sheet risks unless such exposure is forbidden. They can also go belly up. And they did. If a bank’s debtors fail to meet their obligations, the bank may face financial difficulties, and the savings it holds may be at risk. Also, with full reserve banking, governments and central banks may end up supporting savings banks and even shadow banks to ensure financial stability, thereby rendering the benefits of full reserve banking void. After all, the initial cause was never a liquidity problem, but a solvency issue.

Commercial versus investment banks

The Glass-Steagall Act in the United States severed linkages between regular commercial banking and investment activities that contributed to the 1929 stock market crash and the ensuing depression. Separating banking from investing can prevent banks from providing loans to corporations in which they have invested. The measure aimed to make bankers more prudent. The separation of commercial and investment banking prevented securities firms and investment banks from taking deposits. The reason for the separation was a conflict of interest arising from banks investing in securities with their own assets, namely, their account holders’ deposits. Banks were obliged to protect account holders’ deposits and were not permitted to engage in speculative activities.

The Glass-Steagall Act included the Federal Deposit Insurance Corporation (FDIC), which guaranteed bank deposits up to a specified limit. It also comprised Regulation Q, which prohibited banks from paying interest on demand deposits and capped interest rates on other deposit products. Maximising interest rates can limit the risks banks are willing to take on loans, as these risks can destabilise the financial system.

Until the 1980s, the legislation mainly remained unchanged. With the rise of neoliberalism, government regulation came to be increasingly disapproved of. Hence, the Glass-Steagall Act was increasingly disregarded, and diligent deregulators repealed it in 1999 as part of their effort to relieve businesses of government regulations that stood in the way of corporations’ profits. Regulation Q ceilings for all account types, except demand deposits, were phased out during the 1980s. After the 2008 financial crisis, a renewed interest in the Glass-Steagall Act emerged. It is a sound idea.

In the United States, money market funds circumvented the limits imposed on banks by Regulation Q, luring depositors with higher interest rates, thereby undermining the prudent banking paradigm. And banks would sell these funds mortgages they preferred not to keep on their own balance sheets, creating a moral hazard that could lead to fraud. The money market funds, which are shadow banks, invested in collateralised debt obligations (CDOs), such as mortgage-backed securities (MBS). The 2008 financial crisis started in money market funds, not traditional banks.

Natural Money works with the same principles. It distinguishes between regular banks, which provide loans, and investment banks, which are partnerships that invest in equity. Islamic banks also operate similarly. The maximum interest rate of zero works like Regulation Q, aiming to limit the risks banks are willing to take on deposits, as interest is a reward for taking on risk. Banking in a Natural Money financial system works as follows:

  • Regular banks make low-risk loans. The money in these banks is secure. The maximum interest rate is zero. And so, deposits have negative yields.
  • Investment banks don’t lend but participate in businesses by providing equity. They can rent houses and lease cars. Investment banks offer higher returns.
  • Both regular banks and investment banks can invest in government securities to manage their risk and meet withdrawals.
  • Regular banks can promise a fixed interest rate. The government may offer support and deposit guarantees.
  • Investment banks don’t guarantee returns. They pay dividends based on their profits. Its depositors are investors who can face losses.

Natural Money enhances financial stability by favouring equity investments over debt investments. The maximum interest rate makes debt investments less attractive. And there is no reward in the form of interest for engaging in high-risk lending, which enhances the financial system’s stability. It stands to reason that the integrity of the system depends on strict adherence to its principles and the termination of evasive, get-rich-quick schemes by financial parasites, which requires belief in the vision behind a usury-free economy. Let’s not dismiss that as a fantasy beforehand. That would prematurely end an interesting thought exercise, and perhaps more than that.

Sanitation of banking

Usury contributes to the financial system’s instability. Imagine what a maximum interest rate of zero on debts can do. Only the most creditworthy borrowers can get a loan. You may need to save and build equity before applying for a mortgage, and that may be the only credit you can obtain. Even an overdraft may be impossible. That may seem harsh, but it is even worse when indebted consumers reach the point where interest payments take up all their income and they can’t make ends meet. If you want to buy something, you have to save for it. Likewise, corporations need to attract capital rather than debt to meet their liquidity requirements. The financial sector will shrink, and much of modern finance may become redundant.

That said, individuals and businesses may obtain better deals in the money market, allowing them to opt for this option rather than a bank. The distinction between traditional banks and shadow banks may blur. Traditional banks may need fewer regulations, while shadow banks may need more. That is because without interest, risk may disappear. The central bank may stand behind the payment system, but it need not stand behind the lending system. The implicit guarantee that central banks will buy debt and issue currency with a holding fee means the warranty will remain unused.

Two other themes emerged during the 2008 financial crisis: ‘too big to fail’ and ‘too complex to understand.’ Complexity and size are the outcome of competition. The failure of a large bank can bring down the financial system, and the products that traders in financial markets use to hedge risk or improve profitability can be complex. Our future civilisation could be simpler, so the sanitation of the financial system should encompass cooperation, simplification and diversification. It may look as follows:

  • There should be an exhaustive list of all legal financial products and their requirements. We shouldn’t allow other financial products to exist.
  • No bank should hold more than a certain percentage of the global market, and no bank should expose itself to more than a certain percentage of another bank.
  • Banks should share services where scale is crucial, such as technological infrastructure and advanced knowledge.

Smaller banks can achieve efficiency improvements by using the same technological infrastructure. As long as they are independent financial institutions, they may share an IT department and operate their businesses on the same software. It may even be a public infrastructure that banks share, allowing for cost savings while also enabling knowledge sharing and the implementation of measures related to issues such as fraud prevention. Another question is whether regular banks should be public or private, since they provide payment services. Likely, the maximum interest rate ensures deposit safety, but if that is not the case, digital currency accounts, which in the case of Natural Money, are accounts backed by government debt, can offer a safe alternative.

Latest revision: 3 November 2026

Featured image: Ara Economicus. Beverly Lussier (2004). Wikimedia Commons. Public Domain.

Fiscal and Monetary Policies

Economic cycles

Mismatches between supply and demand cause economic cycles. A harvest may fail, and food prices may rise, leaving us with less money to spend on other items. Mismatches can concern the supply and demand of money, capital, labour, raw materials or consumer products. Interest charges also contribute to economic cycles. Interest rates reflect the market for funds. Had all markets been perfect, economists lament, supply could adapt to demand instantly, and there would be no economic cycles. Not unlike many others, economists love fairy tales about a paradise where everything is perfect. And so, they may advise us to make markets perfect, so that an economic paradise will ensue.

Economic cycles manifest when supply and demand periodically become misaligned and eventually realign. Economists use the term equilibrium in their models to explain the relationship between supply, demand, and price. Models are simplifications of reality. There is rarely a stable equilibrium, and fluctuations in demand and supply cause changes in prices, inventories, and employment. There are several theories and explanations regarding those mismatches, economic cycles, and their effects. Most notably, money, credit and interest deserve attention. After all, Natural Money is a monetary theory.

According to Say’s law, supply creates its own demand because we make goods and services to use ourselves or to acquire other goods and services. It is most applicable to a simple barter economy. When money serves as a medium of exchange, we can postpone our purchases, leaving producers with excess inventory. Money hoarding can be a serious problem as it interrupts the circular flow of money. When money loses value, we are less likely to postpone purchases. It is why central banks aim for a bit of inflation. However, inflation shouldn’t be too high, as that can undermine trust in the currency.

Expectations are another factor. When consumers feel good about the future, they are more willing to spend on big-ticket items. Likewise, when investors expect brighter prospects, they anticipate higher profits, making them more willing to invest. Conversely, when consumers and investors are pessimistic, the opposite happens. And so, expectations can become a self-fulfilling prophecy. Likewise, when people expect a bank to collapse, it may collapse because that expectation triggers a bank run. Policymakers try to instil confidence in the system because a lack of confidence can break it. The reason is that credit means trust, and trust is what keeps the system going.

During good times, businesses and individuals tend to be confident. Credit is often available because businesses’ and individuals’ future income projections serve as the basis for banks to lend money. And so, companies and individuals can borrow more in good times. When the economy slows and their incomes decrease, they may struggle to make their interest payments. Consumers would have more disposable income without debt, since they wouldn’t have to pay interest. Similarly, businesses can go bankrupt even when they are profitable overall because of interest charges. And so, interest charges can exacerbate and prolong the bust.

Leverage contributes to the overall risk in financial markets. Liquid financial markets make it easier to enter and exit positions, leading investors to fantasise that it is safe to operate with leverage. If markets were not fluid, leverage appears more dangerous, as it would be more difficult to exit a position. For example, if you aren’t sure you can renew your mortgage after five years, you won’t buy a home. Liquidity enables risk-taking, thereby increasing the overall level of risk in the financial system. That can become apparent during a crisis. People who have to sell their home during a housing crisis may end up selling it at a low price, leaving them with a debt that takes years to repay. Therefore, maintaining a liquid market is crucial for its safety, and limiting leverage further enhances its security.

Bureaucratic interventions

In the wake of the Great Depression and World War II, government and central bank interventions have become standard tools for bureaucrats to manage the capitalist economy. Fiscal policies involve steering the economy through government expenditures. Ideally, it works as follows. When the economy is performing poorly due to sluggish demand, the government increases spending to boost demand. Conversely, when the economy is overheating due to excessive demand, the government reduces spending to curb demand. Likewise, central banks can lower interest rates to promote borrowing and boost demand, or raise interest rates to discourage lending and curb demand. These policies can have the following undesirable consequences:

  • The timing of the measures may be off, so by the time the measures are decided upon and take effect, the economy may already be on the desired path.
  • Politicians may interfere and press for increased government spending or lower interest rates to boost the economy and get them re-elected.
  • Central bank interventions cause market participants to take more risk because they expect the central bank to intervene.
  • Due to usury, debt levels increase, so once these policies become commonplace, there are no corrective measures to cleanse the system of its excesses.

By failing to periodically cleanse the financial system of its excesses, either through a debt jubilee or an economic depression, the economy becomes addicted to credit expansion, and the final collapse will be even more severe. As the US dollar is the world’s reserve currency, a collapse in trust in this currency can trigger a global economic apocalypse. Usury is the primary reason for fiscal and monetary policies, because interest on money and debts promotes a money shortage, driving a demand for credit. Debtors must repay more than they borrowed, but that extra money doesn’t exist. And so, governments and central banks fill the gap.

Due to usury, it has become a permanent requirement. To prevent a shortage of money or a liquidity crunch from materialising, governments borrow, and central banks print money. The shortage arises when the private sector fails to borrow enough to cover interest payments on existing debt. To counter the problem, the government can borrow and spend this money. Central banks can lower interest rates to make borrowing more attractive. They do so by buying up government debt, thereby decreasing the supply of government debt and increasing the supply of currency, which lowers interest rates because there is less debt and more currency to buy it with.

Economists assume that there is a natural interest rate at which the economy grows at its trend rate while inflation is stable. There is no direct way to measure or calculate the natural interest rate. Economists estimate it using their theories and models. The elusive natural interest rate is a crucial element in central bank decisions. The natural interest rate may differ from the actual interest rate due to credit in the financial system. Deviations from this rate trigger booms and busts. The interest rate below the natural rate can generate a boom. In that case, people borrow too much because interest rates are too low, leading to overspending and overinvesting. An interest rate above the natural rate can lead to a bust, resulting in underinvestment and underspending. By setting short-term interest rates and thereby influencing long-term rates, central banks steer credit creation.

The economy can do well by itself

With Natural Money, the economy can manage itself, making fiscal and monetary policies redundant. The holding fee removes the zero lower bound, thereby providing stimulus during economic slumps. The maximum interest rate curbs lending during economic booms, providing austerity. That mitigates business cycles. And so there will be fewer debt overhangs and financial crises. The market, combined with the price control of the zero upper bound, steers interest rates and the money supply, thereby reducing the role of central banks. The central bank’s currency will then become a unit of account or administrative currency. Natural Money has the following favourable consequences:

  • The holding fee on currency allows negative interest rates to provide stimulus, while the maximum interest rate imposes austerity by curbing lending.
  • As interest is also a reward for taking risks, a maximum interest rate will take away the incentive to take risks and limit lending to the safest borrowers.
  • In the absence of usury, debt levels don’t increase, while only the safest borrowers can borrow, resulting in fewer bad debts.

There is no need for governments to engage in deficit spending, except to provide liquidity in financial markets, as government debt, rather than administrative currency, serves as the source of liquidity. The holding fee makes owning administrative currency unattractive. Provided their finances are sound, governments can borrow at negative interest rates and earn interest on their debts. They could aim for the debt level giving the highest interest income. If market participants are willing to lend at -1% when government debt is 100% of GDP and at -2% when government debt is at 70% of GDP, the government could harvest 1% of GDP in the former case and 1.4% of GDP in the latter case.

It will be the end of fiscal and monetary policies. The economy will manage itself. Interest payments don’t create a need to take on additional debt. Governments and central banks may step in during a crisis to restore trust in the financial system and the economy, but whether such intervention will be necessary is unclear, as are the measures they may need to take, given the unlikelihood of crises and the unforeseeable nature of them, as the current estimate is that they won’t occur. Natural Money also doesn’t require central banks to do more than handle daily interbank transactions, since the holding fee eliminates demand for the central bank’s currency.

Latest revision: 4 November 2026

Der Untergang der Titanic. Willy Stöwer (1912)

Harbinger of Things to Come

In 2006 or 2007, a software upgrade of the disk controllers on the principal systems went wrong. For a week, they were out of operation. It was one of the biggest crises in the history of the government office CJIB, and perhaps the biggest of all. At the time, Kees and I were working on the systems renewal project at another location. The other database administrators dealt with the issue, as did many others. I knew there was a serious problem because we received regular email updates, but I didn’t realise how serious it was. After a week, the telephone rang at home. It was 9 PM. My wife, Ingrid, took up the phone. It was the IT director. He said there was an emergency and asked me to come to the office. His voice reflected fear. ‘As if the Titanic had hit the iceberg,’ Ingrid later noted.

I hurried to the office and arrived by 9:30 PM. Many people were still in. It was a massive crisis. There was an atmosphere of fear. The database administrator on duty, Dirk-Jan, brought me up to speed. I searched the database log files, found the error messages, and typed them into the Google search bar. In this way, I found an online document with the remedy. I then repaired the failures and brought the systems online one by one. Board members and senior managers were standing around me, watching me type. Solving the issue wasn’t complicated, but few people used Google to find the answer at the time.

I learned that the last backup was over a week old, and the mirror copy was offline. You may know what backups are and why you might need them, but you may not know what a mirror copy is. A mirror copy is a safety measure. If you own a computer or a mobile phone, it contains data. That data is on a device. In the early 2000s, it was usually a hard disk. If that disk fails, your data may be gone forever. If you lose some photographs of your late cat, you might feel sad about it, but after a few years, you get over it, perhaps after consulting your psychiatrist and taking a lot of pills.

Corporations can’t afford to lose their data. That would bankrupt them. Their business is their data. Without it, they are out of business. If you have a backup, only data after the latest backup may be lost, but that can still kill you, especially if you haven’t backed up for a week. We were a government agency, so loss of data wouldn’t have bankrupted us, but it would have been a national political scandal.

Corporate computers have multiple data storage groups in different locations. If one group catches fire or stops operating because of a failed software upgrade, the other groups still have the data. These groups are called mirror copies. We had two groups: the original and the mirror. You can imagine my bewilderment. We had no backup, and the copy wasn’t available. So much had gone wrong that it was a miracle that I succeeded in recovering all the data. But having no mirror and no backup meant we were still on the brink.

An even greater surprise was yet to come. The managers and the board wanted to return to business as usual and run the backlog of batch jobs. Then I said, ‘This is perhaps the most important advice I will ever give in my entire career. Don’t start the batch jobs yet. We are on the proverbial edge of the precipice. Running the jobs might just push us over. Everything went wrong for a week and there is no guarantee whatsoever that it will be all right now. We should bring the mirror copy back online and make a backup first.’

They planned to ignore my advice. Bringing the mirror copy back online and taking a backup would take eighteen hours of precious time. It was a lot of data to back up, as it was everything we had. I was a low-ranking official while the IT director had claimed there was nothing to worry about. But he had left the building. I kept stressing that making a backup was the right thing to do. ‘If something goes wrong that could finish us,’ I told them. It was the worst crisis ever. And so, I pressed for an extensive check-up to see if everything was in order. On that, they could agree.

During the check-up, I found another failure that everyone had overlooked. That scared the managers and the board, prompting them to start another meeting. And then they followed my advice. The IT director was no longer there, and they faced a determined saviour who told them in no uncertain terms that they were about to do something stupid. The operators brought the mirror copy online and made a backup before we resumed normal operations. In this way, rational decision-making prevailed. Nothing went wrong anymore, but no one could have known that beforehand.

If it had gone wrong, the agency would have survived. Operations would likely have had to stop for several weeks—that had already happened for a week—and it may have been impossible to recover all the data. That would have made the headlines. But it never came to that. When the local newspaper’s journalists smelled a rat, the board could tell them that the situation was under control and that the data was safe. My wife’s comparison of this situation to the Titanic hitting an iceberg was not entirely apt. Saving the Titanic once it had hit the iceberg was technically impossible. It would have required a miracle. What I did may have appeared to be a miracle, but it was technically possible.

The audit department later evaluated the crisis. The auditors noted that after a week of failures, all the problems suddenly vanished, which they found already hard to believe. What they found even more difficult to fathom, and they stressed the inconceivability of it during a meeting, was that after a week of irrational decision-making, sanity suddenly took hold as we had brought the mirror copy back online and made a backup. They couldn’t figure out why that happened. Our management had kept them entirely in the dark. I didn’t enlighten them either, as it would make our management and board appear incompetent.

My manager, Geert, complimented me for handling the situation. He stressed that my colleagues had been content with me. ‘I was a pleasant colleague,’ he added. Strangely enough, Geert didn’t say something like, ‘Your contribution was critical in saving us from a disaster.’ It reveals something about Geert’s thinking. To him, it was teamwork. Geert wasn’t present that evening, so he may not have learned the details of what transpired. And so, it didn’t help my career. A few years later, the senior database administrators received a higher salary grade, except me. Geert was involved in that decision. If you save people from their own stupidity, you shouldn’t expect gratitude. In this case, the truth had remained hidden because it would have hurt the egos of those in charge. My dealings with the crisis could be a harbinger of things to come.

Latest revision: 25 February 2026

Featured image: Der Untergang der Titanic. Willy Stöwer (1912). Wikimedia Commons. Public Domain.